



Wed, 4th Sep ’24
GAS
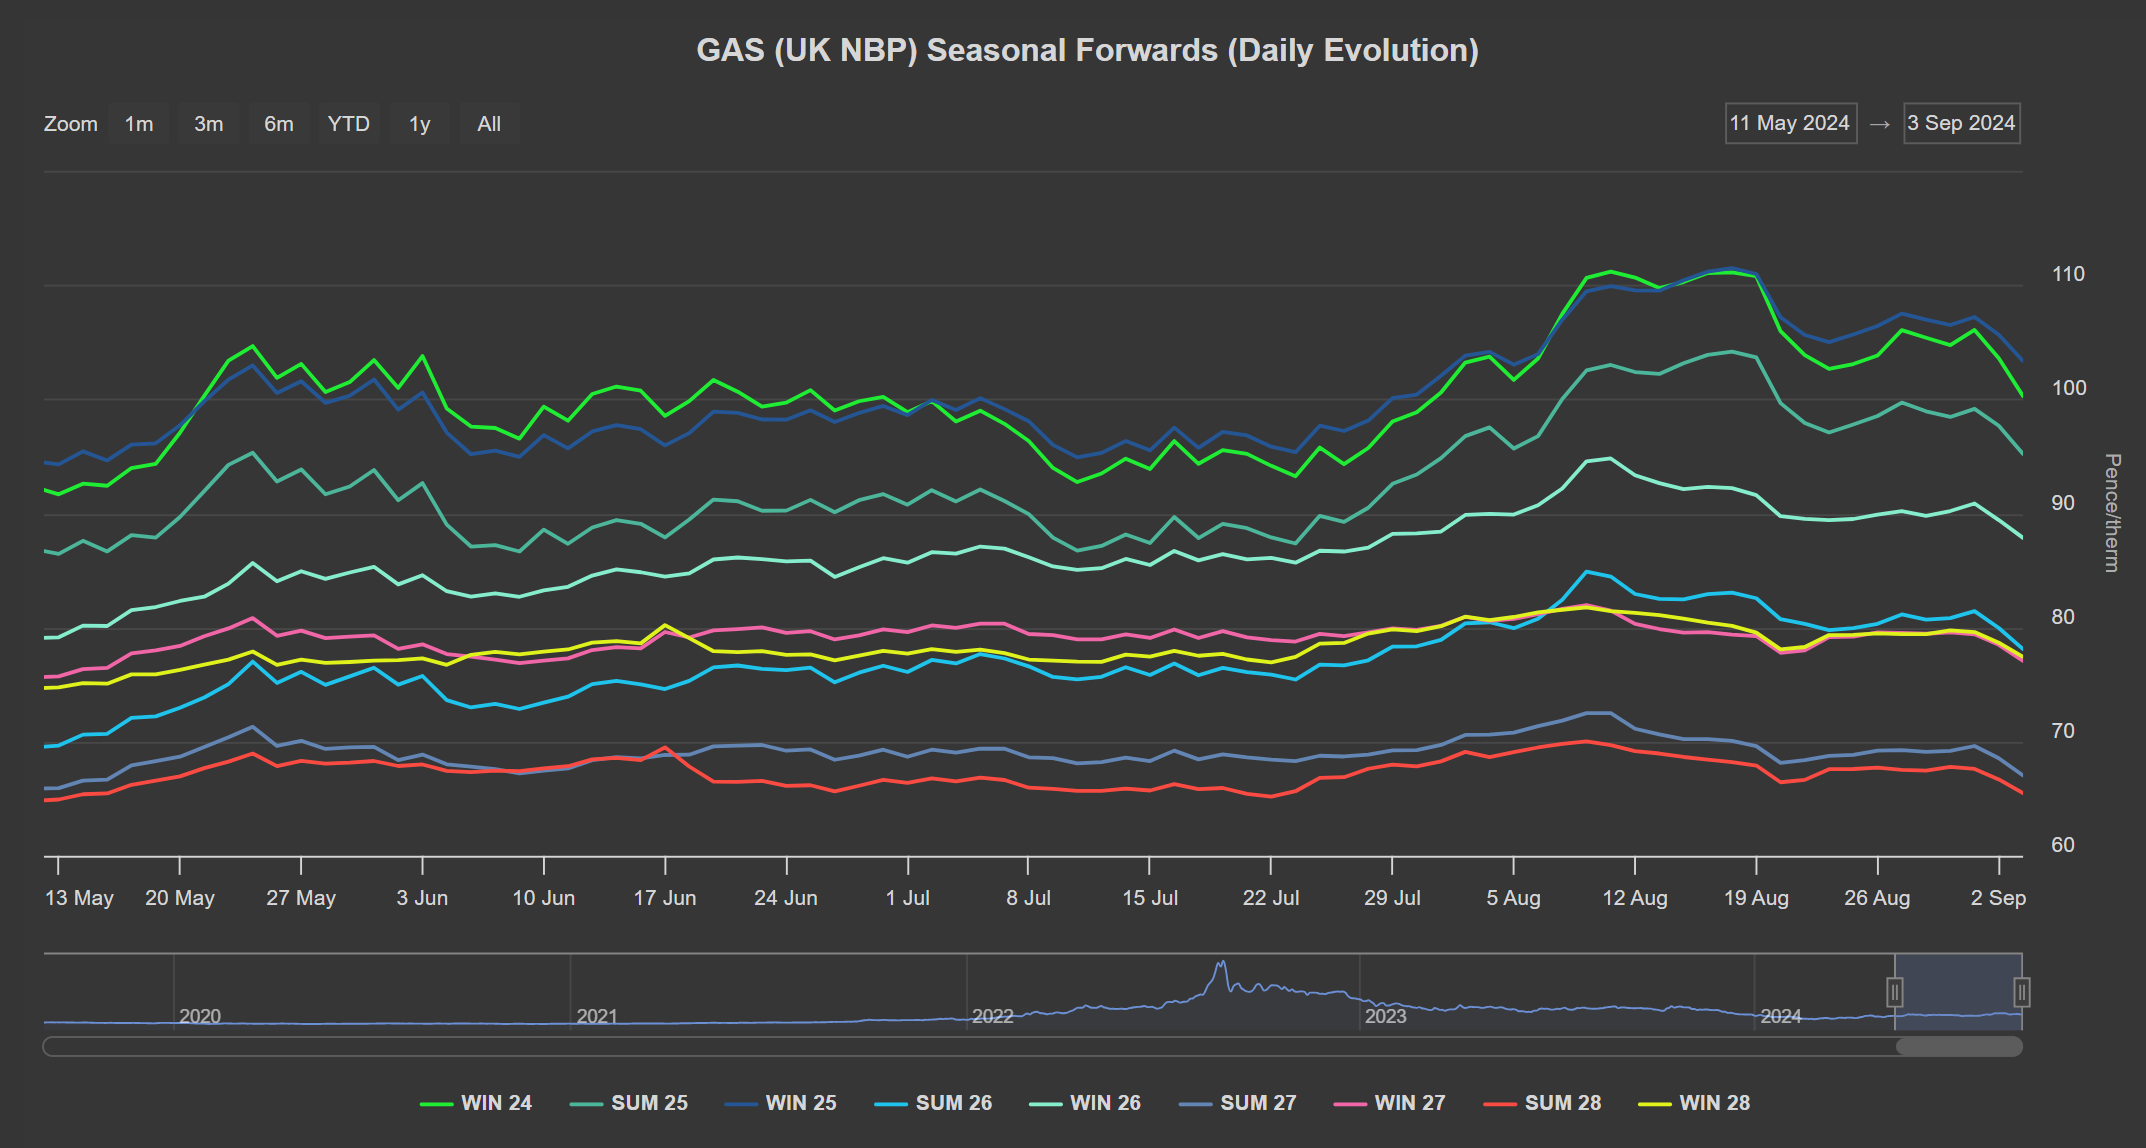
- The increasingly unpredictable (and contrarian) movements of the European/UK gas markets persist – arguably reflecting a more speculative market condition where the participants (increasingly investment funds or “non-physical buyers”) are buying on the rumour, then selling on the news…
- It’s been a bearish session today with Winter-24 prices breaking below 100p/therm for the first time in over a month despite massively reduced Norwegian flows due to ongoing scheduled maintenance – with the Easington terminal offline until 16th September (meaning zero flows into the UK from Norway’s Langeled).
- Analysts are citing bearish drivers as being confidence in historically high European storage levels coupled with very low industrial and domestic demand.
- European storage is 93% versus the 5-year average of 82%.
- Industrial and domestic demand across Europe is around 20% below average levels for the 2017 to 2021 period.
- We’re expecting two more LNG arrivals to degasify at British terminals before 11th September which should provide a boost to supply (amid current supply constraints caused by Norway’s flows being offline).
- European LNG send-outs are forecast to be more than 20% higher in September compared to August – further evidence of a drop in cooling demand throughout Asia.
- Elsewhere it appears geopolitical risk premiums are easing with tensions in the Middle East and on the Ukraine-Russia border stabilising (for now).
- Clients with significantly open volumes for Winter-24 are in the minority – with most having opted to heavily hedge Positions with winter conditions now on the horizon.
- Monthly Day-Ahead averages so far this month are on target to achieve 93p/therm (or approx. 3.1p/kwh excluding non-gas).
ELECTRICITY & CARBON
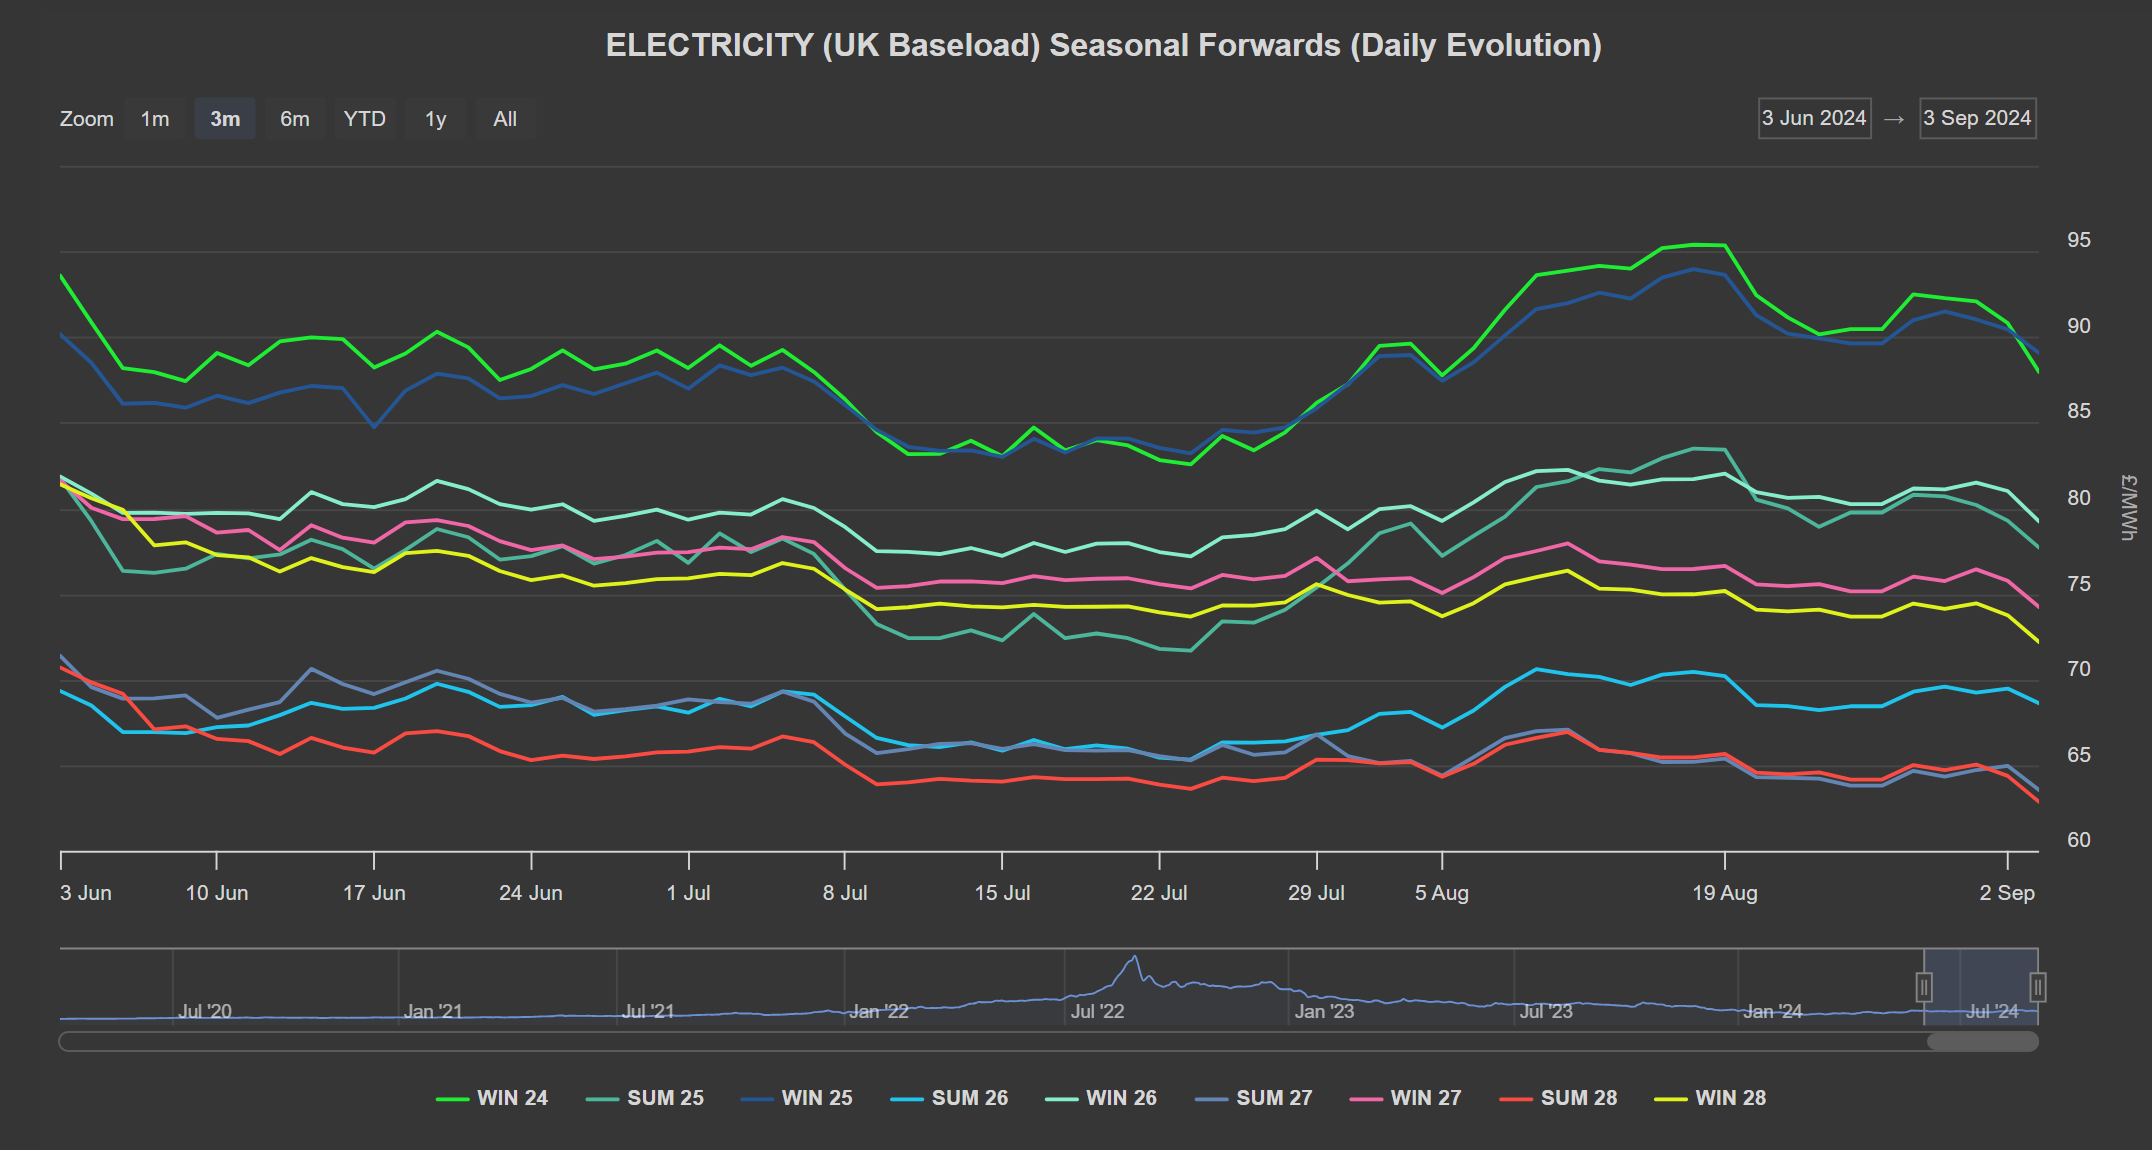
- On the carbon markets, the benchmark EUA Dec ’24 contract sold off yesterday, finally breaking below the psychological €70/tonne support level – closing at €68.16/t after losing -3.22%.
- Carbon’s bearish momentum has been atttributed to the decline of gas prices, thought the increased nuclear generation target from EDF certainly played a role, as it is the confirmation that thermal assets are losing further ground to low carbon energy sources for the upcoming months.
- High temperatures across Europe are still expected to persist until this weekend, especially in Germany.
- Down the curve, Forward prices also sold off yesterday as well – mirroring losses on both carbon and gas.
- UKAs have finally recognised (and emulated) the falling value of their more heavily traded European counterpart, having dropped to £41/tn today from £43/tn yesterday.
- Our electricity generation mix is bullish in nature today with renewables contributing 15%, thermal at 47% (gas and coal) and low carbon at 25% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £83/mwh (or approx. 8.3p/kwh excluding non-energy).