



Fri, 6th Sep ’24
GAS
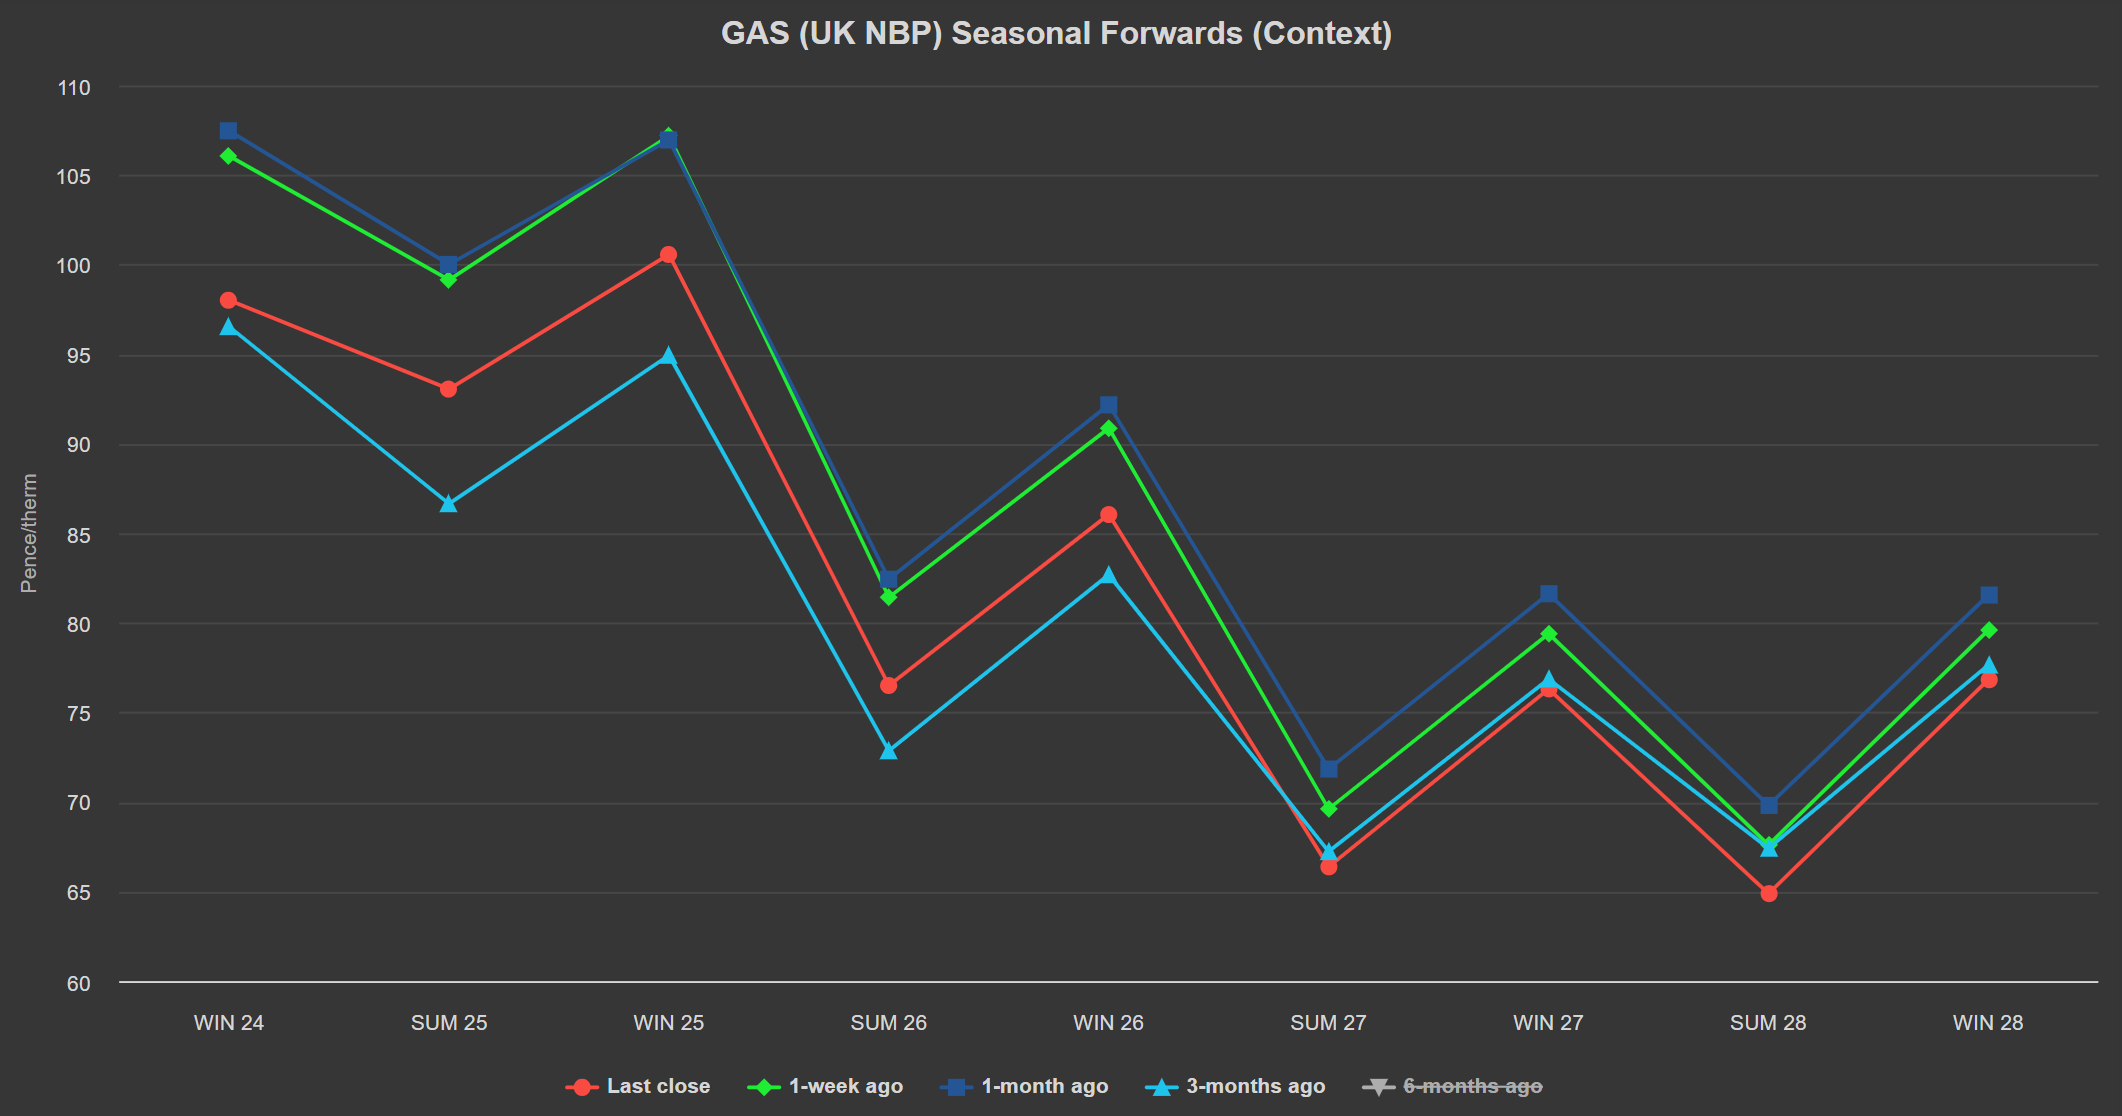
- It’s been sideways price action to end the week – with Seasonal Forwards now down on the week, down on the month, but up versus 3-months ago (see chart below).
- Heavy Norwegian maintenance continues to restrict supplies coming into the UK.
- LDZ (heating demand) dropped off today with temperatures reaching 26°C in some parts of the UK – 5°C above seasonal norms.
- Global competition for LNG has picked up again with Egypt looking to buy 20 cargos for delivery next month.
- Lest we forget, Europe and the UK have come to rely increasingly on continuous global gas flows since Russia turned off the taps back in ’22.
- However, strong EU storage (93% versus the 5-year average of 82%) continues to offset fears of impending supply tightness.
- Industrial and domestic demand across Europe is around 20% below average levels for the 2017 to 2021 period.
- We’re expecting two more LNG arrivals to degasify at British terminals before 11th September which should provide a boost to supply (amid current supply constraints caused by Norway’s flows being offline).
- European LNG send-outs are forecast to be more than 20% higher in September compared to August – further evidence of a drop in cooling demand throughout Asia.
- Elsewhere it appears geopolitical risk premiums are easing with tensions in the Middle East and on the Ukraine-Russia border stabilising (for now).
- Clients with significantly open volumes for Winter-24 are in the minority – with most having opted to heavily hedge Positions with winter conditions now on the horizon.
- Monthly Day-Ahead averages so far this month are on target to achieve 89p/therm (or approx. 3p/kwh excluding non-gas).
ELECTRICITY & CARBON
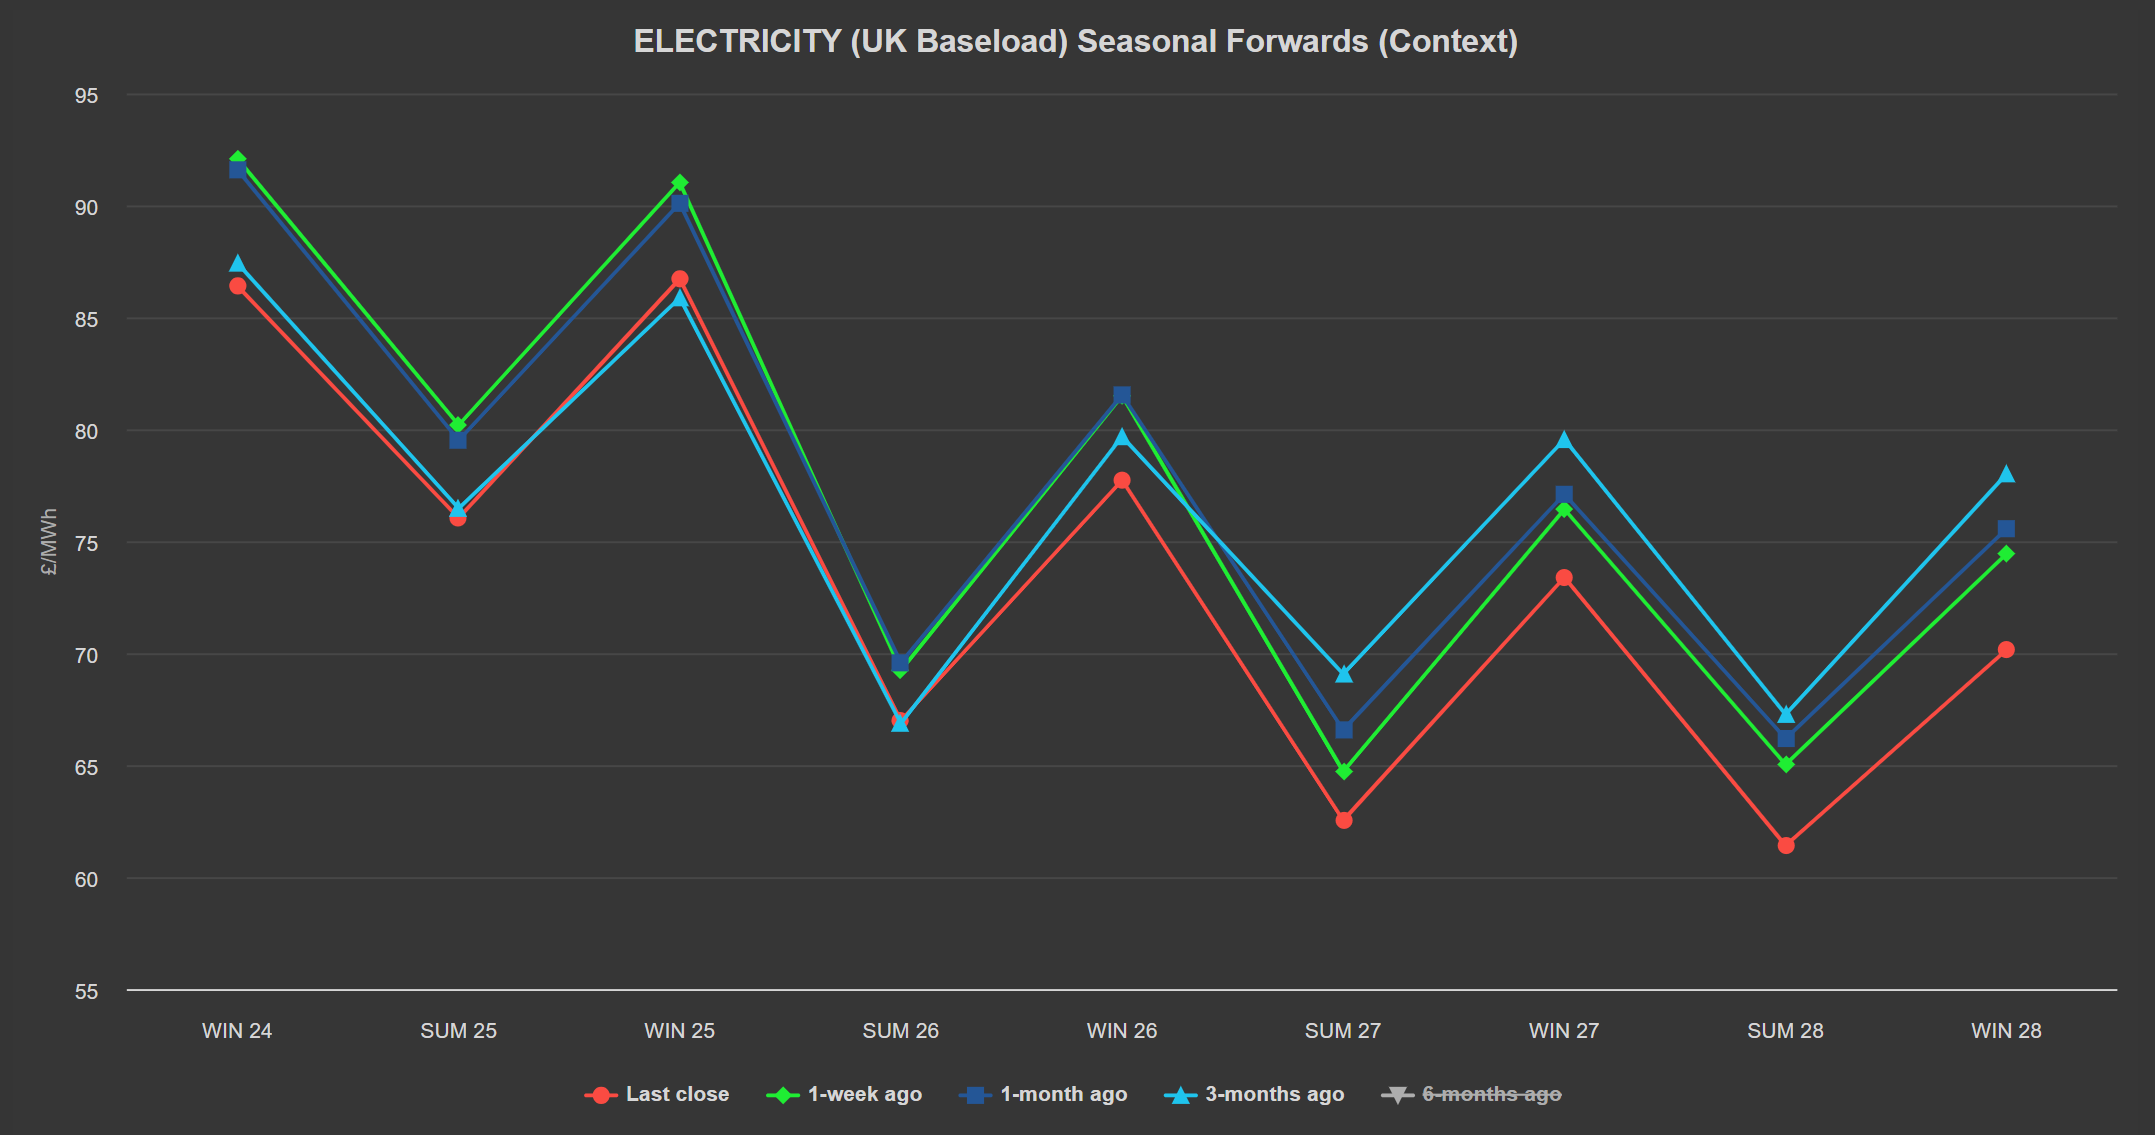
- Looking to the continent, European near-term delivery prices are trading a in a tight range.
- The weather outlook has revised colder for next week, with temperatures dropping 4°C below seasonal norms – increasing heating demand.
- Wind outputs look solid – limiting gas-for-power demand.
- As further evidence of directionless trading, carbon and gas moved in opposite directions yesterday.
- On the carbon markets, the benchmark Dec ’24 EUA contract has continued its slide to a six-week low – closing at €66.2/t after losing 1.1% on the day.
- UKAs have idled today at around £42/tonne.
- Our electricity generation mix has been neutral in nature today with renewables contributing 26%, thermal at 31% (gas and coal) and low carbon at 27% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £82/mwh (or approx. 8.2p/kwh excluding non-energy).