



Mon, 2nd Sep ’24
GAS
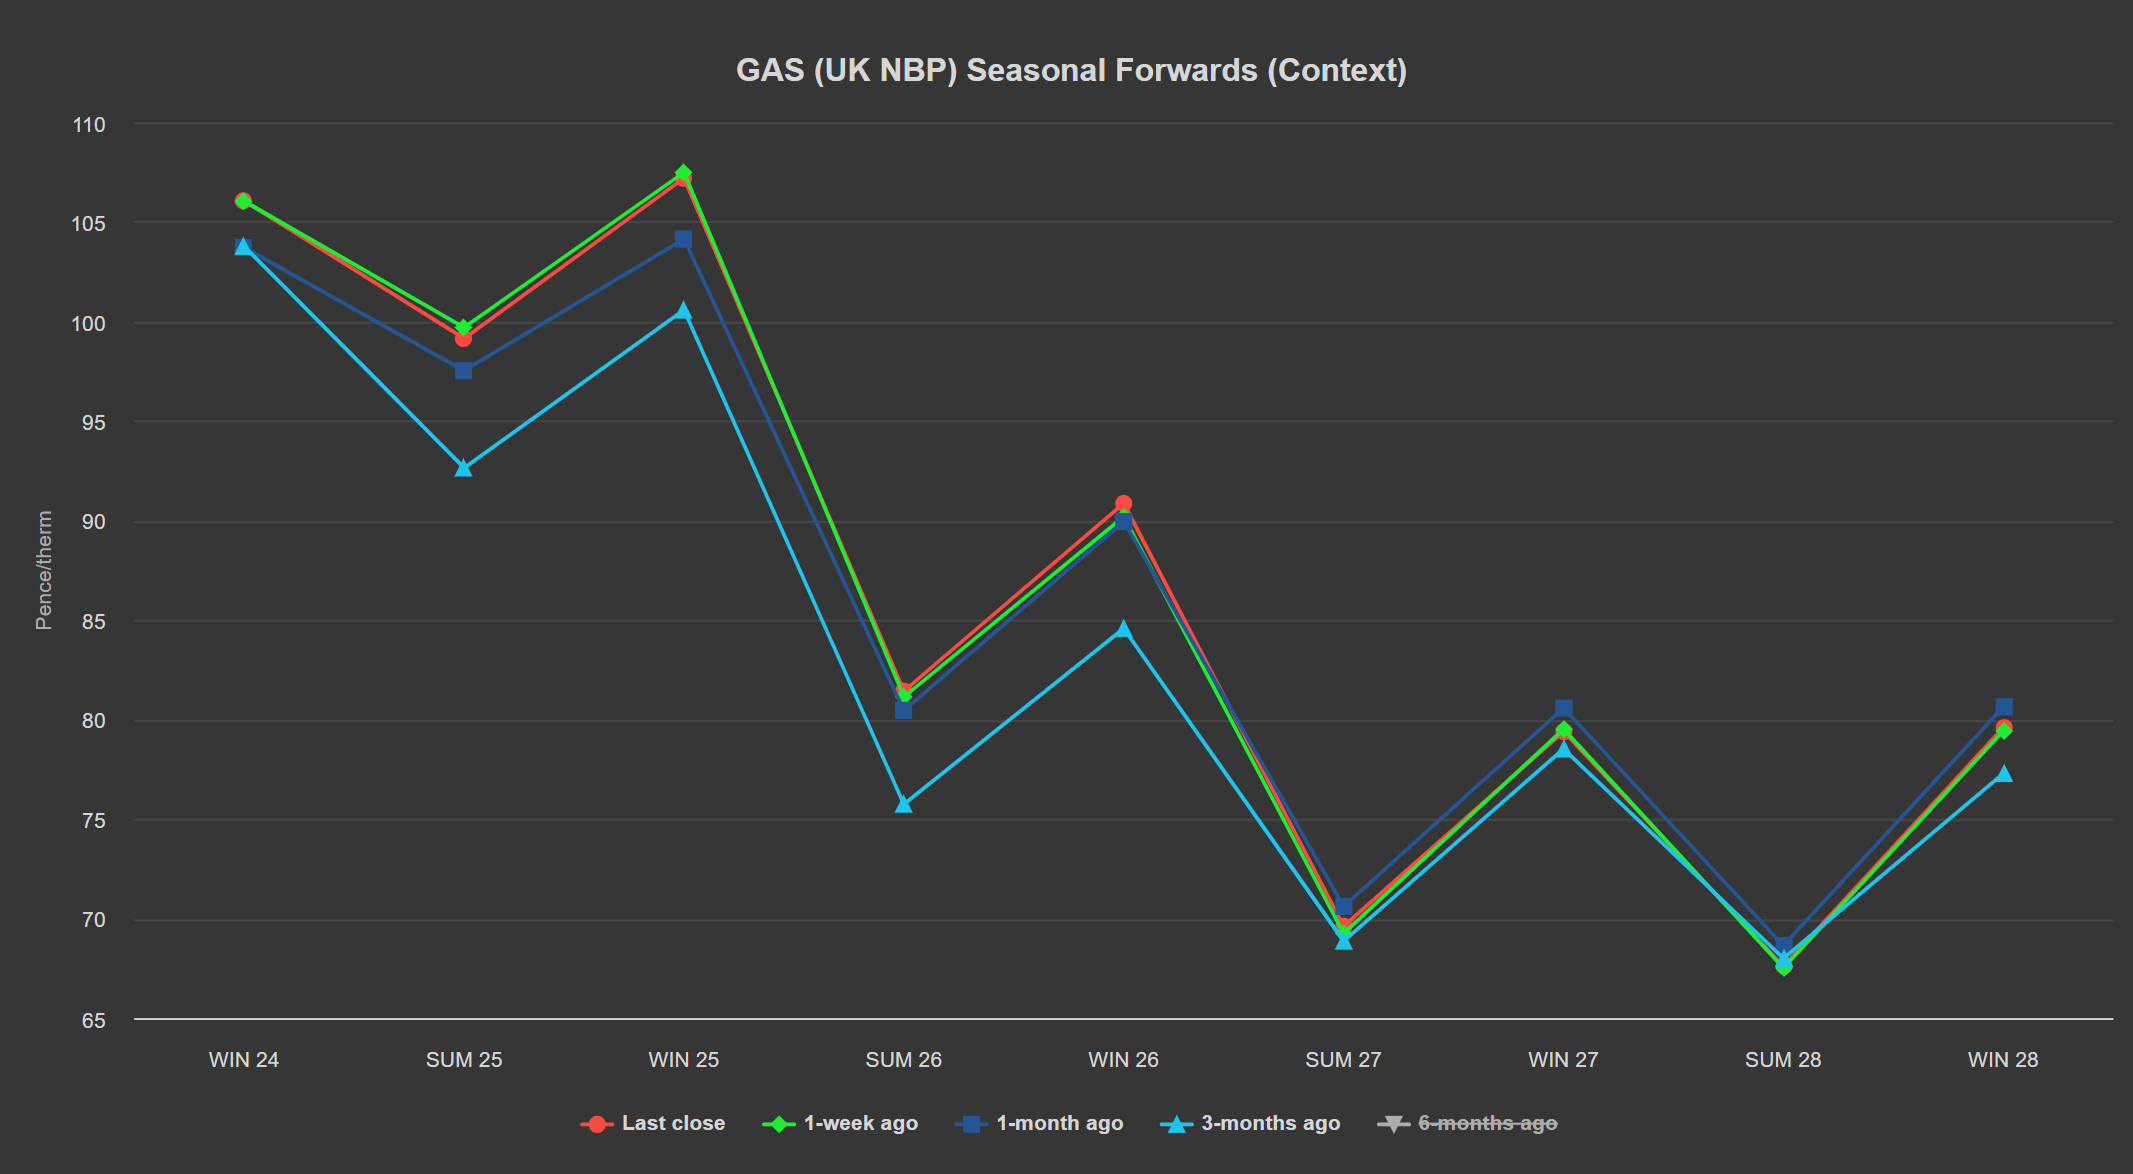
- Seasonal Forwards are down on the week, but up on the month/3-months ago (see chart below).
- Prices opened up this morning off the back of ongoing Norwegian maintenance (though the maintenance of the Kollsnes and Nyhamna gas-processing plants has been delayed).
- Most notably, the Easington terminal is offline for maintenance from today until 16th September, meaning zero flows into the UK from Norway’s Langeled.
- Not surprisingly then, the UK system opened short today despite demand being significantly below seasonal norms.
- Given reduced Norwegian flows, the UK is now withdrawing 24mcm from storage to help balance the grid.
- Accordingly, UK exports have reduced to retain volumes – this is set to continue, as the Interconnector will go offline for maintenance tomorrow (ending 18th September).
- Temperatures are set to turn gradually cooler as the week progresses, before warming at the weekend.
- Europe’s storage levels (92% full versus the 5-year average of 82%) continue to offset Europe’s demand for gas as the amount of LNG idling at sea for more than 30 days waiting to degasify is increasing – reaching 1.7 million tons last week (reflecting a glut).
- Three LNG arrivals from the US are expected to degasify at UK ports before 10th September – reflecting a drop in cooling demand throughout Asia.
- Clients with significantly open volumes for Winter-24 are in the minority – with most having opted to heavily hedge Positions with winter conditions now on the horizon.
- Monthly Day-Ahead averages for August achieved 85p/therm (or approx. 2.9p/kwh excluding non-gas).
- Monthly Day-Ahead averages so far this month are on target to achieve 94p/therm (or approx. 3.2p/kwh excluding non-gas).
ELECTRICITY & CARBON
- Looking to the continent for direction, European near-term delivery prices averaged €111.11/mwh for delivery today.
- Such high figures are among the highest power prices of the year.
- Elevated temperatures, low wind speeds and declining hydro generation are the supportive drivers.
- An increase in wind generation at the end of the week should help prices to trade lower.
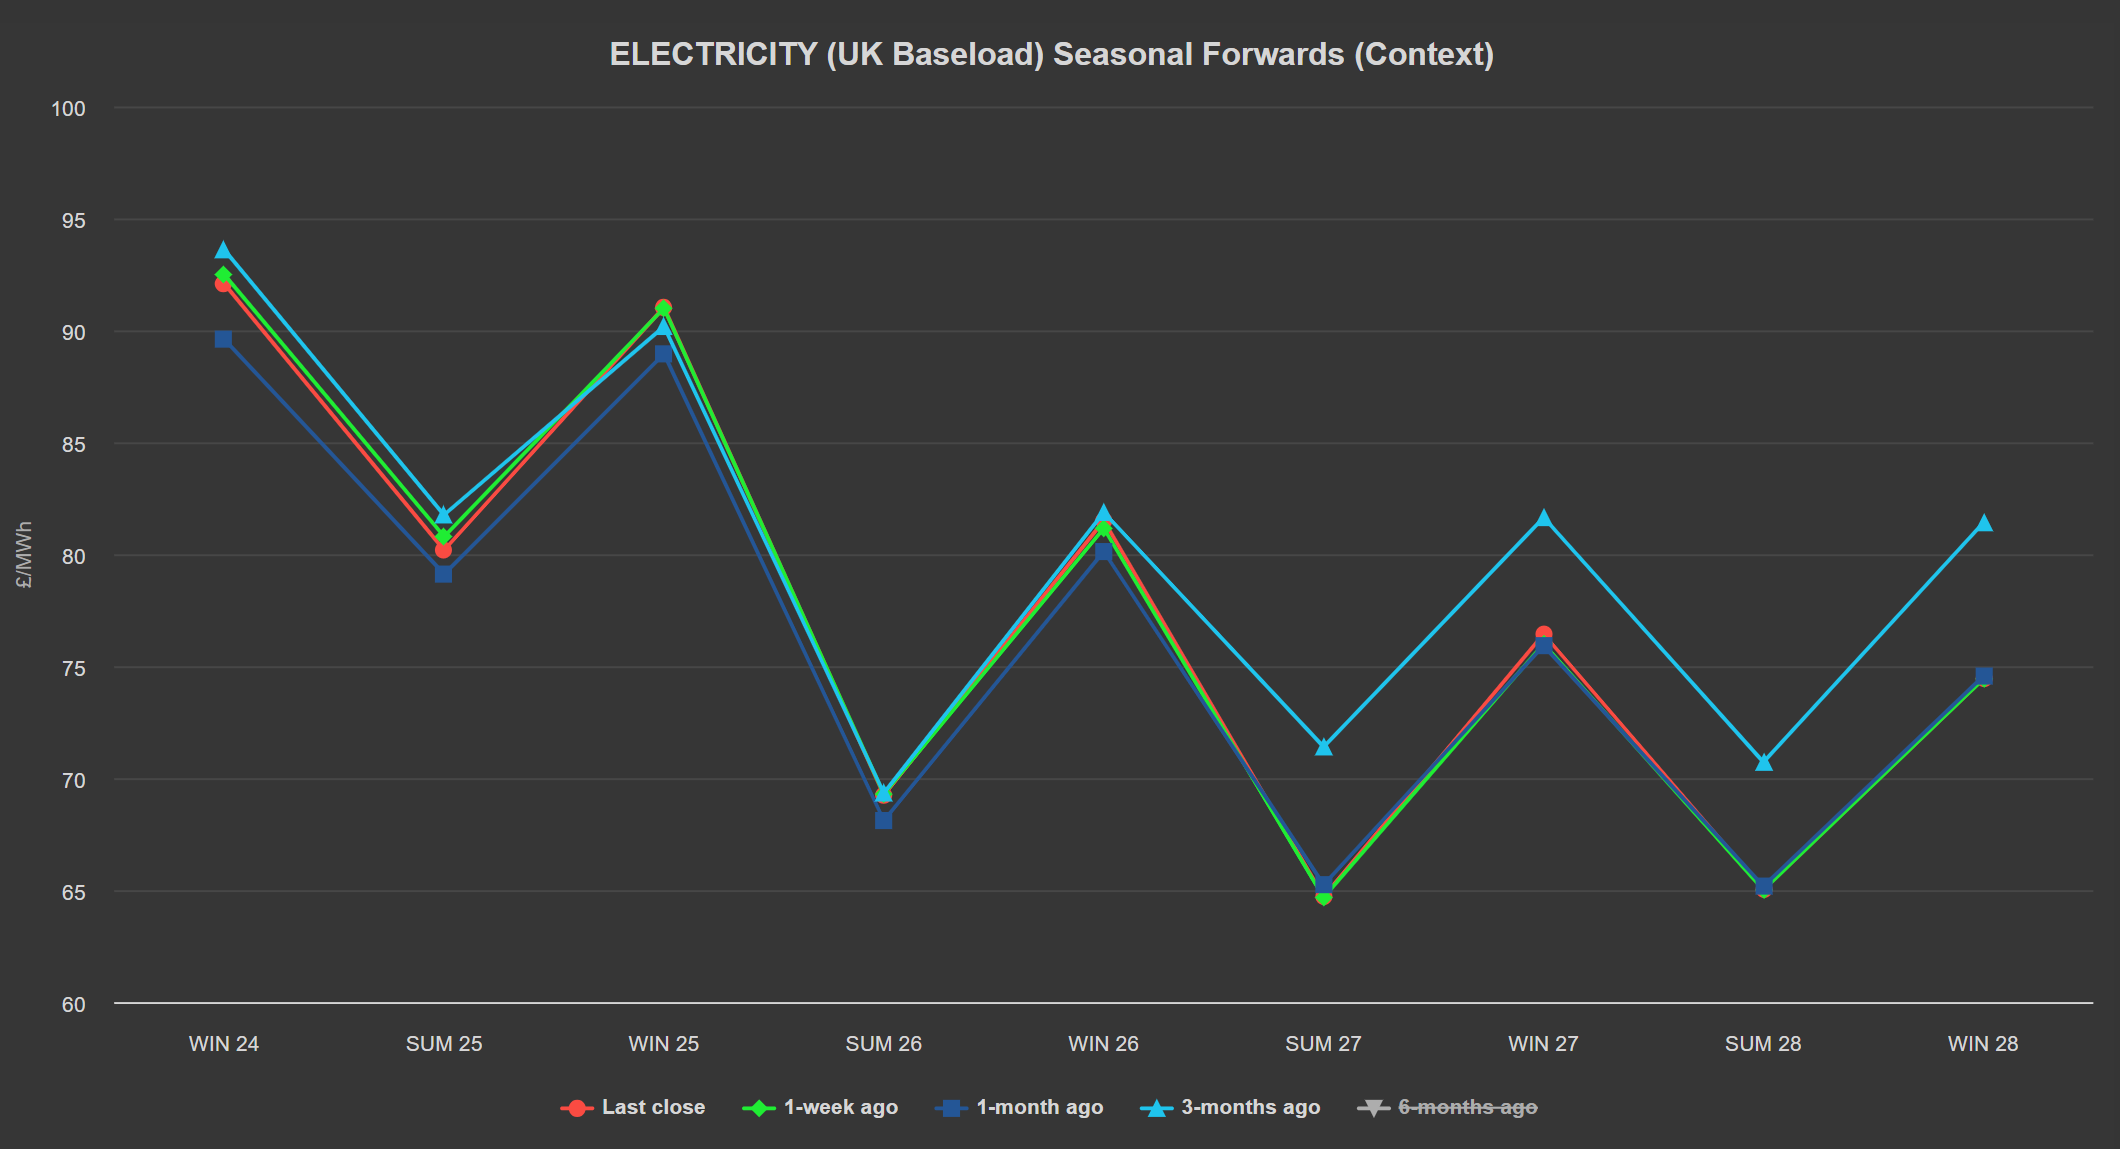
- Seasonal Forward prices were down last week following developments on the carbon side, and despite higher gas prices.
- On the Carbon markets, EUA’s are idling sideways, whilst UKAs are drifting higher.
- From a technical perspective, the €70/tonne support level for EUA Dec ’24 is still holding but has been retested countless times over the past week, increasing the likelihood of it being breached.
- And with a challenged correlation with gas, moves on EUAs seem even harder to anticipate.
- Conversely, UKAs seem set to approach relative value parity with EUAs, having risen to £43/tonne following the low achieved of £37 back on 9th August.
- Our electricity generation mix is bullish in nature today with renewables contributing 29%, thermal at 36% (gas and coal) and low carbon at 23% (nuclear and imports).
- Monthly Day-Ahead averages for August achieved £60/mwh (or approx. 6p/kwh excluding non-energy).
- Monthly Day-Ahead averages so far this month are on target to achieve £80/mwh (or approx. 8p/kwh excluding non-energy).