



Wed, 13th Mar ’24
GAS
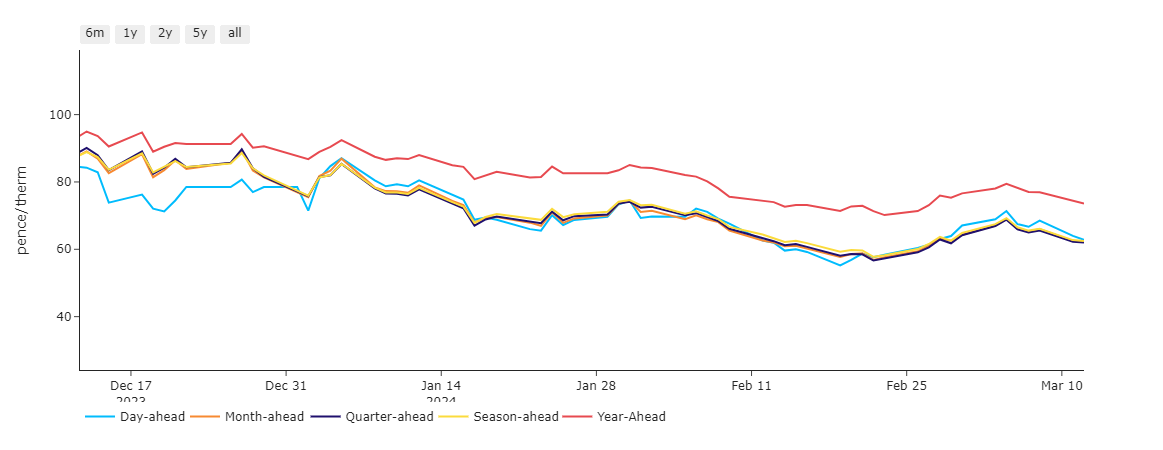
- As predicted (in the absence of heightened geo-political risk), markets continue to meander southwards.
- Last week’s short-covering has abated, and it’s as you were – with near-term delivery set to test the lows printed back on 22nd Feb (see chart).
- Both Europe and the UK are expecting temperatures above seasonal norms for the rest of March against a backdrop of weaker demand (Industrial and domestic).
- Volumes of LNG crossing European waters waiting to degasify has risen sharply by 27% w-o-w to circa. 3.5 m/t (million tonnes).
- European inventories remain at historical highs – 61% fullness versus the 5-year average of 45%.
- Demand forecasts remain below seasonal norms and the UK system is long at the time of writing (supply outstripping demand).
- On the supply side, it’s very comfortable – the outage any Nyhamna having little impact on continually strong Norwegian flows.
- Geo-political risk is background noise, with lingering shipping disquiet in the Red Sea area – though LNG is mostly headed around the Cape of Good Hope.
- 18 days of Winter-23 remain, and buyers are looking to summer conditioning to further soften Winter-24 offers.
- Monthly Day-Ahead averages are on target this month to achieve 67p/therm (or 2.25p/kwh).
ELECTRICITY & CARBON
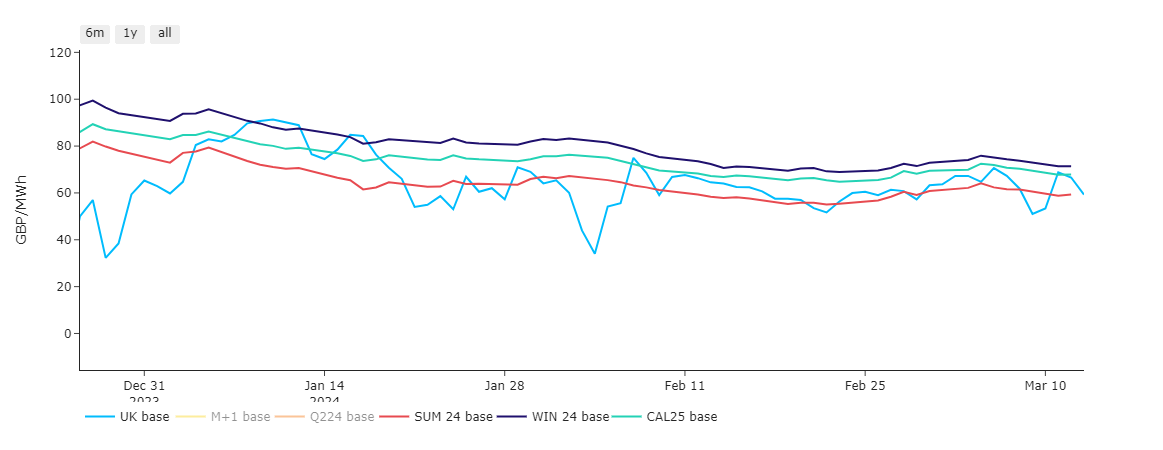
- As you’d expect heading toward summer conditioning, Day-Ahead is using Winter-24 delivery prices as a resistance level (see chart).
- Looking to the continent, European near-term delivery prices dropped off yesterday pressured by a resurgence in renewable outputs coupled with rapidly rising temperatures.
- Expect more of the same this week off the back of windier, sunnier, and milder weather conditions.
- Down the curve, markets are trading sideways having found a comfortable equilibrium – pressured by steady gas prices, buoyed slightly by firmer carbon.
- On the carbon markets, market particpants are eyeing either a further short squeeze or subject to the latest COT (Commitment of Traders report), we may find that short-covering has abated – as such, speculators are likely to rebuild their net-short position and we’ll see a retest of February lows.
- At the time of writing, Dec-24 contracts for UKAs are sitting at £38/tn.
- Our electricity generation mix is bearish in nature this morning with renewables contributing 53%, thermal at 16% (gas and coal) and low carbon at 20% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £65/mwh (or 6.5p/kwh).