



Fri, 15th Mar ’24
GAS
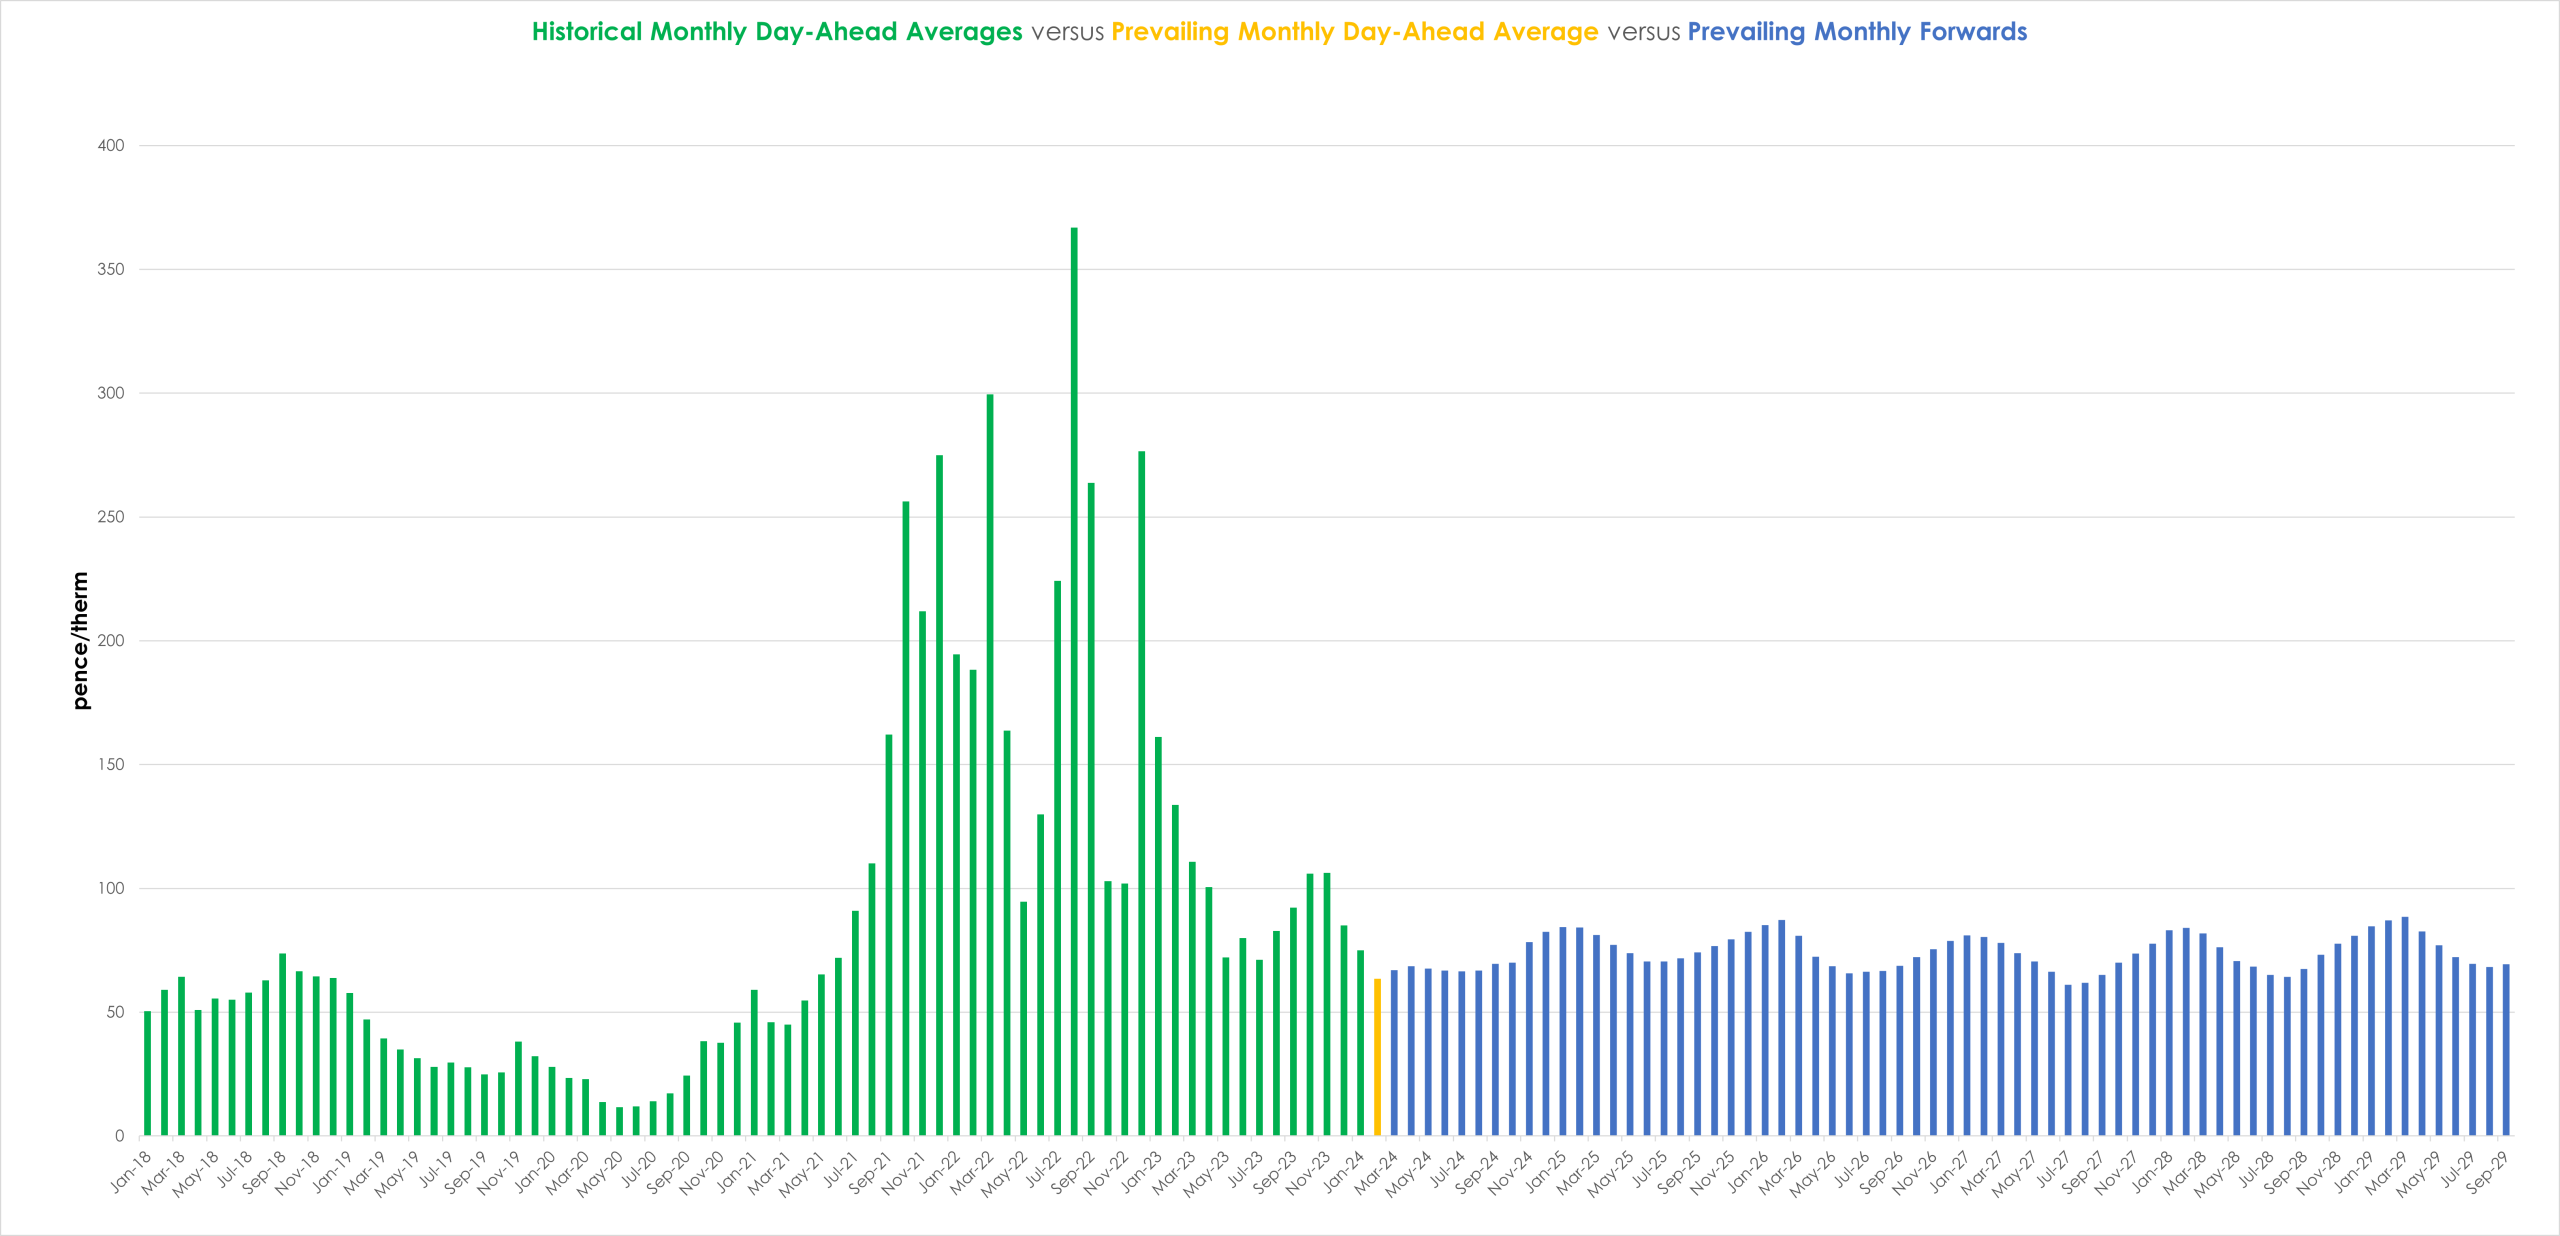
- Whilst the bigger picture remains overwhelmingly bearish, the last couple of days have seen prices well-supported – though gains have been very modest.
- Strong moves in the wider energy complex (fuels and emissions) have added some marginal value to near-term delivery gas contracts.
- Despite the UK system being long at market open (supply outstripping demand), prices rallied this morning – but have dropped back again to end the week.
- Most likely, prices have found their bottom for now and so market participants are bound to test support/resistance levels until such a time as the bulls or the bears take hold.
- In real terms, markets are balanced and enjoying comparative equilibrium versus the volatility that began in mid ’21 and only really abated at the back end of ’23.
- Down the curve, prices are a little firmer too – supported in the main by concerns over supply tightness as flows have dropped off to the Corpus Christi LNG facility (Texas, USA).
- Europe is heavily reliant on imports from the US, most of which come from Texas.
- Also, one of the trains at Freeport LNG (also Texas) remains offline – further limiting export capability.
- Temperatures are set to remain warm over the weekend and will stay above seasonal norms into next week – limiting heating demand.
- Norwegian flows remain steady and (due to the mild winter we’ve had) European storage has suffered little by way of withdrawals – with inventories at a record-breaking 60% versus the 5-year average of 40%.
- Geo-political risk has become background noise over the past few weeks, with lingering shipping disquiet in the Red Sea area – though LNG has been mostly rerouted around the Cape of Good Hope until further notice.
- With only 15 days of Winter-23 remaining buyers are looking to summer conditioning to further soften Winter-24 offers.
- Monthly Day-Ahead averages are on target this month to achieve 67p/therm (or 2.28p/kwh).
ELECTRICITY & CARBON
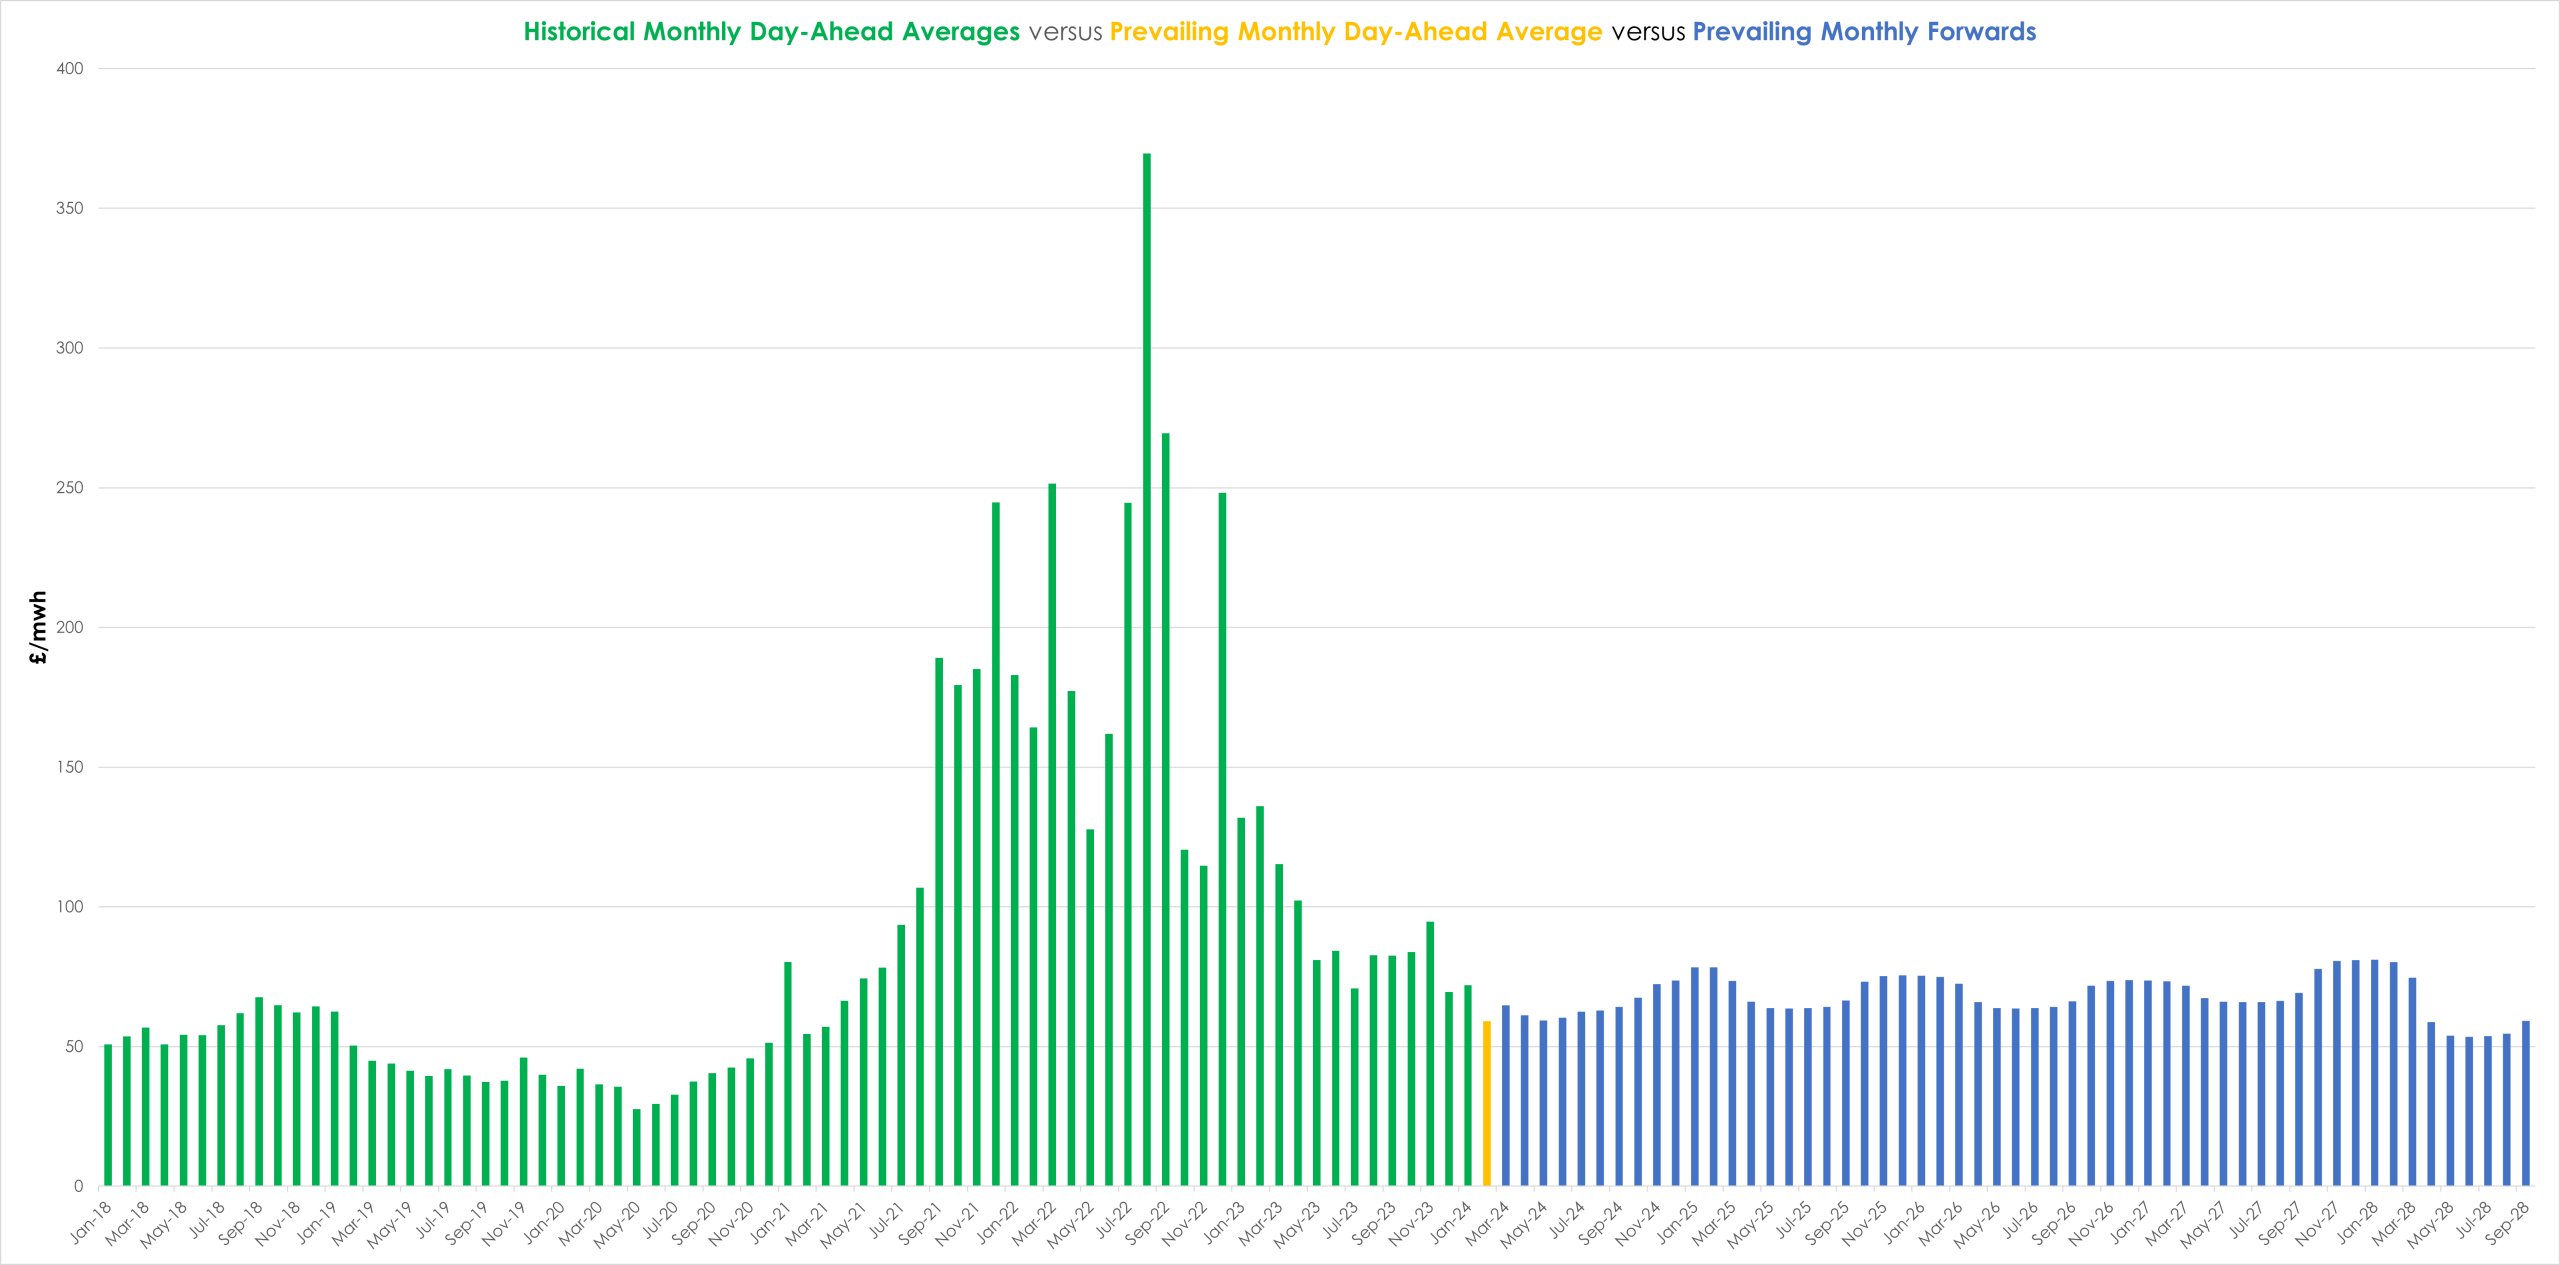
- Looking to the continent, rising temperatures and renewable production continued to weigh on short-term delivery prices in the latter part of this week – shedding circa. 20% in anticipation of lower demand and limited gas-for-power burn.
- Nonetheless, prices may find support next week with forecasts of colder temperatures and weak renewables outputs.
- Down the curve, markets firmed to end the week, though market participants struggled to identify a fundamental rationale for the upward movement, with some attributing it to potential positioning /short-covering.
- On the carbon markets, prices remain rangebound with neither bulls nor bears managing to break above/below established support/resitance levels.
- Any hope amongst bulls that carbon is ready for another rally seems premature – with many analysts preferinng to explain any upwards movement as market noise rather than a shift in fundamental sentiment.
- UKAs closed the week at circa. £40/tn – with the prevailing range at £45/tn to the topside (and £30/tn to the downside).
- Back in the UK, our electricity generation mix is bearish in nature to end the week with renewables contributing 43%, thermal at 18% (gas and coal) and low carbon at 25% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £65/mwh (or 6.5p/kwh).