



Mon, 11th Mar ’24
GAS
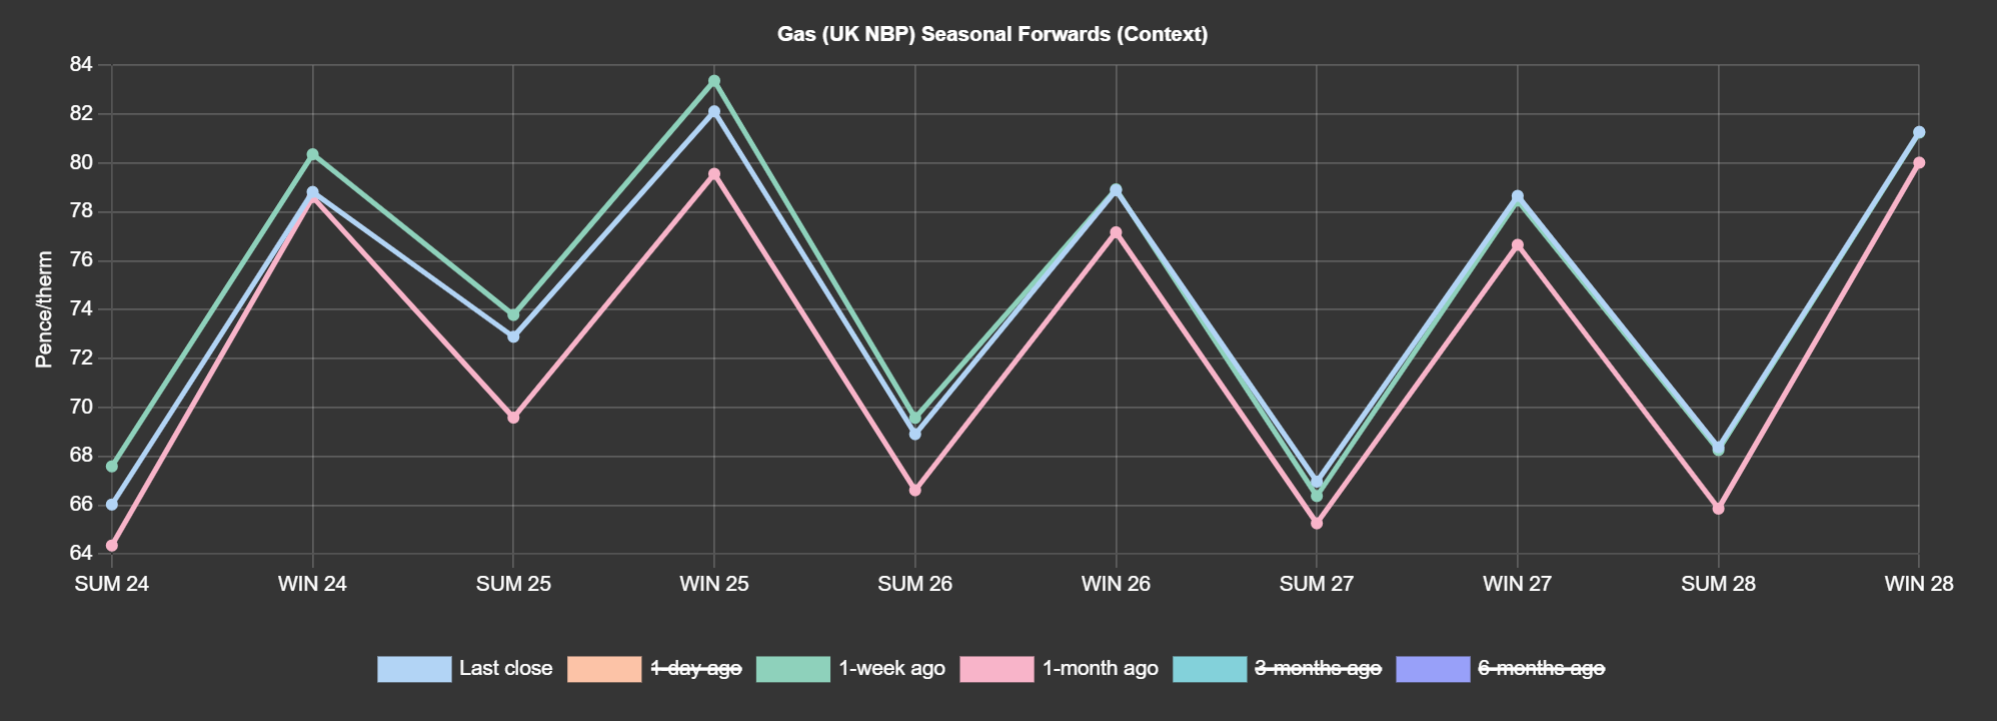
- Notwithstanding last week’s froth/noise, markets have resumed their downward trajectory this morning.
- Key drivers remain overwhelmingly bearish and Seasonal Forwards are little changed versus 1-week/1-month ago (see chart).
- On the supply side, European storage is at 61% versus the 5-year average of 41%.
- Norwegian flows remain high and steady (despite unscheduled outages at the Nyhamna field).
- The UK’s system opened short this morning – though demand remains below seasonal norms against a backdrop of temperatures remaining (in large part) above seasonal norms.
- In no small part due to the resurgence of Freeport and the introduction of additional capacity at Calcasieu, America is likely to remain the world’s leading supplier of LNG in 2024 – with forecasts adding 4% to the country’s annual exports to just under 50 m/t (million tonnes).
- Geo-political risk persists with ongoing shipping attacks in the Red Sea area – though LNG is mostly headed around the Cape of Good Hope.
- Russia’s flows are still missed, and their absence explains why markets haven’t fallen further (yet).
- Notably (and a bullish driver), China imported more than 20 million tonnes of natural gas in the first month of ’24 – equating to y-o-y growth of more than 20%.
- 20 days of Winter-23 remain, and buyers are looking to summer conditioning to further soften Winter-24 offers.
- Monthly Day-Ahead averages are on target this month to achieve 68p/therm (or 2.3p/kwh).
ELECTRICITY & CARBON
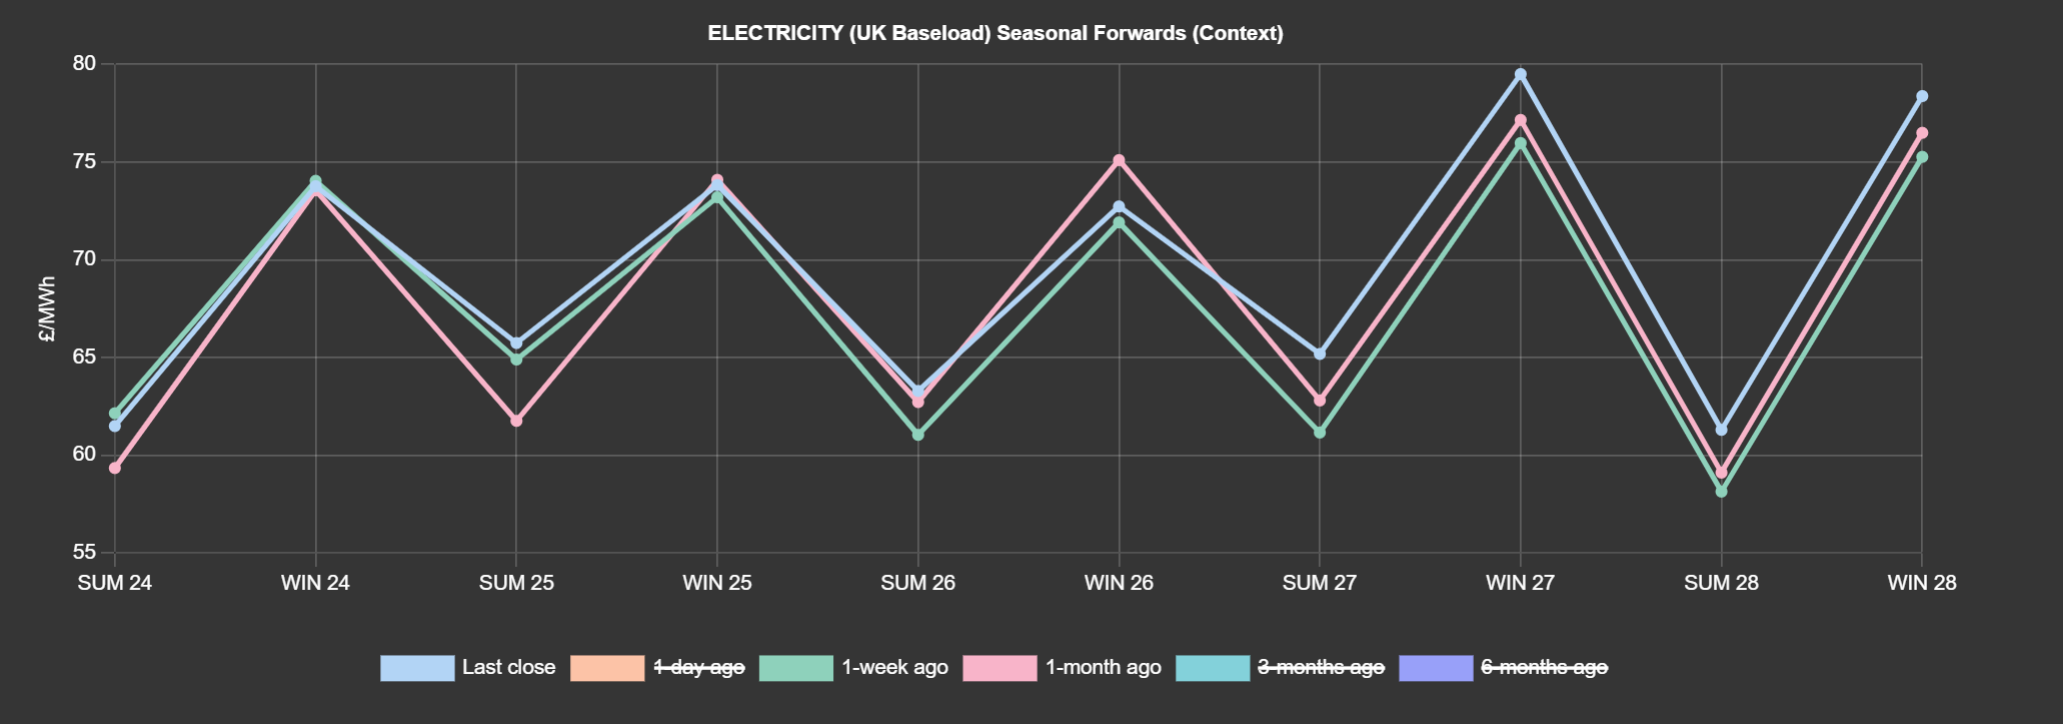
- Looking to the continent, European near-term delivery prices are marginally buoyed by decreasing renewables outputs alongside seaonal norm temperatures.
- The strength of the market is likely to be short-lived with improving renewables outputs and higher temperatures forecast by the end of the week.
- Down the curve, prices have resumed a bearish momentum following Friday’s short-covering rally – although with muted conviction (i.e., markets are stable and rangebound).
- Markets are weighed further by a warmer and windier revision of weather forecasts for the second half of March.
- In addition, bearish pressure is being exerted by the anticipation of the return of three French reactors by 23rd March, pushing the country’s nuclear availability back within historical range.
- On the carbon markets, allowances continued to gently fade in the final session of the week – though aggressive bears are being matched by bottom-hunting Industrial bulls looking to capitalise on the value on offer.
- UK Allowances closed last week around £35/tn – still testing support and resistance levels with a downside target of £30/tn, and an upside area of congestion circa £45/tn.
- At the time of writing, our electricity generation mix is bullish in nature with renewables contributing 15.3%, thermal at 50.5% (gas and coal) and low carbon at 21.9% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £65/mwh (or 6.5p/kwh).