



Mon, 14th Sep ’26
GAS
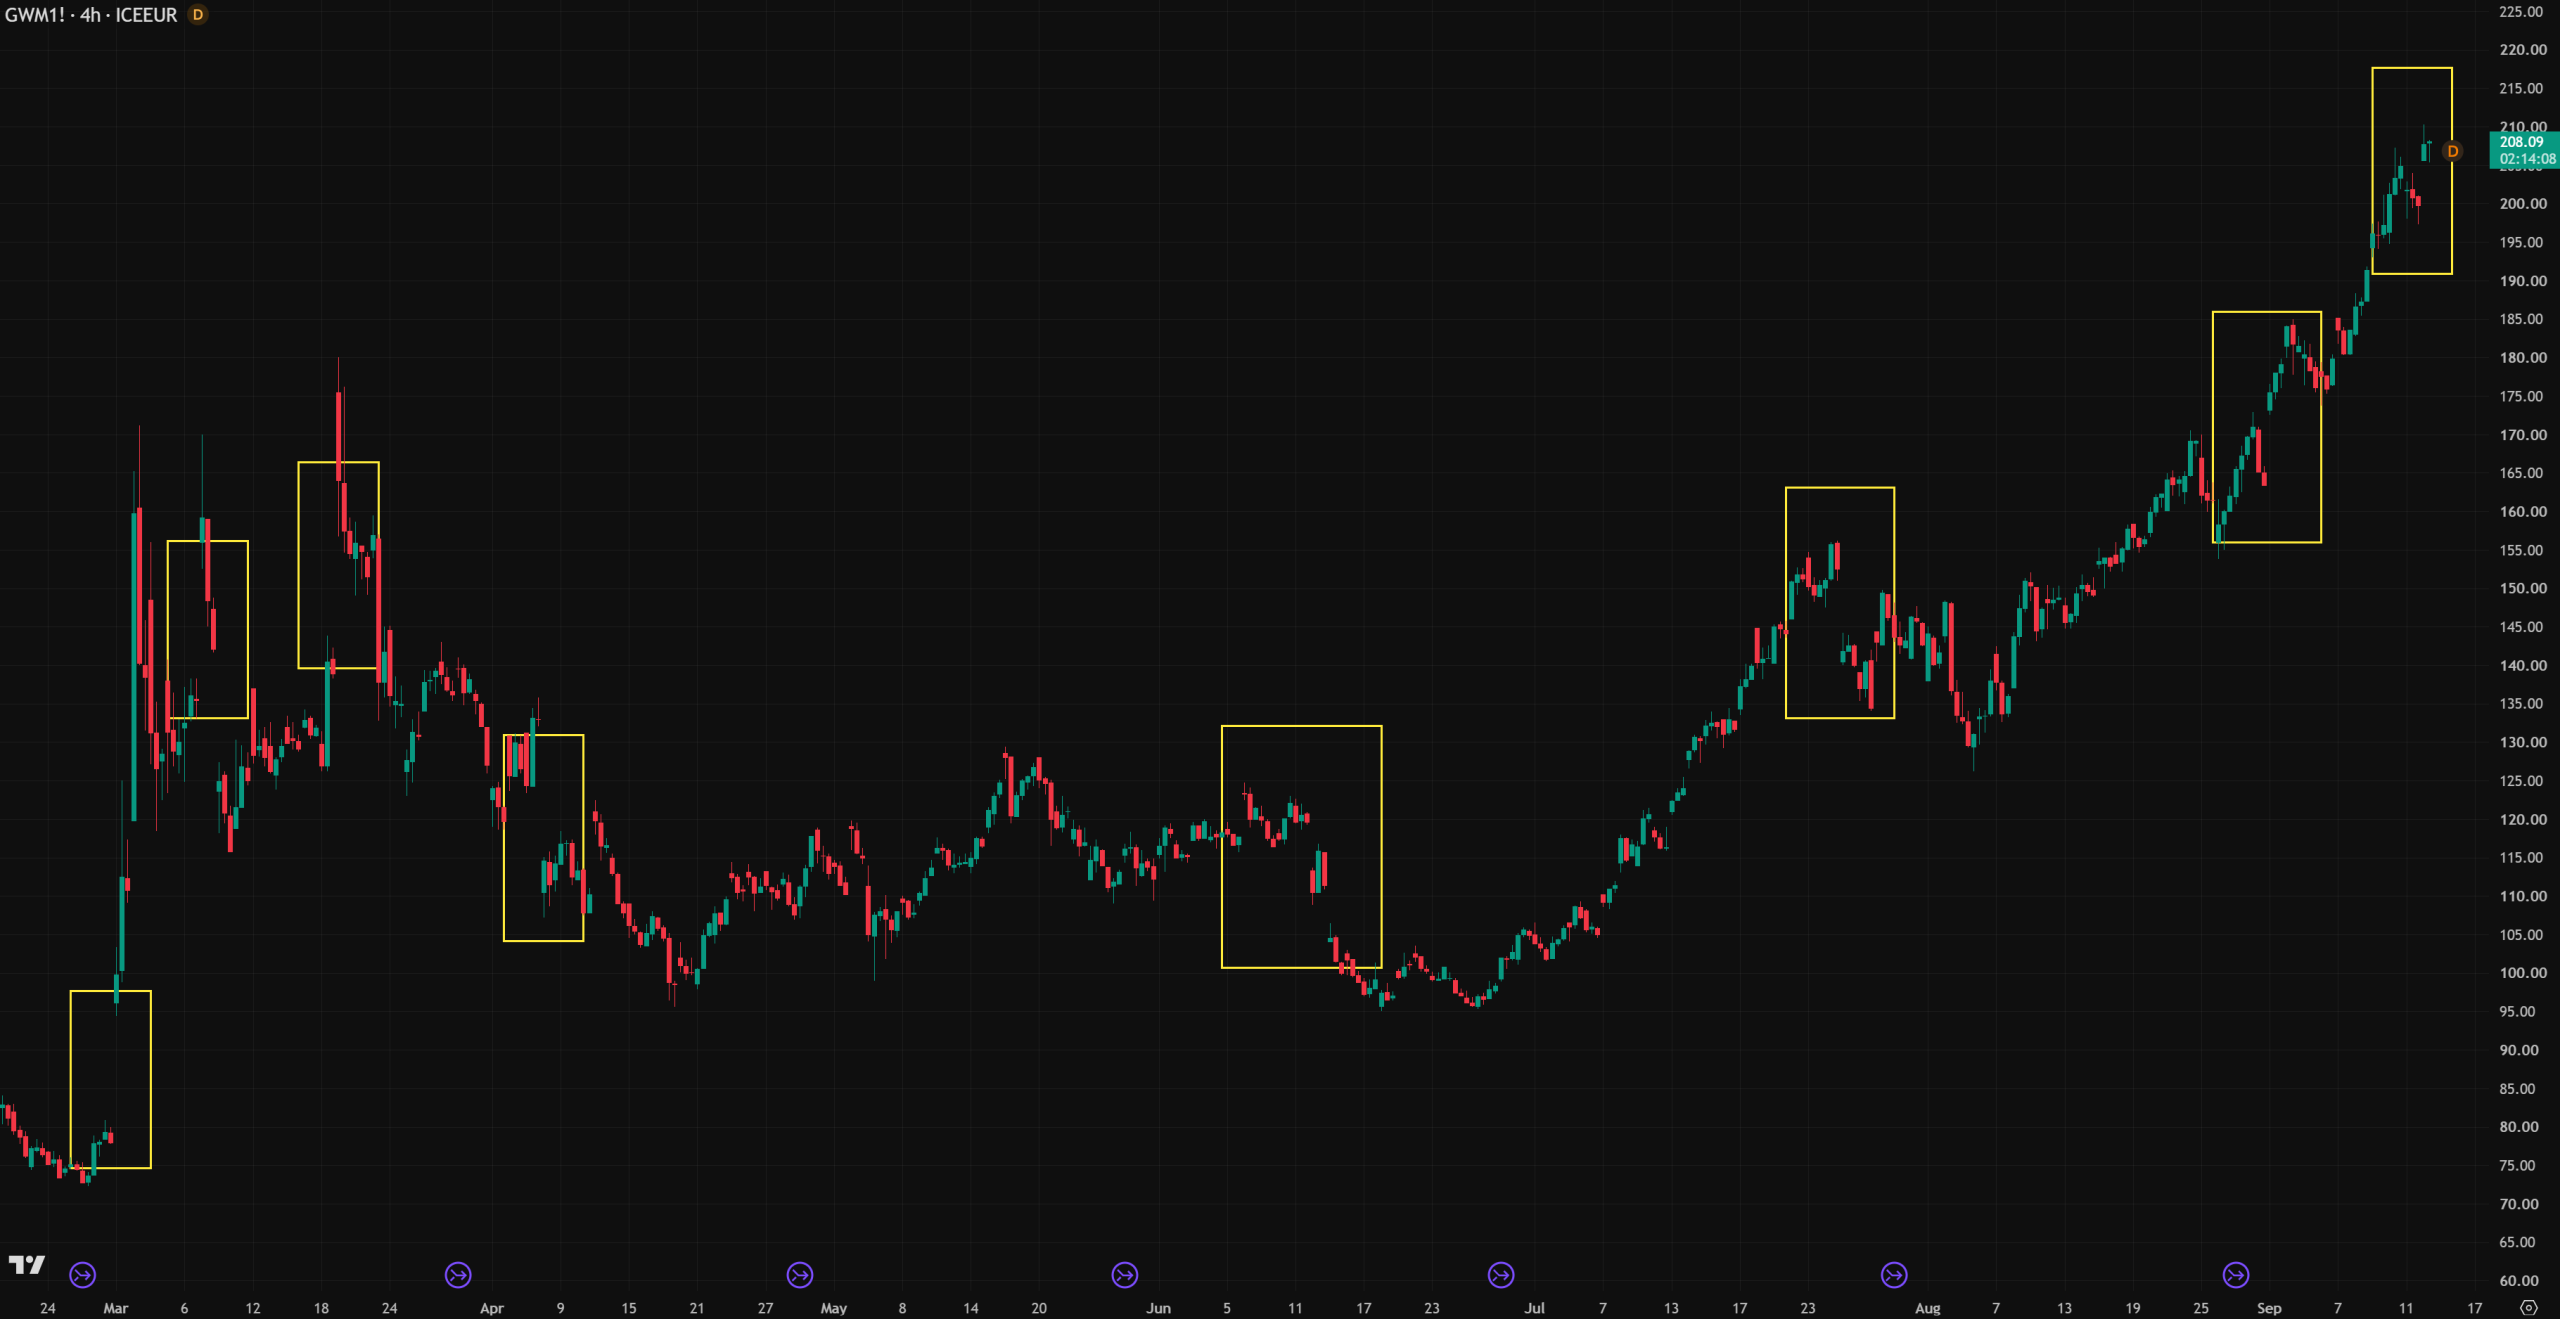
- Markets remain high and wide, following another weekend of developments across the Middle East.
- As has been the case since Trump’s war on Iran began back in late Feb, near-term delivery markets are “gapped” at open – please see chart below (Front-Month UK gas delivery).
- “Gapping” in financial markets occurs when an asset’s price makes a sharp jump up or down at the opening bell, leaving a blank, discontinuous space on a price chart.
- Invariably, gaps are caused by geopolitical events which happen when markets are closed for the day, or for the weekend.
- Trump’s war has been punctuated by weekend developments, resulting in broken price lines all over the place – practically speaking, traders struggle to enter/exit markets when gapping is prevalent as price triggers are leap-frogged, and entry/exit points are missed (regardless of whether trades are being placed manually and/or electronically).
- This weekend, the Houthis’ (bizarrely uncontested) march to secure pretty much the whole of the Red Sea coastline continued apace.
- Last week’s drone attack on Saudi Arabia’s East-West oil pipeline has been traced back to Maysan province in Iraq.
- Whilst the US was quick to blame Iran’s proxies in Iraq, Tehran has been equally as swift in refuting such claims.
- Saudi Arabia has confirmed that oil stocks will only sustain exports for five to seven days if the pipeline does not re-open – though how long repairs may last has yet to be confirmed.
- Today’s meeting between Iran and the Gulf States has been postponed, with Oman citing the need for “consensus” before the meeting can be reconvened.
- Not surprisingly, reports that Gulf neighbours are not even prepared to hold talks is pushing hopes of de-escalation further into the future, raising near-term risk premiums.
- For it’s part, Iran repeats it will only re-open the Strait if the US meets its demands.
- Trump counterclaims that Iran has been ‘calling constantly’ for talks, whilst reiterating that peace will only happen if the ‘right deal’ is reached.
- Qatari LNG exports remain all but suspended under force majeure, sustaining competition between European and Asian buyers for flexible LNG cargoes (keeping prices high).
- It looks likely that the US Fed will be forced to follow the ECB by raising interest rates tomorrow, which will put Trump and his choice for Fed Chair, Keith Warsh, on a collision course.
- Of course, Trump has made no secret of his preference that interest rates in the US should be the lowest in the world.
- Closely watched European gas storage fullness is now at 68% versus the 5-year average of 82%.
- Whilst industrials across Europe are still clamouring to close out big portions of Winter-26 delivery in anticipation of further escalation, market conditions remain spiky and volatile – as such, traders are scaling-in at intraday intervals (as and when the markets retraces or when speculators take profits).
- Monthly Day-Ahead Averages for September to date remain below Monthly Forwards – so, as was the case in Winter-22, it looks increasingly likely that Day-Ahead prices throughout Winter-26 will outperform the winter delivery forward prices we’ve seen over the last few weeks.
- To clarify, Monthly Day-Ahead Averages for September so far are at 189p/therm (or 6.5p/kwh exc. non-gas) – the highest level we’ve seen since Dec ’22 (at the height of the crisis, post Ukraine invasion etc.)
ELECTRICITY & CARBON
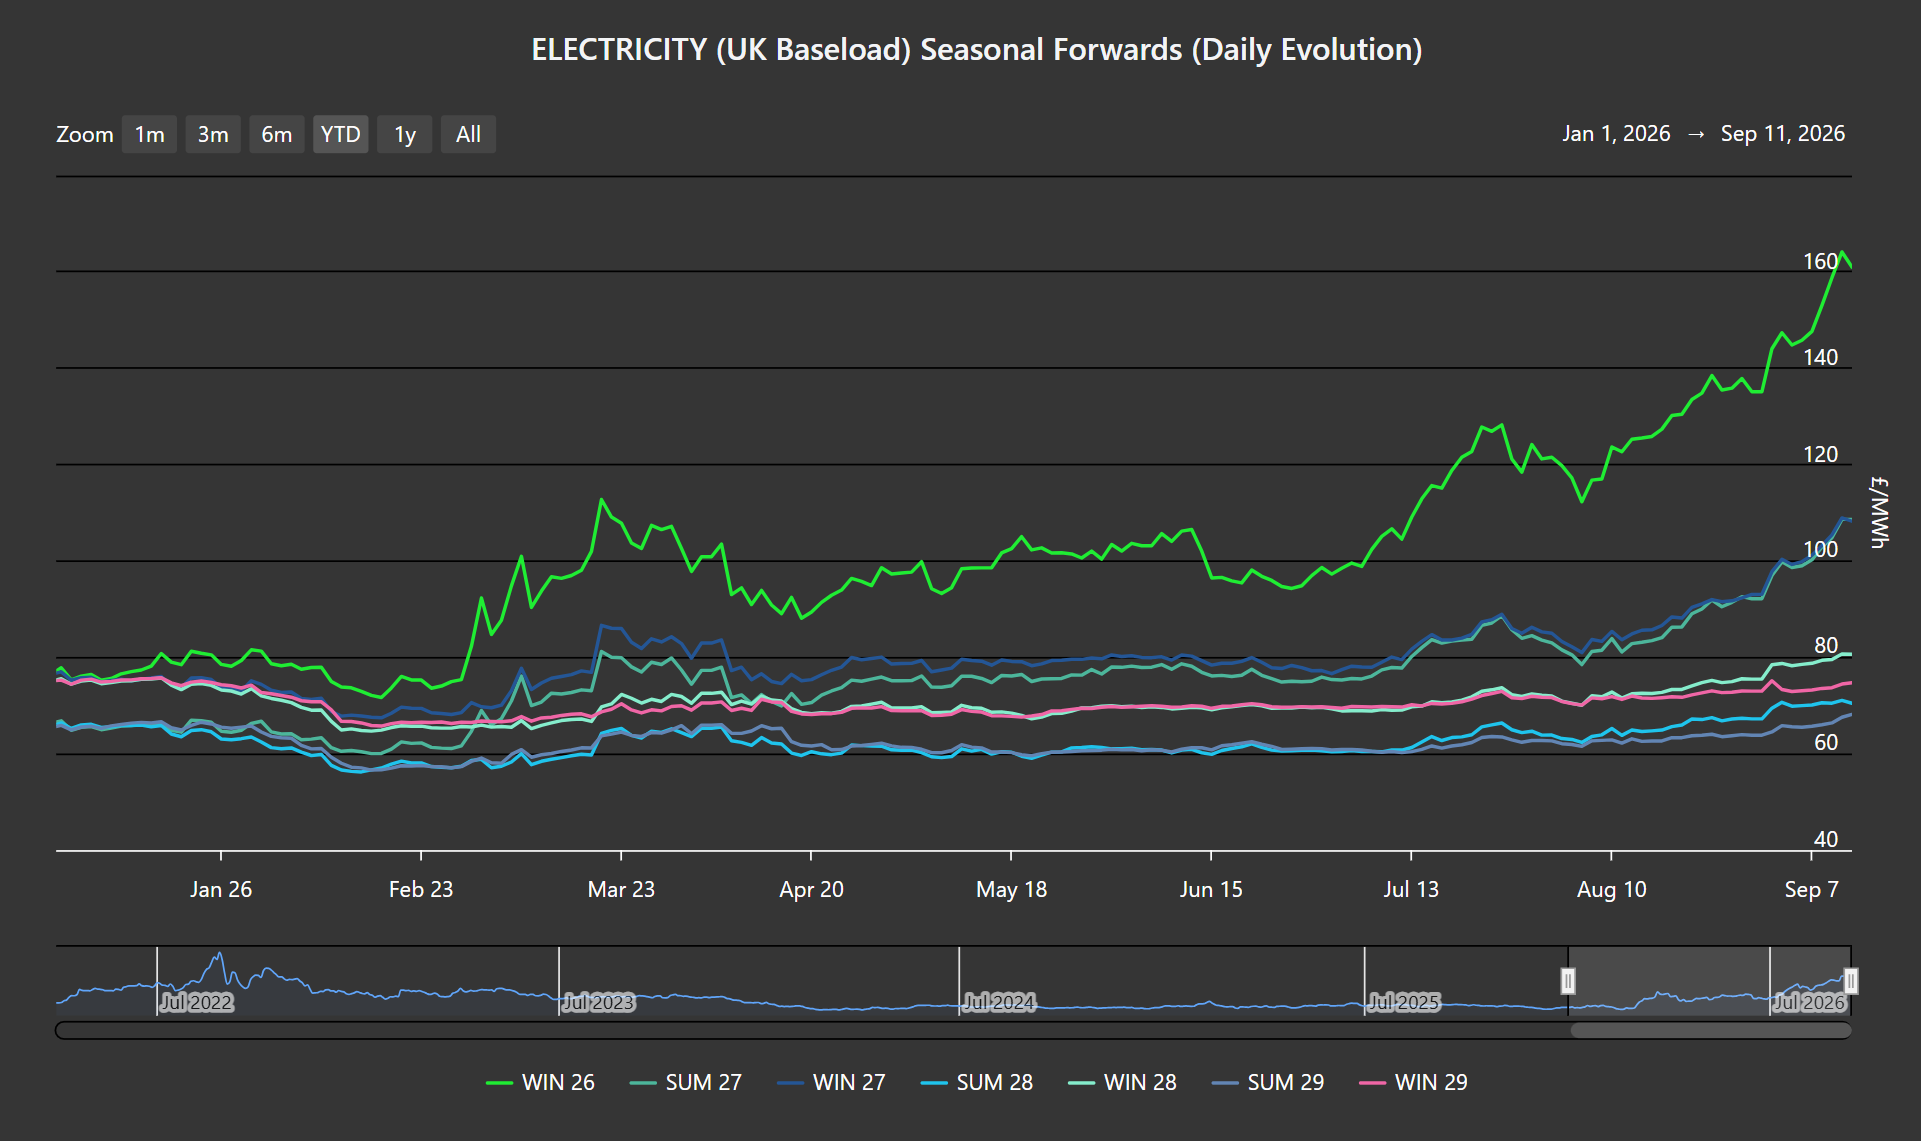
- Forward prices (available to secure now) are at almost a 60% discount versus Winter-26 delivery – this reflects the market’s underlying hopes that life will return to normal as and when Trump loses his grip on power.
- Electricity remains at a comparative discount to gas, this is down primarily to solid renewables outputs limiting gas for power burn over the summer months – though of course this will change when the days get shorter and the wind drops.
- On the Carbon side of things, mid-price Dec-26 UKA delivery sits at at £62.29/tn (and the spot is at early 61s) – prices have found support this last week off the back of runaway near-term gas prices.
- UK electricity Monthly Day-Ahead Averages for September so far are at £135/mwh (or 13.5p/kwh exc. non-energy).
- Whilst industrials across Europe are still clamouring to close out big portions of Winter-26 delivery in anticipation of further escalation, market conditions remain spiky and volatile – as such, traders are scaling-in at intraday intervals (as and when the markets retraces or when speculators take profits).
- Monthly Day-Ahead Averages for September to date remain below Monthly Forwards – so, as was the case in Winter-22, it looks increasingly likely that Day-Ahead prices throughout Winter-26 will outperform the winter delivery forward prices we’ve seen over the last few weeks.