



Wed, 9th Sep ’26
GAS
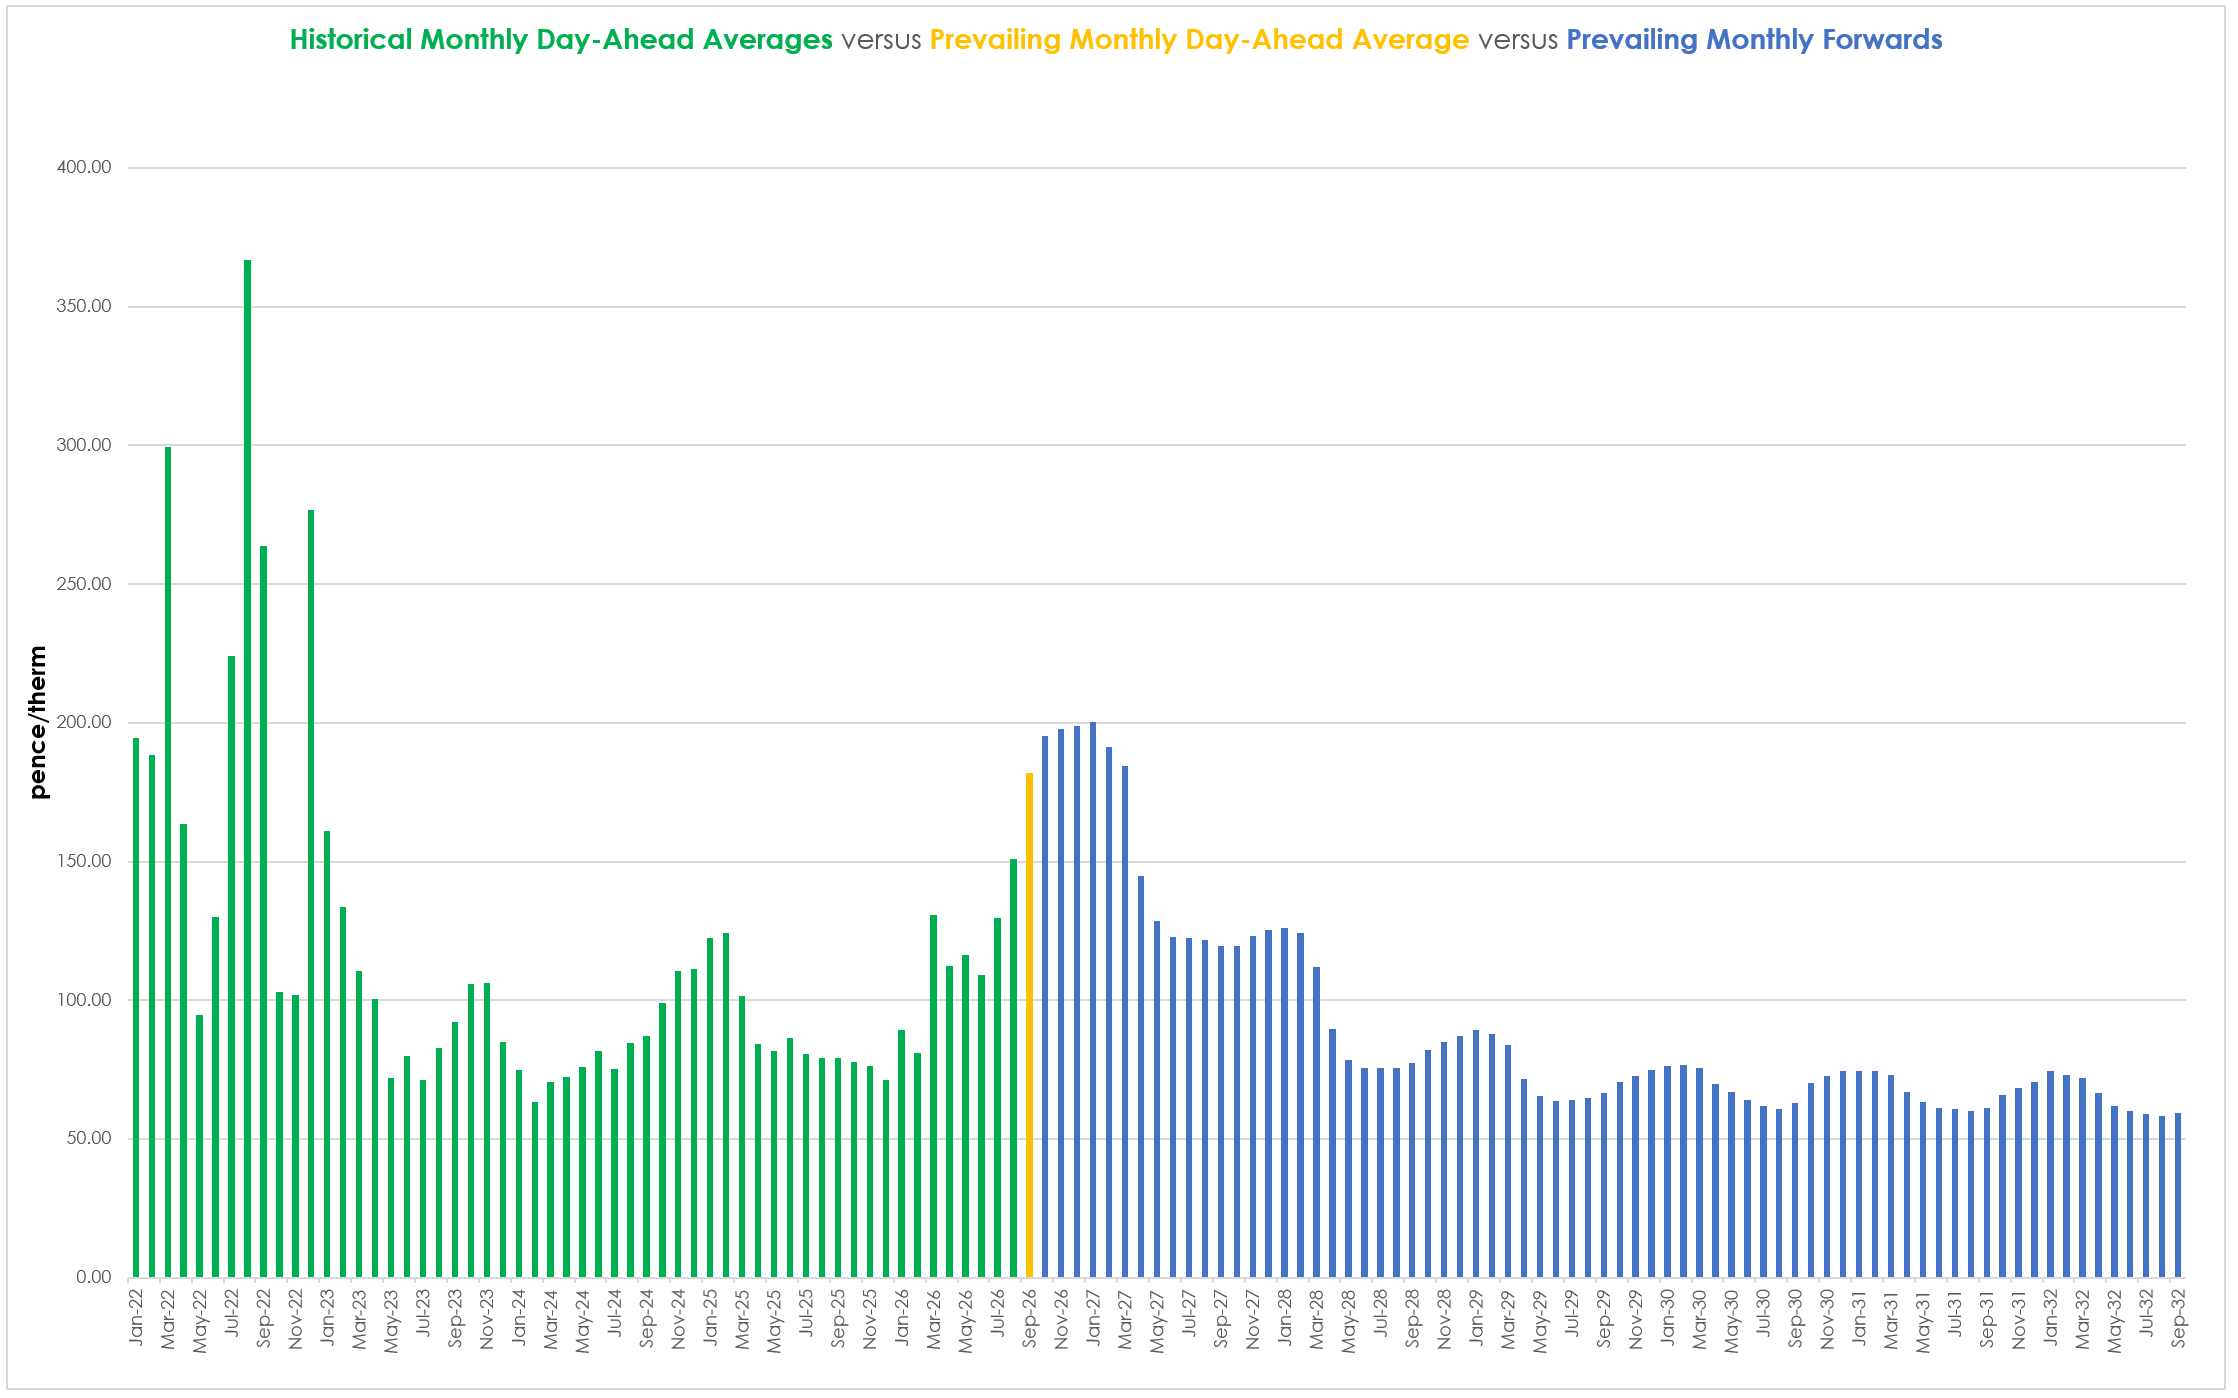
- This week has seen a significant escalation in hostilities across the Middle East.
- The US look powerless to bring an end to the wider impacts of Trump’s war on Iran.
- Geopolitical risk is all that’s driving price right now.
- Brent crude is holding above $100/bbl after the US destroyed five Iranian oil tankers near Kharg Island.
- Iran has retaliated against US targets in Jordan – for their part, the Houthis have then struck Saudi Arabia’s Jazan oil refinery.
- This morning, Iran has issued warnings to workers near Kuwaiti and Bahraini ports to abandon ship in preparation for an imminent attack.
- Qatar has all but halted LNG deliveries and inevitably extended force majeure on cargoes to Europe through the coming autumn – essentially putting the last nail in the coffin where European storage injection is conerned.
- Storage fullness is now at 67% – well off the pace (the 5-year average being 81%).
- Industrials across Europe are closing out big portions of Winter-26 delivery in anticipation of further escalation, with only 21 days remaining until winter officially kicks-in.
- Whilst Monthly Day-Ahead Averages for September so far remain below Monthly Forwards, the front of the curve has now stretched to as much as 312% higher than the bottom of the curve – please see chart below.
- For the first time since Trump’s war began, the upside risk now heavily outweighs any potential downside benefit.
ELECTRICITY & CARBON
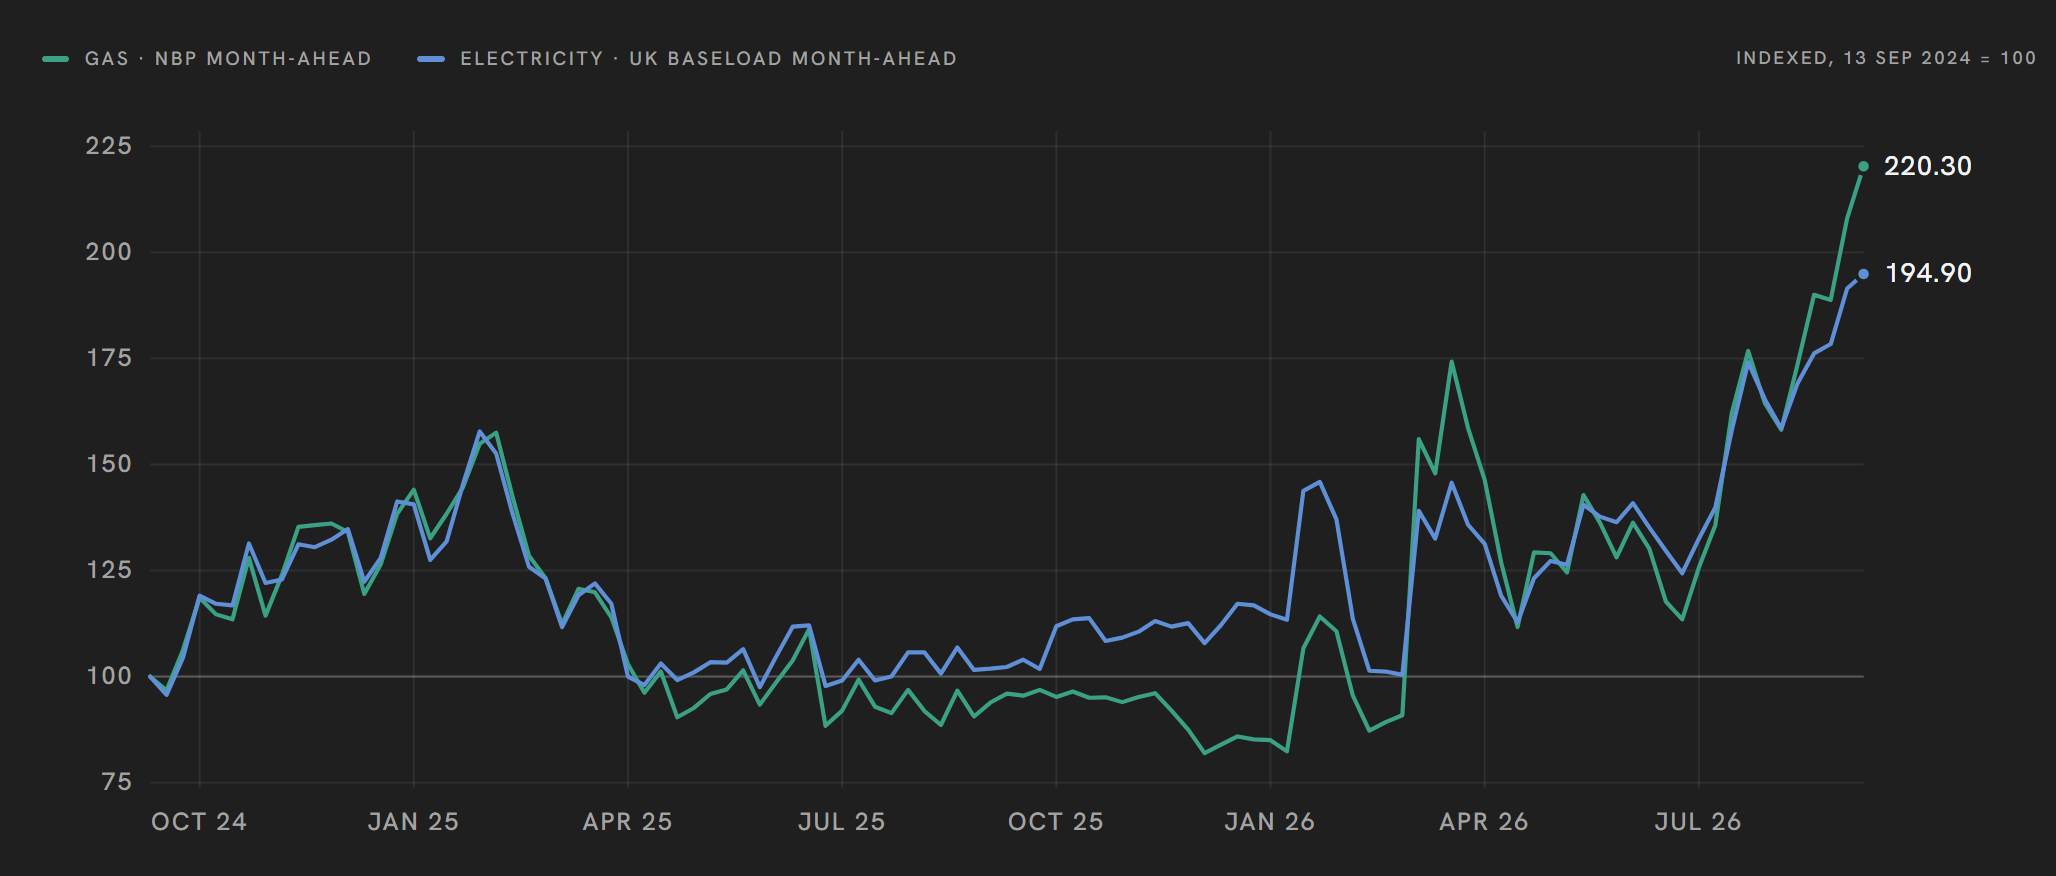
- The chart below is taken from our website (https://pep-icd.com/charts/) and details the correlation coefficient between gas and electricity prices.
- The data shows weekly closing prices indexed to 100 at 13th Sep ’24 and illustrates comparative value.
- As you can see, gas is very much at a premium right now, with electricity spiking less in response to the impacts of the closure of the Strait of Hormuz.
- This is down primarily to solid renewables outputs limiting gas for power burn – though of course this will change when the days get shorter and the wind drops.
- On the Carbon side of things, mid-price Dec-26 UKA delivery sits at at £61.40/tn (and the spot is at early 60s) – prices are a little firmer today off the back of runaway gas contracts.
- UK electricity Monthly Day-Ahead Averages for August so far are also at £123/mwh (or 12.3p/kwh exc. non-energy).
- Monthly Day-Ahead Averages are at £119/mwh (or 11.9p/kwh ec non-energy) – so well below Monthly Forwards across the winter period.