



Fri, 18th Sep ’26
GAS
- Markets are taking a breather to end the week.
- Whilst we’ll need to see significantly improved European LNG imports (alongside a higher rate of storage injections) before prices cna drop-off further, it’s nonetheless true to say that markets hit a ceiling on Monday and have then spent the rest of the week unwinding.
- On the face of it, this unwinding looks like a correction/retracement most likely due to profit-taking and/or speculative repositioning – but it’s also starting to feel like prices have now baked-in both the supply shock and the geopolitical risk linked to the closure of the Strait of Hormuz.
- Notably, a second “theatre” of battle has taken centre-stage this week between the Houthis and Saudi Arabia along the Red Sea coast – which, up to now, has not resulted in the closure of the Bal el-Mandeb Strait.
- And so, whilst the energy crisis persists, the heat has gone out of the bull run – today, prices are consolidating in a tight range pending further developments (be they bullish or bearish).
- But as we are all coming to learn, Trump likes to use the weekends to move markets – so it’s anyone’s guess if the prevailing calm/balance will still be with us come Monday morning!
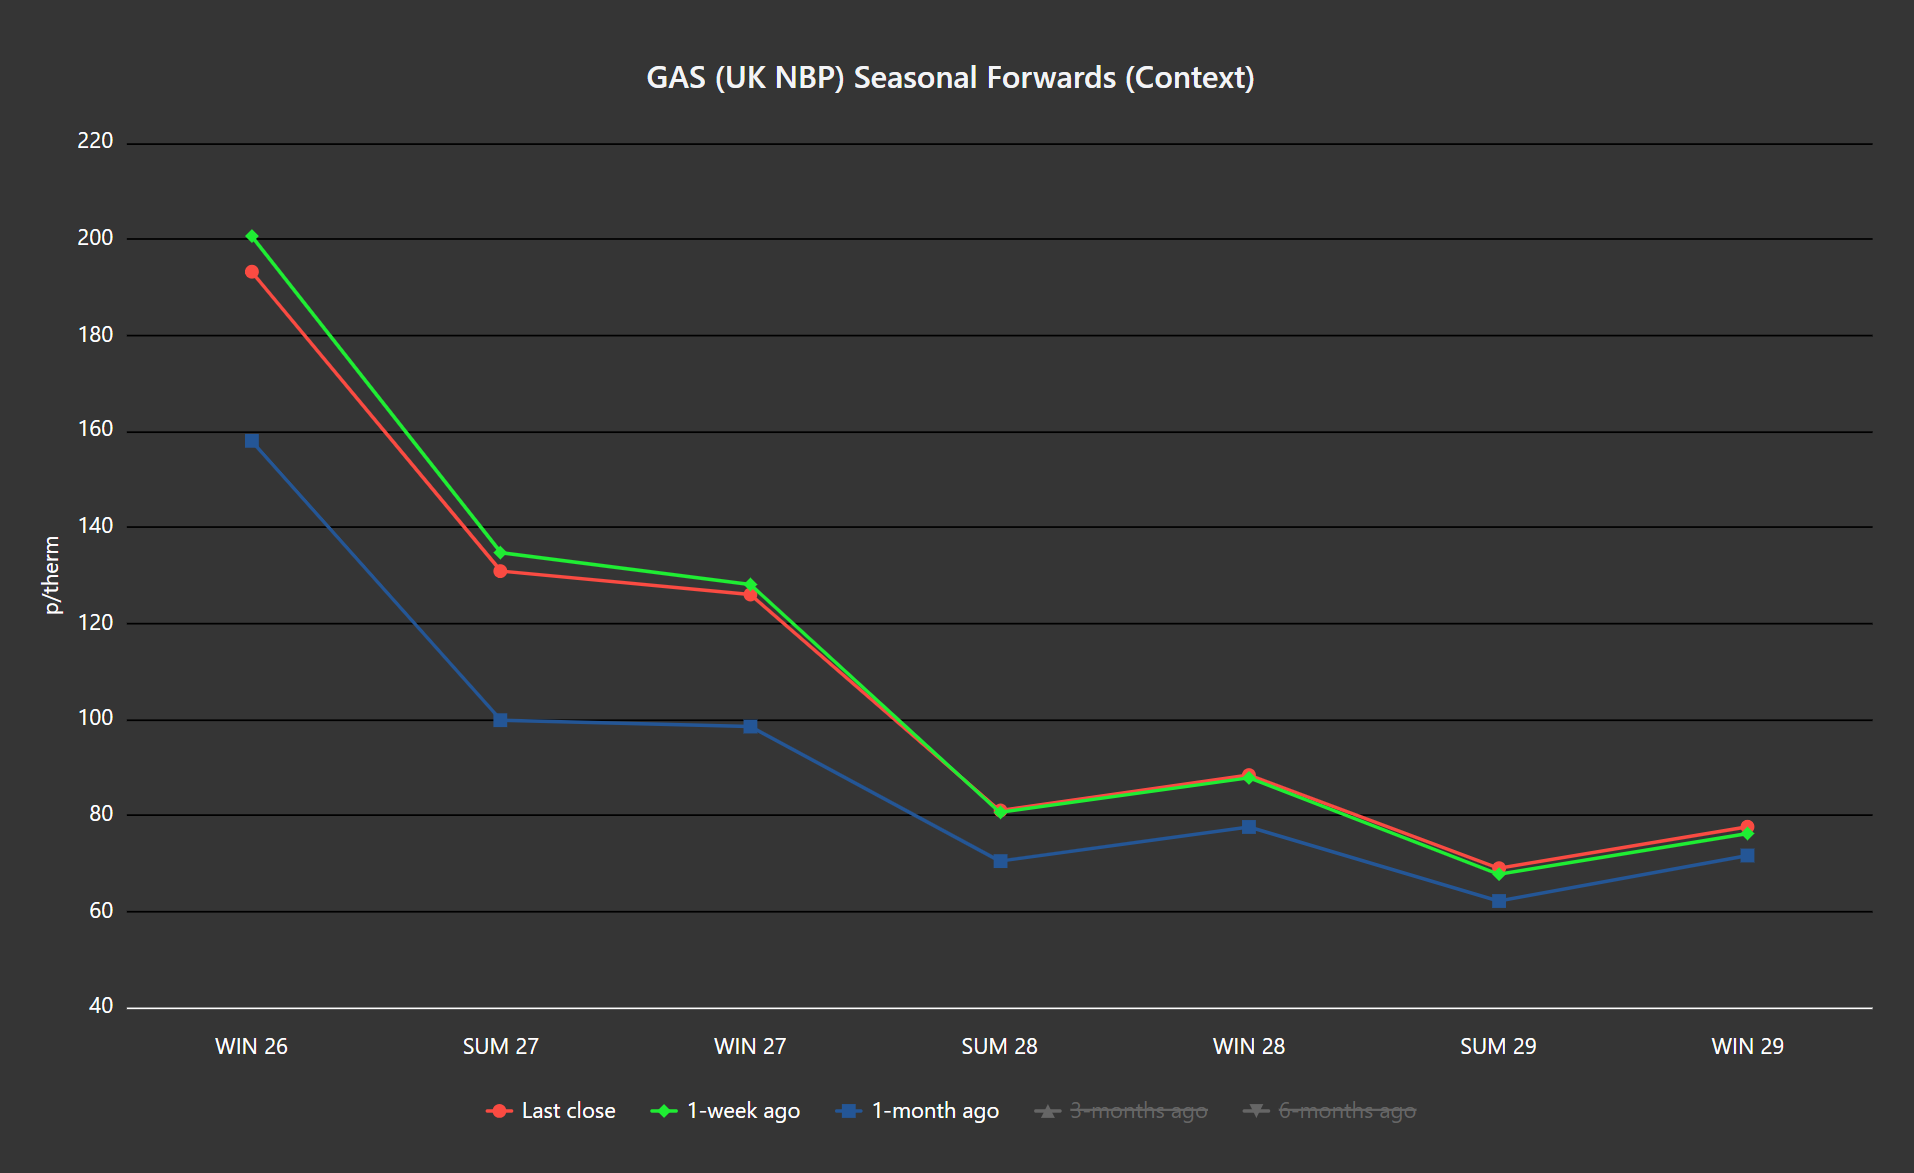
- As you can see from the chart below, Seasonal Forwards are actually down on the week – but still significantly up on the month.
- With the mid-terms nearly upon us, the Trump Administration looks increasingly isolated – his appointed Fed Chair (Kevin Warsh) went against Trump’s wishes this week by presiding over a decision to raise interest rates whilst also hinting at further tightening over the coming months so as to take the heat out of inflationary pressures (caused, a little ironically, by Trump’s war).
- Trump has complained of course – suggesting instead that the US should be at 1% interest rate.
- Economists have been keen to point out such a rate is only used when one is trying to stimulate the economy, not slow it down!
- Closely watched European gas storage fullness is now at 68% versus the 8-year average of 84%.
- Industrials across Europe are still scaling-in big portions of Winter-26 delivery in anticipation of further escalation.
- Monthly Day-Ahead Averages for September to date remain below Monthly Forwards – so, as was the case in Winter-22, it looks increasingly likely that Day-Ahead prices throughout Winter-26 may outperform the winter delivery forward prices we’ve seen over the last few weeks.
- To clarify, Monthly Day-Ahead Averages for September so far are at 191p/therm (or 6.5p/kwh exc. non-gas) – the highest level we’ve seen since Dec ’22 (at the height of the crisis, post Ukraine invasion etc.)
ELECTRICITY & CARBON
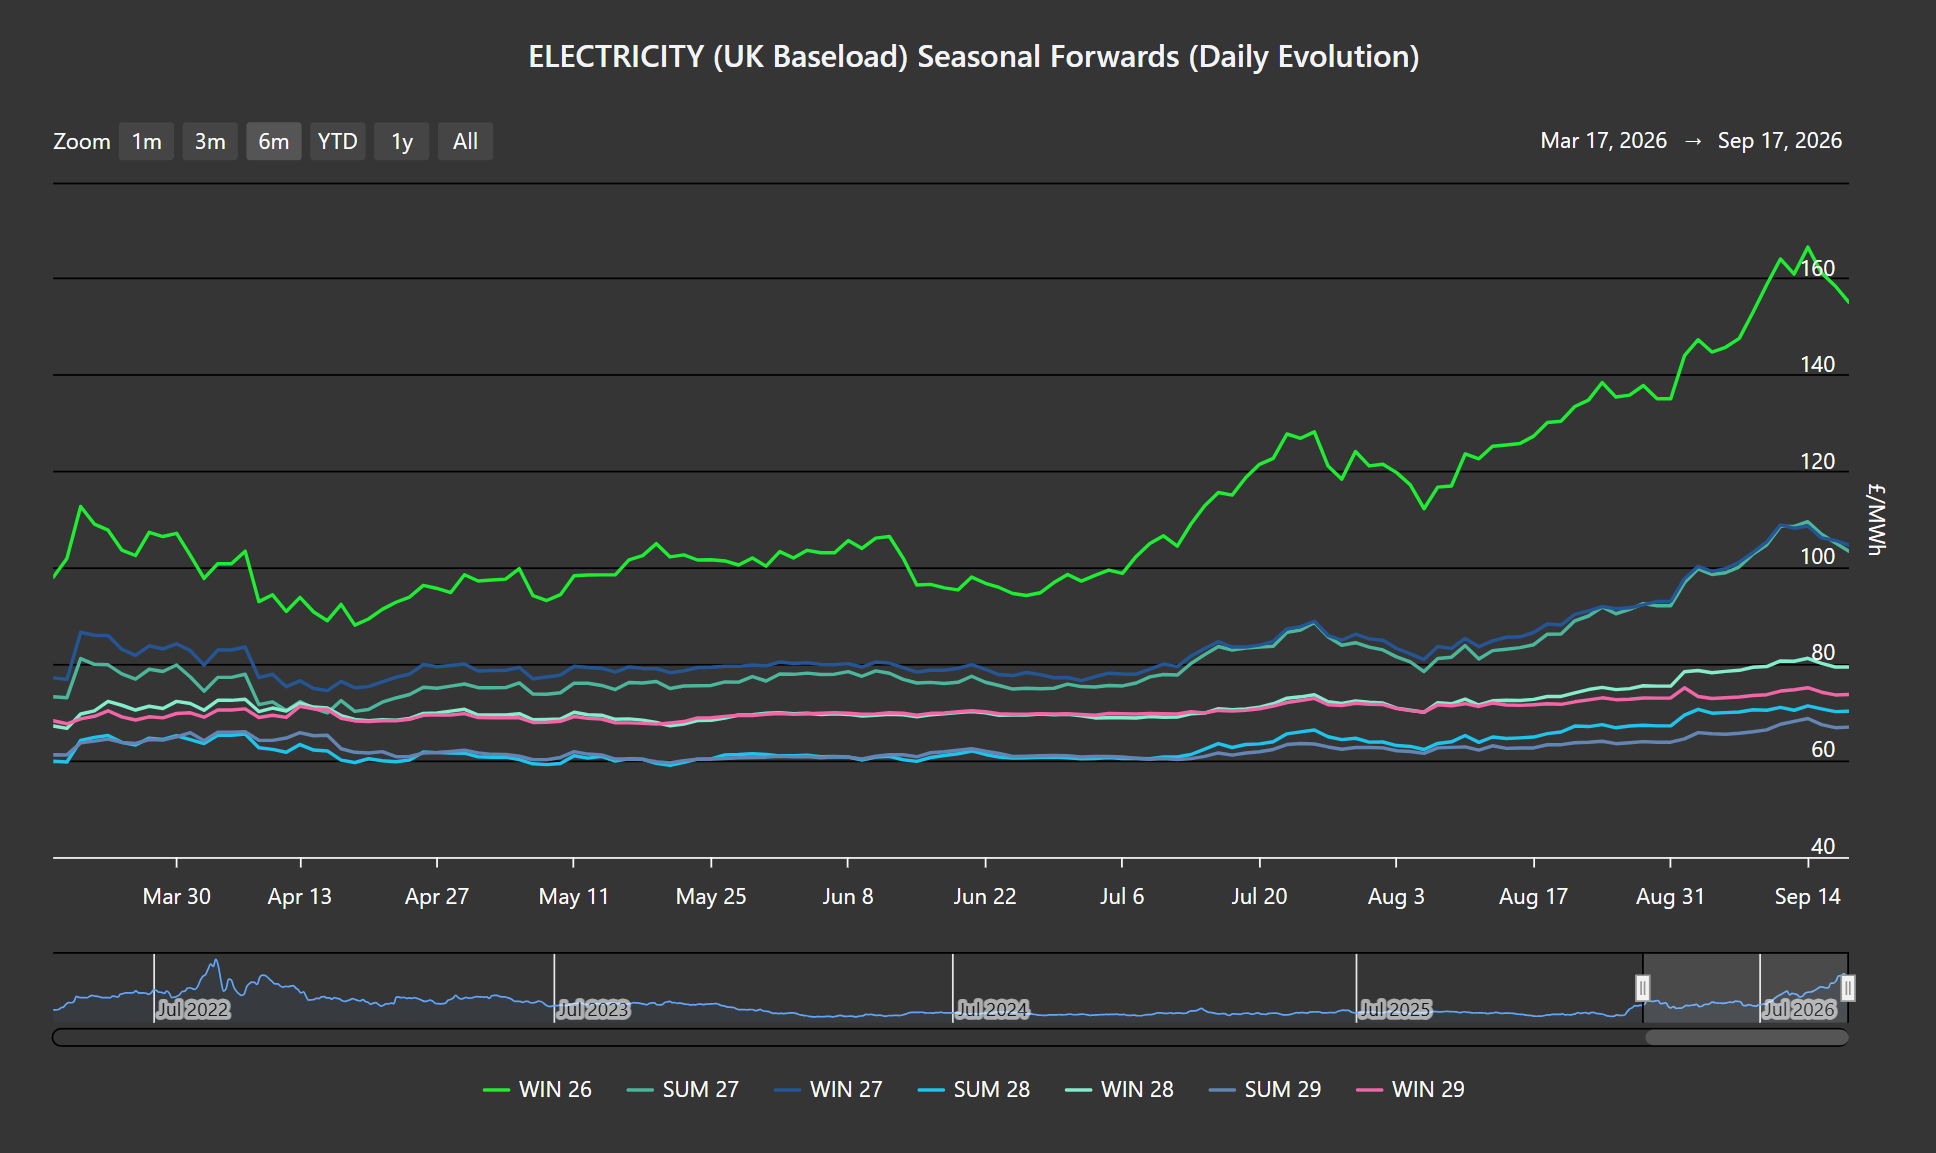
- Far-curve Forward prices (available to secure now) are at almost a 60% discount versus Winter-26 delivery – this reflects the market’s underlying hopes that life will return to normal as and when Trump loses his grip on power.
- Electricity remains at a comparative discount to gas, this is down to solid renewables outputs limiting gas for power burn over the summer months – though of course this will change when the days get shorter and the wind drops.
- On the Carbon side of things, mid-price Dec-26 UKA delivery sits at at £59.30/tn (and the spot is at early 58s) – prices have fallen this week in line with softening gas prices (and the likelihood of industrial demand destruction if prevailing prices persist across the winter).
- UK electricity Monthly Day-Ahead Averages for September so far are at £135/mwh (or 13.5p/kwh exc. non-energy).
- Industrials across Europe are still scaling-in big portions of Winter-26 delivery in anticipation of further escalation.
- Monthly Day-Ahead Averages for September to date remain below Monthly Forwards – so, as was the case in Winter-22, it looks increasingly likely that Day-Ahead prices throughout Winter-26 may outperform the winter delivery forward prices we’ve seen over the last few weeks.
- As per the chart below, Winter-26 prices have rolled over marginally this week.