



Fri, 12th Jul ’24
GAS
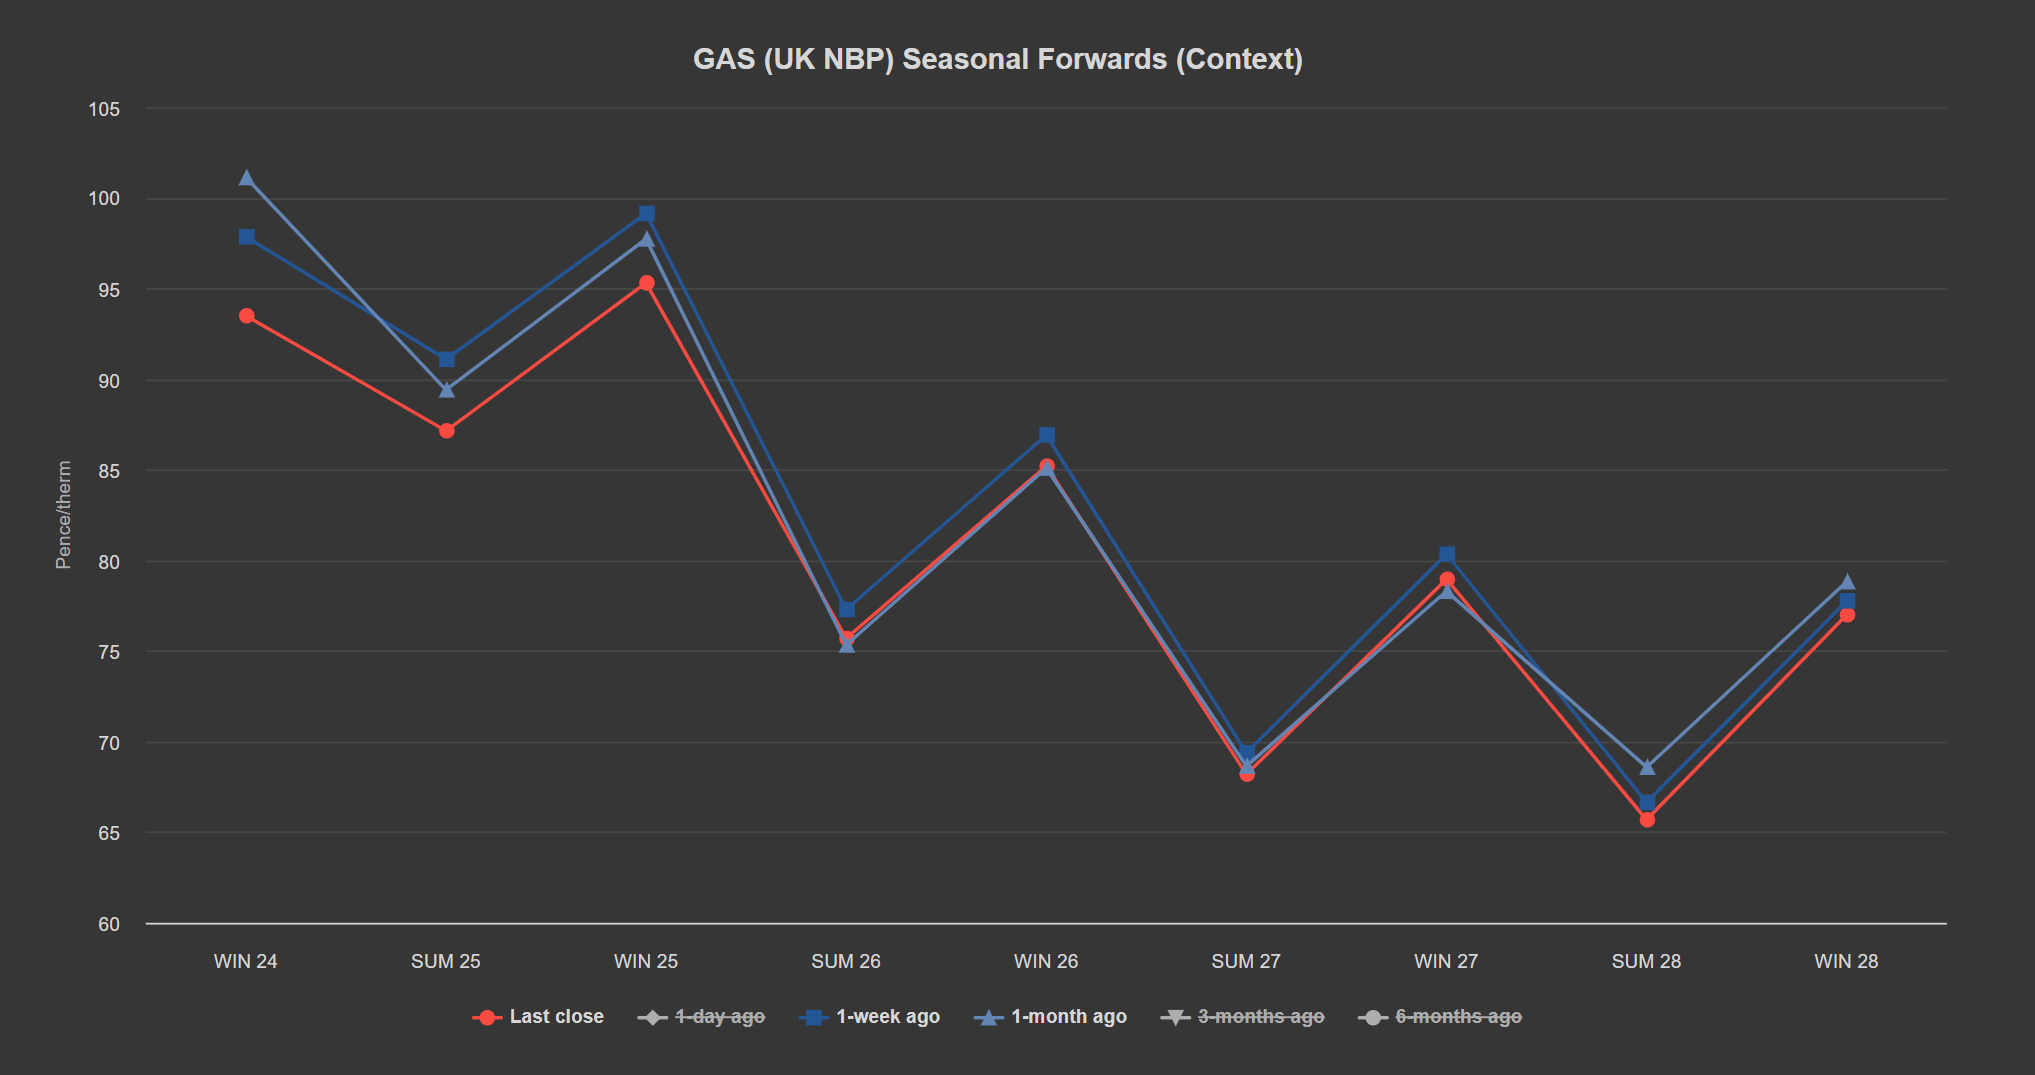
- Prices are ending the week down on both the week and the month – see chart.
- Though, yesterday, prices tracked European benchmarks and printed a marginal increase to halt a 4-day bearish run.
- Bullish support is centred around fears of LNG supply tightness, with Freeport LNG terminal still not operational following a hurricane induced outage.
- At the time of writing, both near- and far-term prices are trading sideways with a marginal bearish bias.
- The UK system opened long this morning (supply outstripping demand forecast).
- Fundamentals remain unchanged, meaning a combination of storage injections and strong exports to the continent look set to continue to sustain a comfortable market balance.
- Wind outputs are forecast to drop off this weekend (increasing the need for gas-for-power burn) which is limiting any further meaningful downside price action in the short term.
- All in all, solid injections and high European storage (80% versus the 5-year average of 67%) coupled with steady Norwegian flows continues to apply bearish pressure to a market exhibiting mild summery symptoms.
- With demand low, and supply comfortable, replenishing gas stocks is not posing any problems.
- On the hedging side, we’re now on the other side of Summer-24 – with 103 days having elapsed, and 81 remaining.
- Clients with open volumes for Winter-24 are increasingly scaling-in so as to avoid any loss of prevailing value.
- Prices are increasingly soft and threatening to roll-over, with temperatures expected to be back above seasonal norms come 16th July (amid improving wind outputs as the month progresses).
- Europe remains on track to achieve 100% storage levels by Winter-24 (early Oct ’24) – though LNG delivery remains tight against a backdrop of sustained high temperatures across Asia (and the associated cooling demand).
- Monthly Day-Ahead averages so far this month are on target to achieve 76p/therm (or circa. 2.55p/kwh excluding non-gas).
ELECTRICITY & CARBON
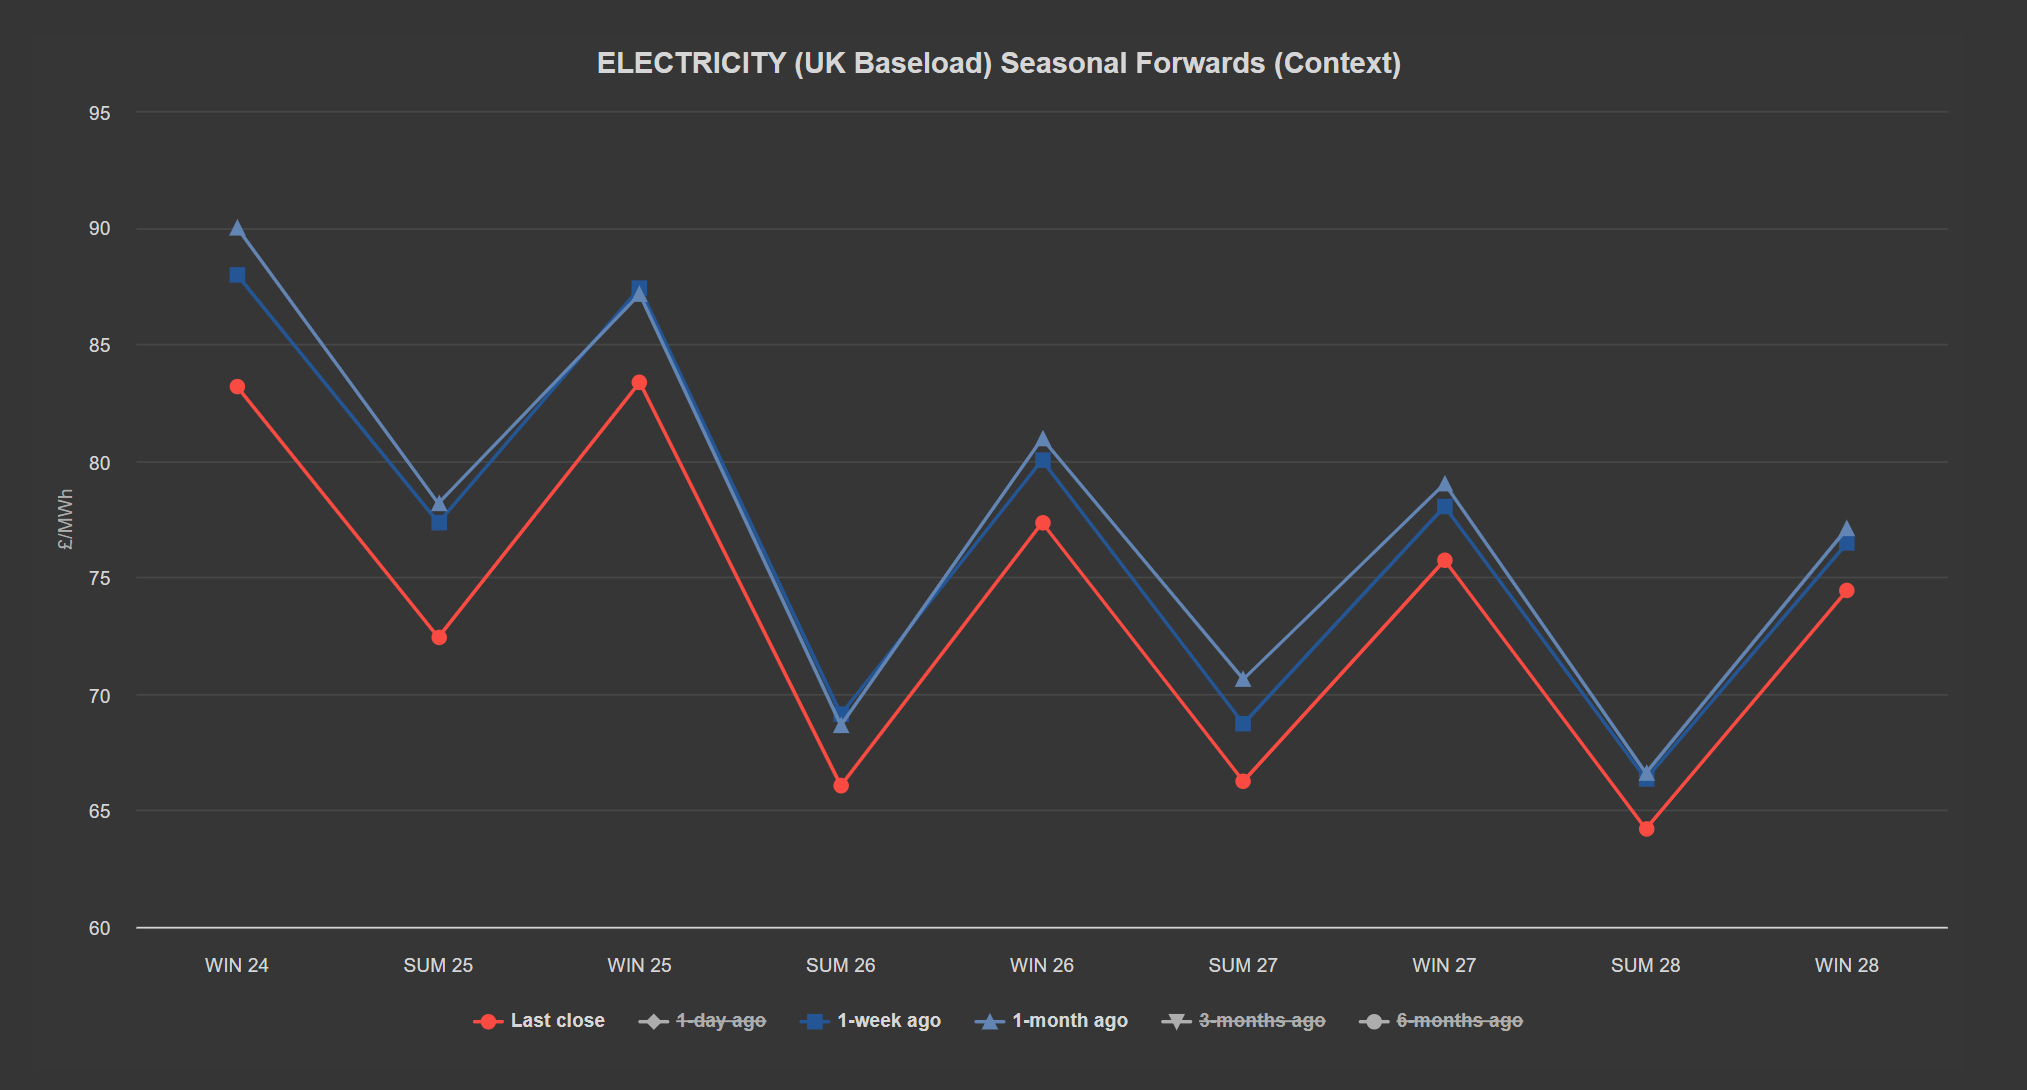
- Looking to the continent, near-term delivery prices are circa. 10% lower on the day.
- Things look warm come the weekend across Western Europe – wind will be patchy and driven by frontal weather conditions.
- On the Carbon side, markets remain in a bear trend (tracking gas) – though summer remains unsupportive for emissions prices.
- Back in the UK, UKAs (UK Carbon Allowances) followed our prediction that prices were due to fall (as indicated by RSI divergence) – now trading at circa. £41/tonne.
- Prices are now in a confirmed ascending trend channel testing the lower extremity – with £40/tn as a strong area of support to the downside – so a retest of this level is likely if EUAs can maintain bearish momentum.
- Our electricity generation mix is bearish in nature today with renewables contributing 36%, thermal at 22% (gas and coal) and low carbon at 29% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are looking summer-esque, and are on target to achieve £62/mwh (or circa. 6.2p/kwh excluding non-energy).