



Tues, 16th Jul ’24
GAS
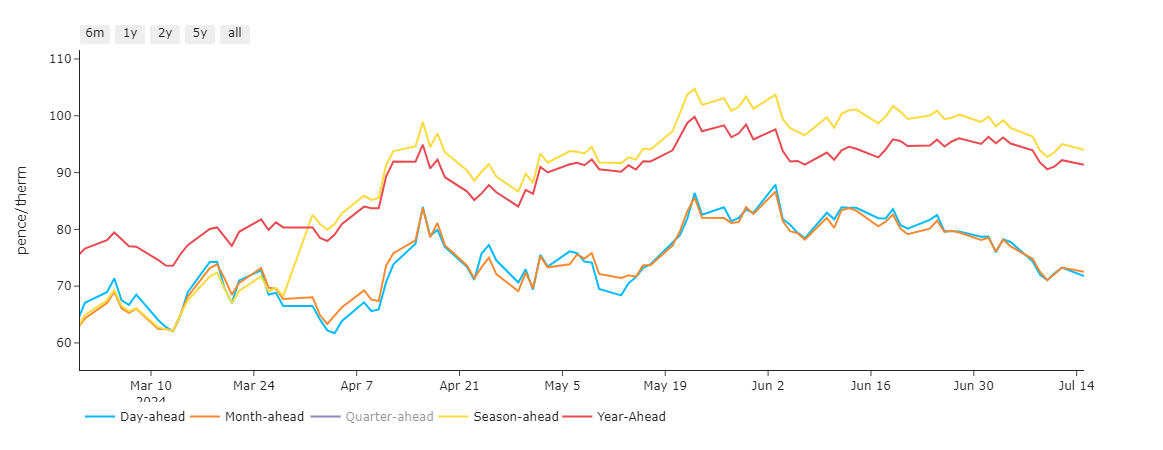
- As Summer-24 deepens, beginning mid-June, Day/Month-Ahead prices have fallen away from Season/Year-Ahead – reflecting a “summery” discount to near-term delivery (see chart).
- Nonetheless, prices opened slightly up on yesterdays close off the back of flip-flopping, mixed weather forecasts for the coming fortnight – with temperatures now expected to climb above the seasonal norms this weekend but then falling back below seasonal norms thereafter.
- Of course, lower temperatures will likely increase gas-for-power burn to accommodate heating demand.
- However, wind outputs whilst expected to remain below seasonal norms this week will likely climb above seasonal norms into next week – mitigating the impact of temperature falls (and the associated reliance on thermal generation).
- The UK opened long this morning (supply outstripping demand forecast).
- Prevailing demand remains below seasonal norms.
- Prices down the curve are a little higher this morning, with cooling demand rising in response to the heatwave being enjoyed/endured across large swathes of Europe – will the UK be next?
- Well, the South of England is forecast to hit high temperatures in the next couple of days.
- Freeport terminal (Texas) continues to export reduced volumes of LNG, as repairs on the facility continue apace following damage caused by Hurricane Beryl.
- All in all, solid injections and high European storage (81% versus the 5-year average of 70%) coupled with steady Norwegian flows continues to apply bearish pressure to a market exhibiting mild summery qualities.
- With demand low, and supply comfortable, replenishing gas stocks is not posing any problems.
- On the hedging side, we’re now on the other side of Summer-24 – with 107 days having elapsed, and 77 remaining.
- Clients with open volumes for Winter-24 are increasingly scaling-in so as to avoid any loss of prevailing value.
- Europe remains on track to achieve 100% storage levels by Winter-24 (early Oct ’24) – though LNG delivery remains tight against a backdrop of sustained high temperatures across Asia (and the associated cooling demand).
- Monthly Day-Ahead averages so far this month are on target to achieve 75p/therm (or circa. 2.55p/kwh excluding non-gas).
ELECTRICITY & CARBON
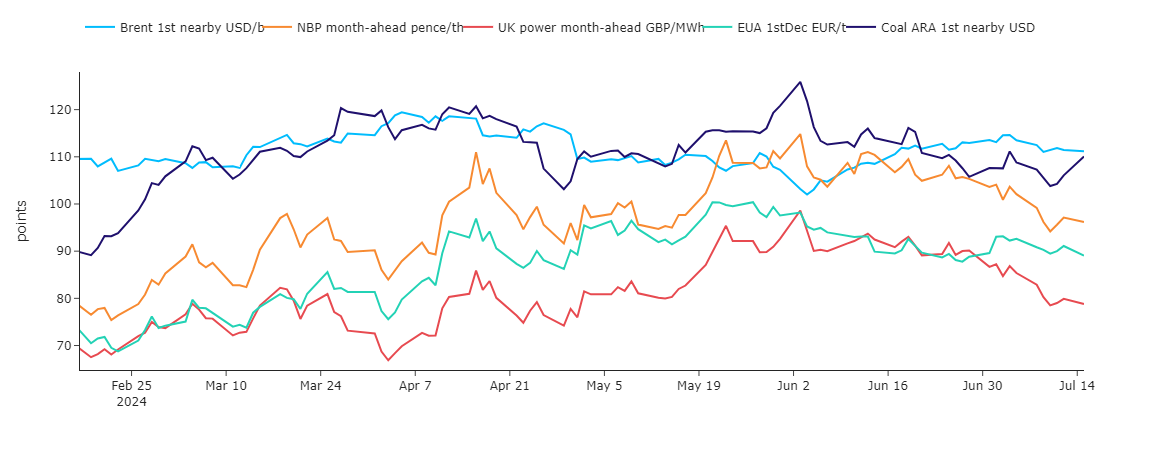
- Electricity (and gas) are enjoying comparative summer decreases relative to a basket of other UK commodities (see chart).
- Looking to the continent, near-term delivery prices are likely to be pressured by high solar and wind outputs – especially during daytime hours.
- Though generators are slowly adapting their bidding behavior to be more price sensitive – by limiting the negative impacts of oversupplying the grid.
- The weather outlook indicates an unstable pattern driven by Atlantic ridges and low pressure systems, leading to fluctuating temperatures and wind conditions across Europe, with a brief warming trend expected over the weekend.
- Renewable energy generation is likely to be affected by these weather patterns, with wind forecasts showing short-term increases followed by calmer conditions, while solar generation remains unstable and hydro potential is expected to decrease due to limited precipitation in the Alps.
- A significant heatwave is being felt across Europe, ranging from the Balkans to the Black Sea.
- Demand is therefore sharply up, stimulated by cooling requirement – the consequence is very high prices for the evening ramp (when solar is not producing but the need to cool down the scorching heat is still present).
- On the Carbon markets, EUAs (European Carbon Allowances) declined yesterday in line with gas markets – the Dec ’24 benchmark contract closed at €67.64/t after losing -2.24% on the day.
- Back in the UK, UKAs (UK Carbon Allowances) followed our prediction that prices were due to fall (as indicated by RSI divergence) – now trading at circa. £41/tonne.
- Prices are now in a confirmed ascending trend channel testing the lower extremity – with £40/tn as a strong area of support to the downside, £45/tn as strong area of resistance to the upside.
- Our electricity generation mix is neutral in nature today with renewables contributing 29%, thermal at 31% (gas and coal) and low carbon at 28% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £66/mwh (or circa. 6.6p/kwh excluding non-energy).