



Tues, 9th Jul ’24
GAS
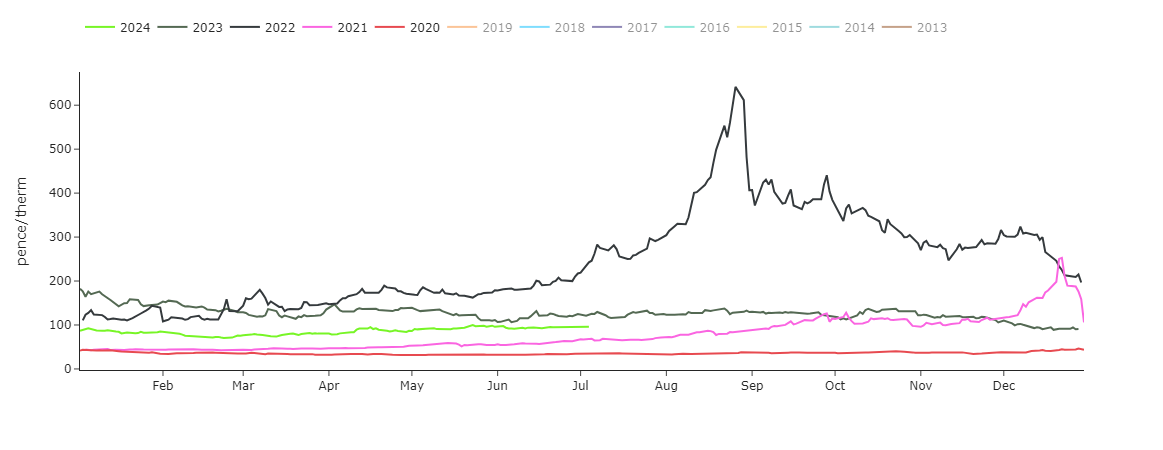
- Year-Ahead prices continue to print at levels above ’20/’21, but comfortably below ’22/’23 (and notably below the psychological resistance level of 100p/therm) – see chart.
- Storm Beryl came and went leaving very little damage to LNG infrastructure in her wake.
- Fundamental key drivers remain soft and could result in further weakness over the coming days.
- The UK supply/demand dynamic is loose (supply outstripping demand forecast).
- UKCS (continental Shelf) domestic production has risen following resolution of the Tolmount maintenance.
- Injections into MRS (mid-range storage) and Rough storage continue and exports to the continent remain elevated (reflecting a surfeit of gas supply).
- Prices opened lower again this morning – off the back of a long UK system and deepening summer conditions.
- Both Norwegian flows and LNG send out remain steady, with European storage now at 79% versus the 5-year average of 69%.
- Looking at global LNG degasification w-o-w, we’ve seen a 9% fall of the number of vessels waiting to degasify for 20 days or more, coupled with a fall of 0.4 million tonnes of delivery on water – reflecting an increase in global demand most likely due to uncertainties over the impacts of Storm Beryl on US exports.
- On the hedging side, we’re now on the other side of Summer-24 – with 100 days having elapsed, and 84 remaining.
- Clients with open volumes for Winter-24 are increasingly scaling-in so as to avoid any loss of prevailing value.
- Nonetheless, prices are soft and threatening to roll-over, with temperatures expected to be back above seasonal norms come 16th July (amid improving wind outputs as the month progresses).
- Europe remains on track to achieve 100% storage levels by Winter-24 (early Oct ’24) – though LNG delivery remains tight against a backdrop of sustained high temperatures across Asia (and the associated cooling demand).
- Monthly Day-Ahead averages so far this month are on target to achieve 77p/therm (or circa. 2.6p/kwh excluding non-gas).
ELECTRICITY & CARBON
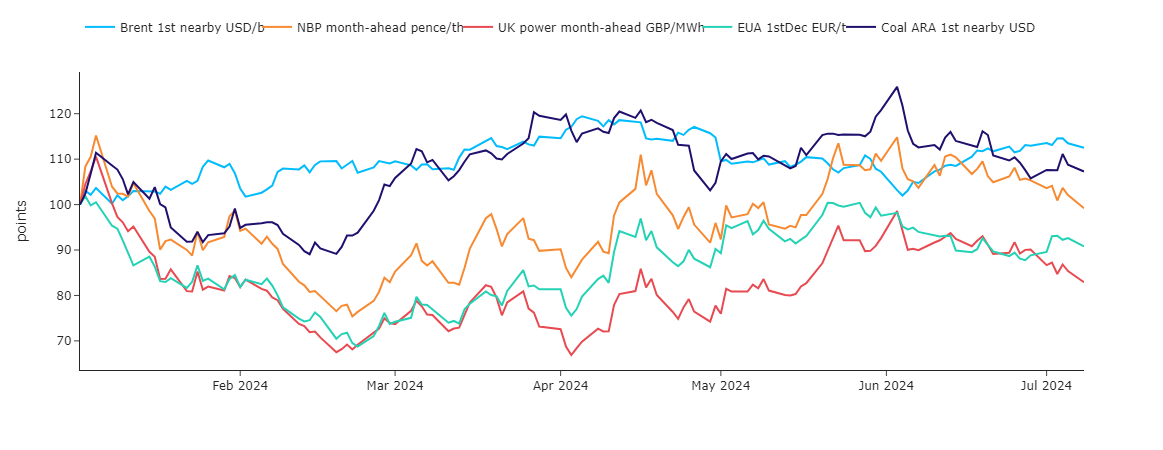
- The correlation between emissions and gas prices persists – though, to some extent, the same could be said across the wider UK energy complex (see chart of relative values below).
- Looking to the continent, near-term delivery prices are marginally lower off the back of strong solar generation strong over north-western Europe.
- The weather outlook appears sunnier and there is potential for upward wind forecasts revisions.
- Prices down the curve dropped following a decline both on the gas and carbon markets.
- The impact of coal prices is also being felt, the “calendar contract” has been in a downtrend for several weeks making power from coal cheaper than gas (on some, not all, maturities).
- European Carbon prices (EUAs) lost a chunk of value yesterday closing at €68.99/tonne (down circa. 2%).
- Fundamentals remain bearish with high renewable outputs amid depressed industrial production forecasts.
- Back in the UK, UKAs (UK Carbon Allowances) followed our prediction that prices were due to fall (as indicated by RSI divergence) – now trading at circa. £42/tonne.
- Prices are now in a confirmed ascending trend channel testing the lower extremity – with £40/tn as a strong area of support to the downside – so a retest of this level is likely if EUAs can maintain bearish momentum.
- Our electricity generation mix is bearish in nature today with renewables contributing 43%, thermal at 18% (gas and coal) and low carbon at 28% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are looking summer-esque, and are on target to achieve £61/mwh (or circa. 6.1p/kwh excluding non-energy).