



Fri, 10th Oct ’25
GAS
- It’s been a quiet week on the markets.
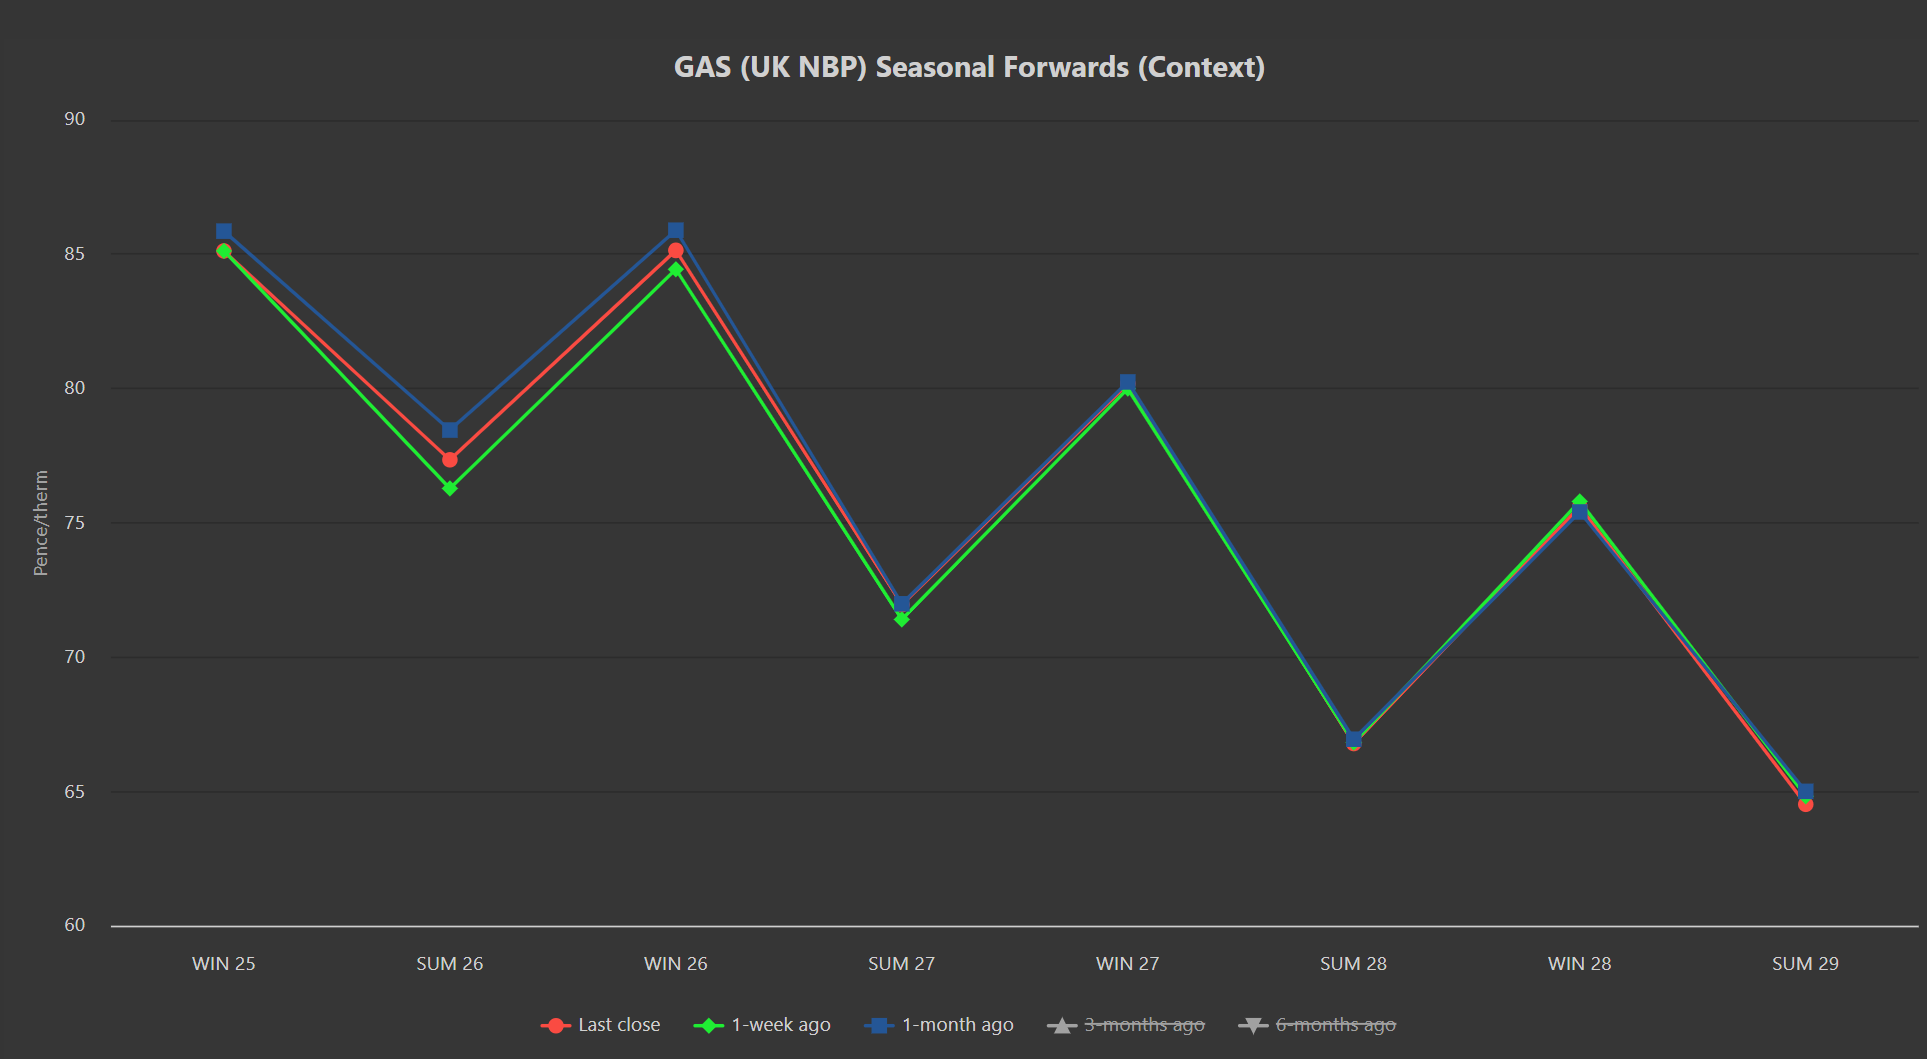
- The chart below details Seasonal Forward prices at last close; one week ago; one month ago.
- As you can see, values are barely altered – reflecting very low volatility this last few weeks for Forward periods of delivery.
- Given mild temperatures, the heating season still looks a little way off – ordinarily 1st Nov marks the period when we expect storage injections to end (and withdrawals to begin in earnest).
- As such, prices have resumed rangebound action with Month-Ahead prices having only bracketed in a 12% range since 1st Sep.
- Steady supply continues to mitigate the hazards of impending cold weather – fortunately, Europe remains a popular destination for LNG (given greater profitability for cargoes headed to Europe over Asia).
- In other news, Egypt looks likely to defer some LNG deliveries from Q4 2025 into next year – with talk of a glut of LNG come ’27, is this a sign of things to come (i.e., supply outstripping demand)?
- Monthly Day-Ahead averages for October so far are at 78p/therm (or 2.66p/kwh exc. non-gas).
- In short, whilst Winter-25 has officially begun, we’re yet to feel the effects of increased demand/increased withdrawals/worries over supply tightness.
- And so, whilst momentum remains neutral to bearish, traders are all too aware of the fragility of the European gas balance.
ELECTRICITY & CARBON
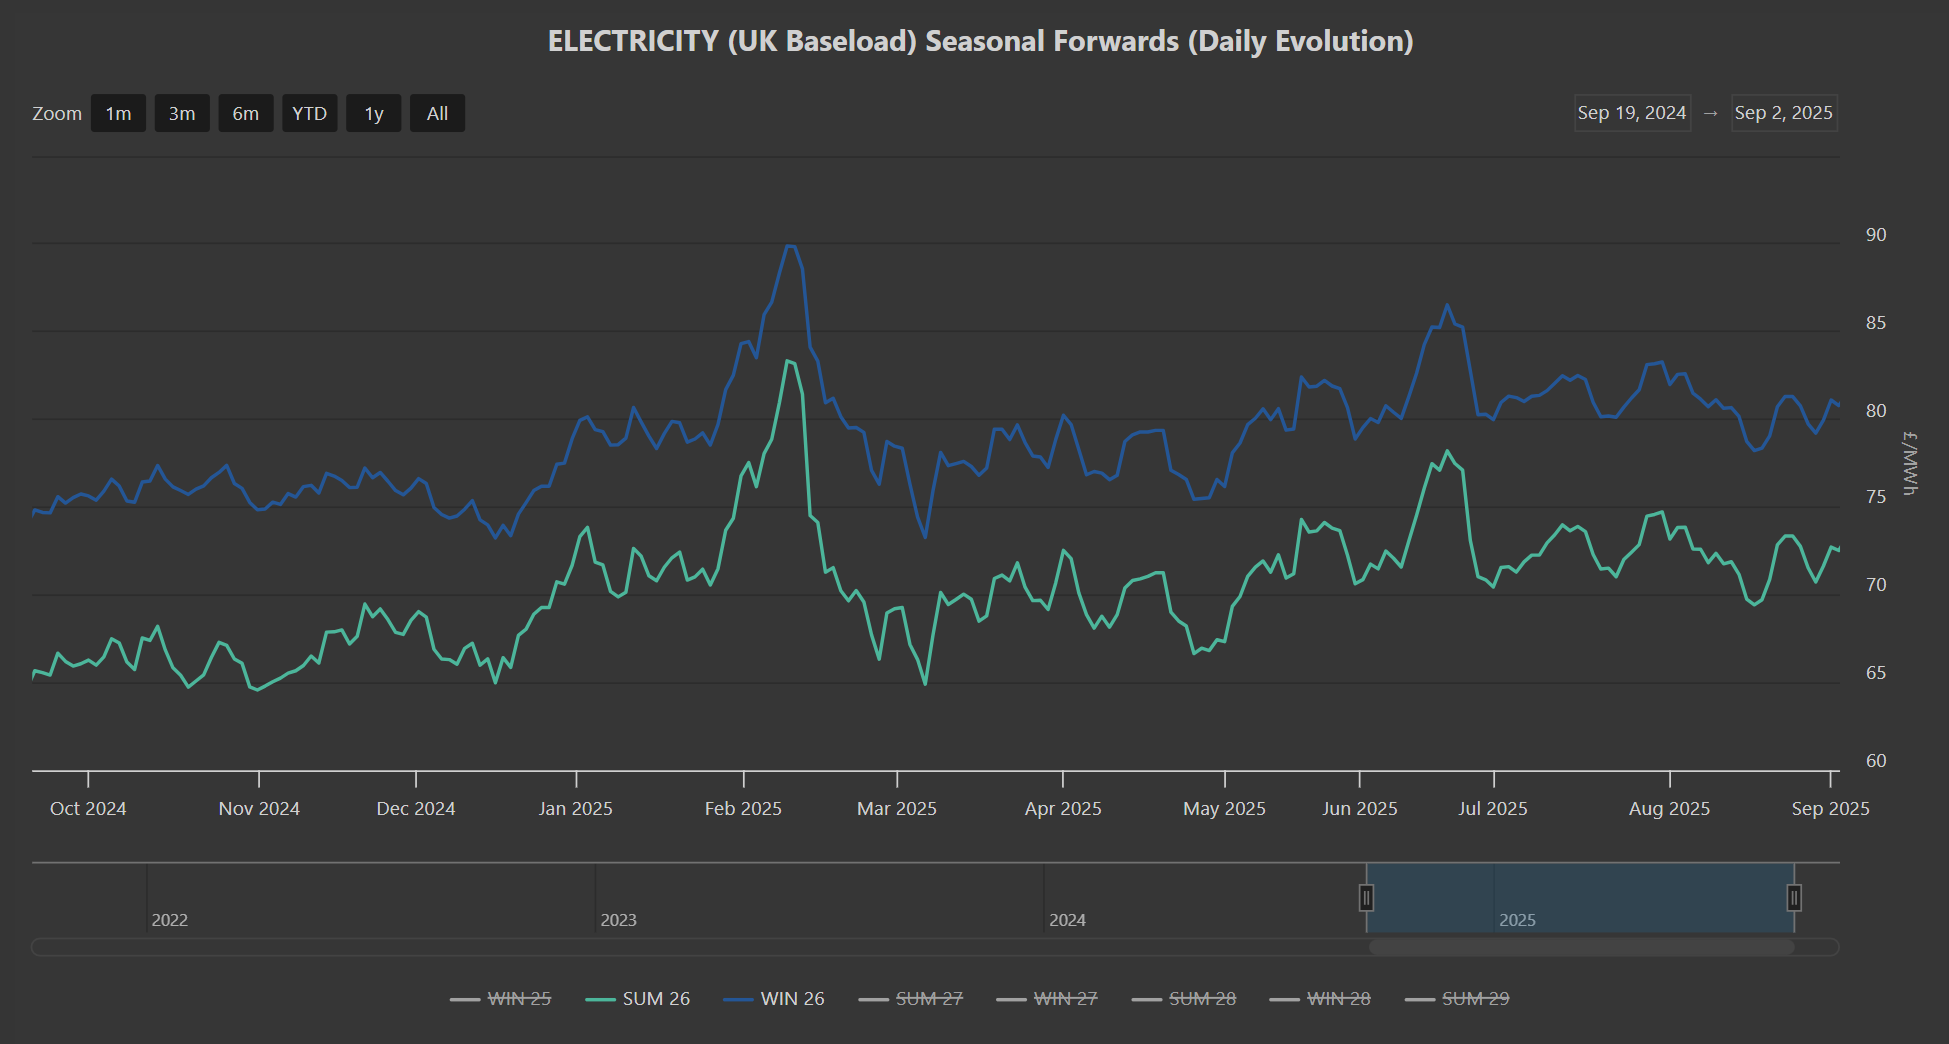
- The chart below details Summer-26/Winter-26 delivery prices dating back to the onset of last winter.
- If recent history is anything to go by then, we should expect prices for the front 2-Seasons to increase over the coming months, peak in Feb ’26, then drop off as temperatures rise into Mar ’26.
- Certainly, I think it’s fair to say that current prices do not feel inflated – and so a drop-off over the winter months would seem very unlikely.
- On the Carbon side of things, UKAs are increasingly correlated to EUAs (following the “common understanding” reached between the UK/Europe to link emissions markets at the UK-EU summit in London on 19th May).
- Dec ’25 UKA benchmark prices are holding steady in the mid-50s (currently at £55/tn).
- Today’s UK electricity generation mix is bullish in nature – specifically, renewables are contributing 28%, thermal at 42% (gas and coal) and low carbon at 19% (nuclear and imports).
- Monthly Day-Ahead averages for October so far are at £66/mwh (or 6.6p/kwh exc. non-energy).