



Fri, 17th Oct ’25
GAS
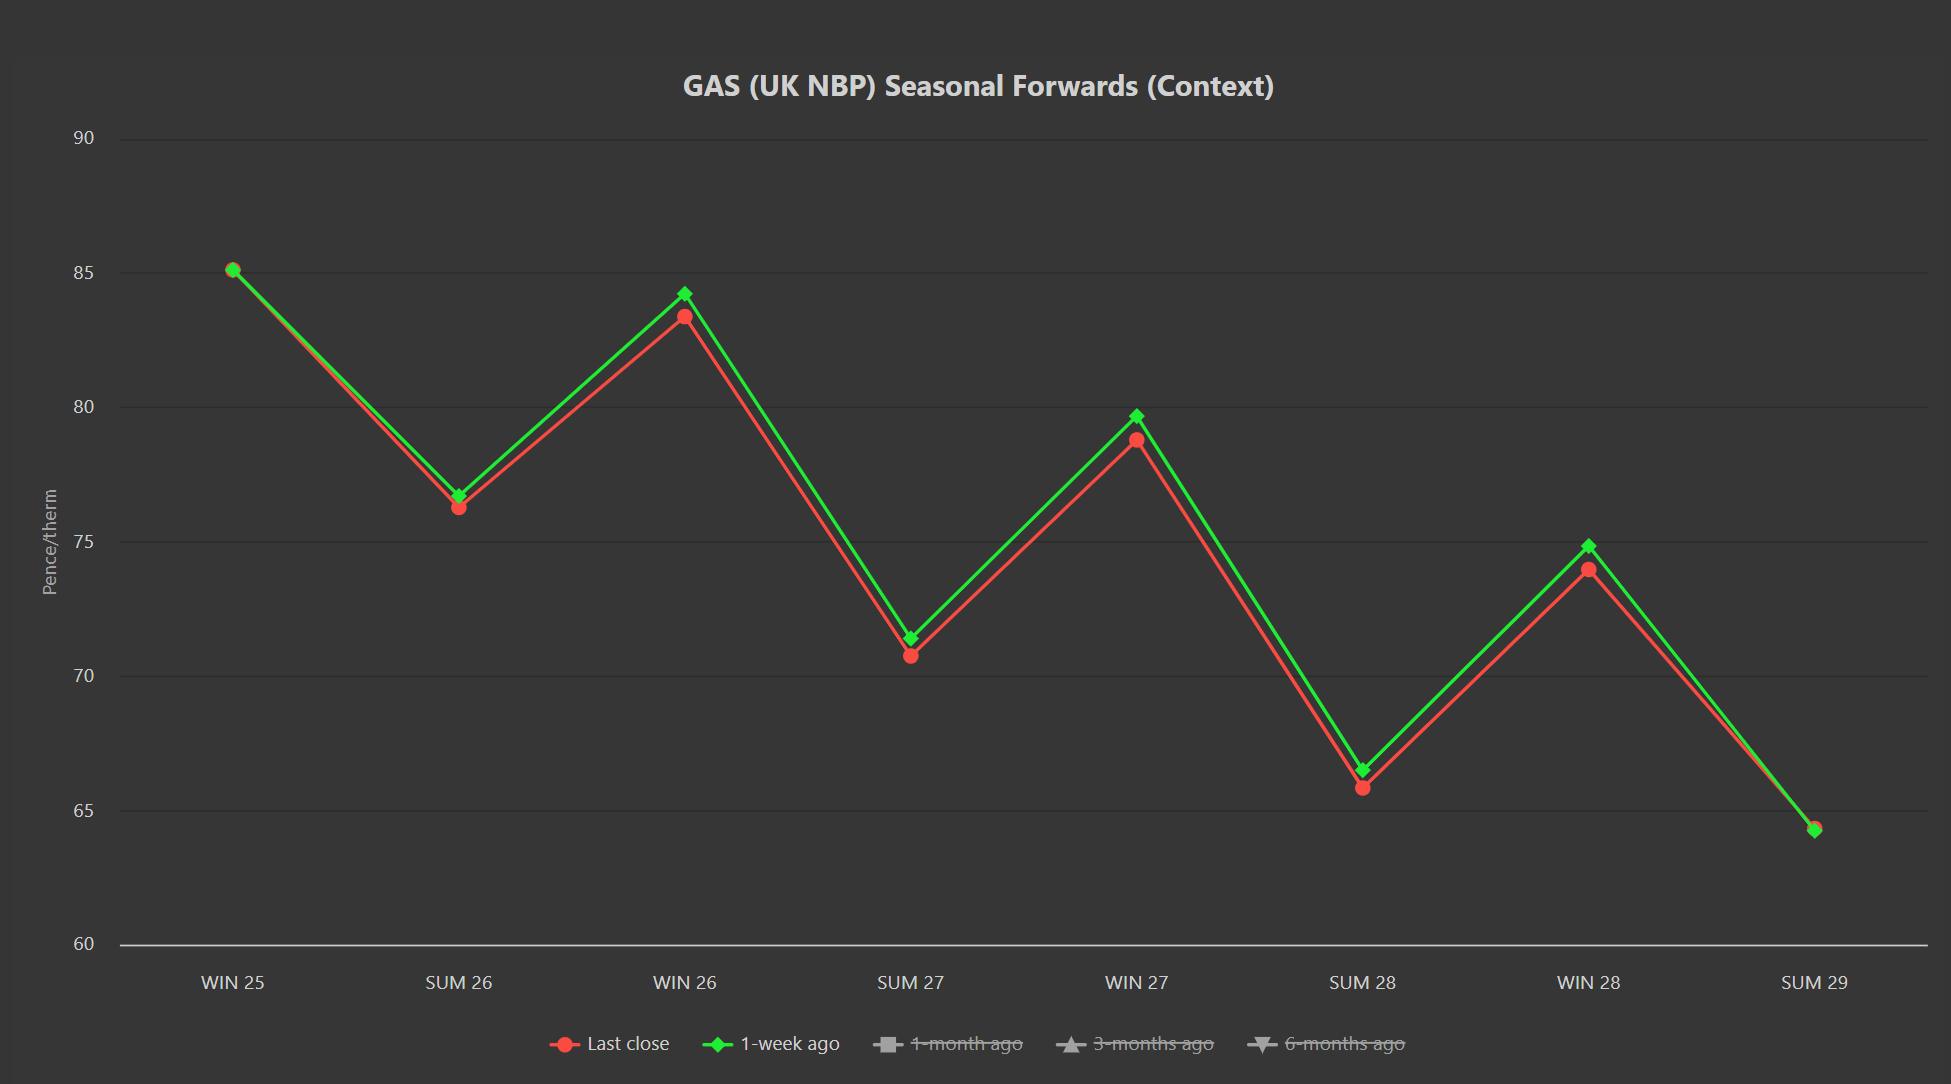
- Seasonal Forward prices are very marginally down versus 1-week ago (please see chart below).
- It’s been another sedate week on the markets amid continued stable fundamentals.
- The end of maintenance at both Dvalin and Oseberg has inevitably resulted in improved Norwegian flows into Europe/the UK.
- After a week of heavy gas-for-power burn, temperatures into the weekend look set to climb above seasonal norms coupled with improved wind outputs – so pressure on storage withdrawals should ease.
- European storage is at 83% versus the 5-year average of 95% – so, with the heating season due to begin in only a couple of weeks, all eyes will be on mid-to-long range weather forecasts.
- In other news, market participants are keeping one eye on Russia’s energy trade (and the resumed US efforts to mediate a peace agreement in Ukraine).
- Following Trump’s announcement that he intends to meet with Putin again soon, prices fell only briefly – reflecting that traders don’t necessarily share Trump’s confidence.
- All in all, a quiet news week, and a balanced market.
- Monthly Day-Ahead averages for October remain at 78p/therm (or 2.66p/kwh exc. non-gas).
- In short, whilst Winter-25 has officially begun, we’re yet to feel the effects of increased demand/increased withdrawals/worries over supply tightness.
- And so, whilst momentum remains neutral, traders are all too aware of the fragility of the European gas balance.
ELECTRICITY & CARBON
- Not surprisingly, electricity prices have mirrored the low volatility of gas markets.
- On the Carbon side of things, UKAs are increasingly correlated to EUAs (following the “common understanding” reached between the UK/Europe to link emissions markets at the UK-EU summit in London on 19th May).
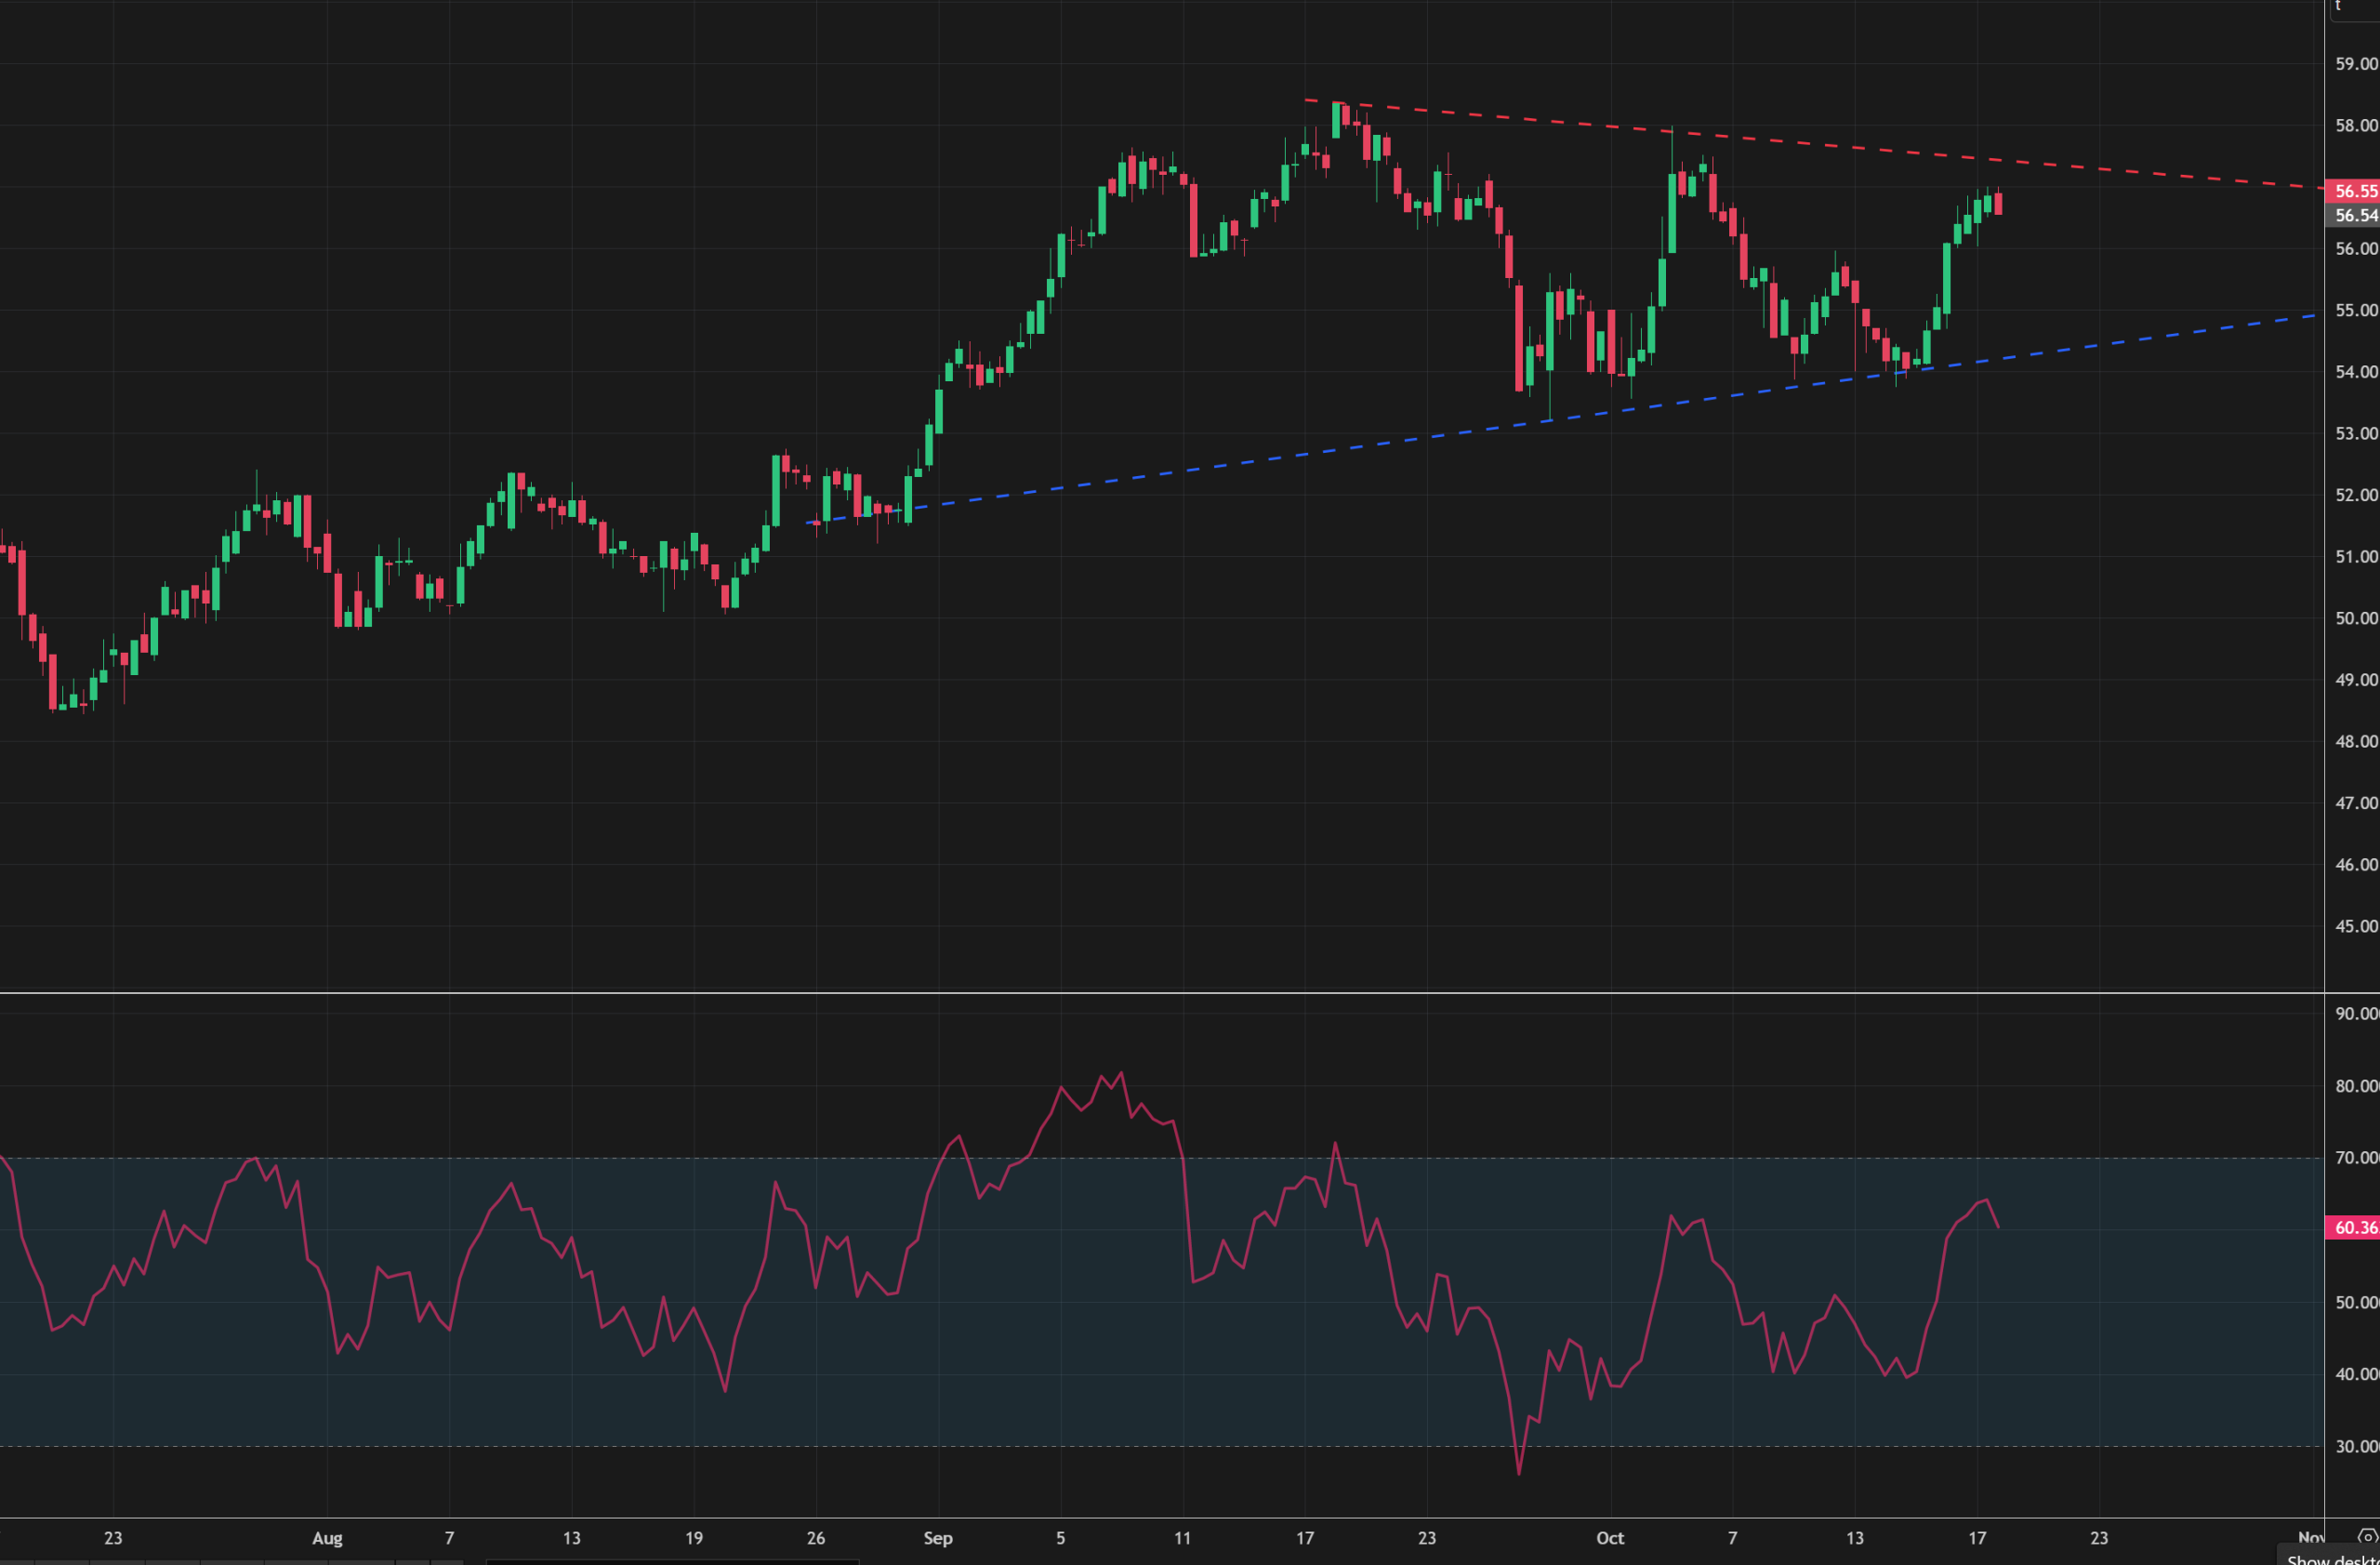
- Dec ’25 UKA benchmark prices are bracketing in a triangle/consolidation pattern (please see chart below).
- At the time of writing, prices are holding steady in the mid-50s (currently at £56/tn) – having failed to break out of the triangle to the downside earlier this week.
- The secondary market remains at a discount to auction settlement prices – reflecting increased speculative interest in emissions as winter deepens.
- Today’s UK electricity generation mix is bullish in nature – specifically, renewables are contributing 10%, thermal at 54% (gas and coal) and low carbon at 22% (nuclear and imports).
- Monthly Day-Ahead averages for October so far are at £77/mwh (or 7.7p/kwh exc. non-energy).