



Fri, 3rd Oct ’25
GAS
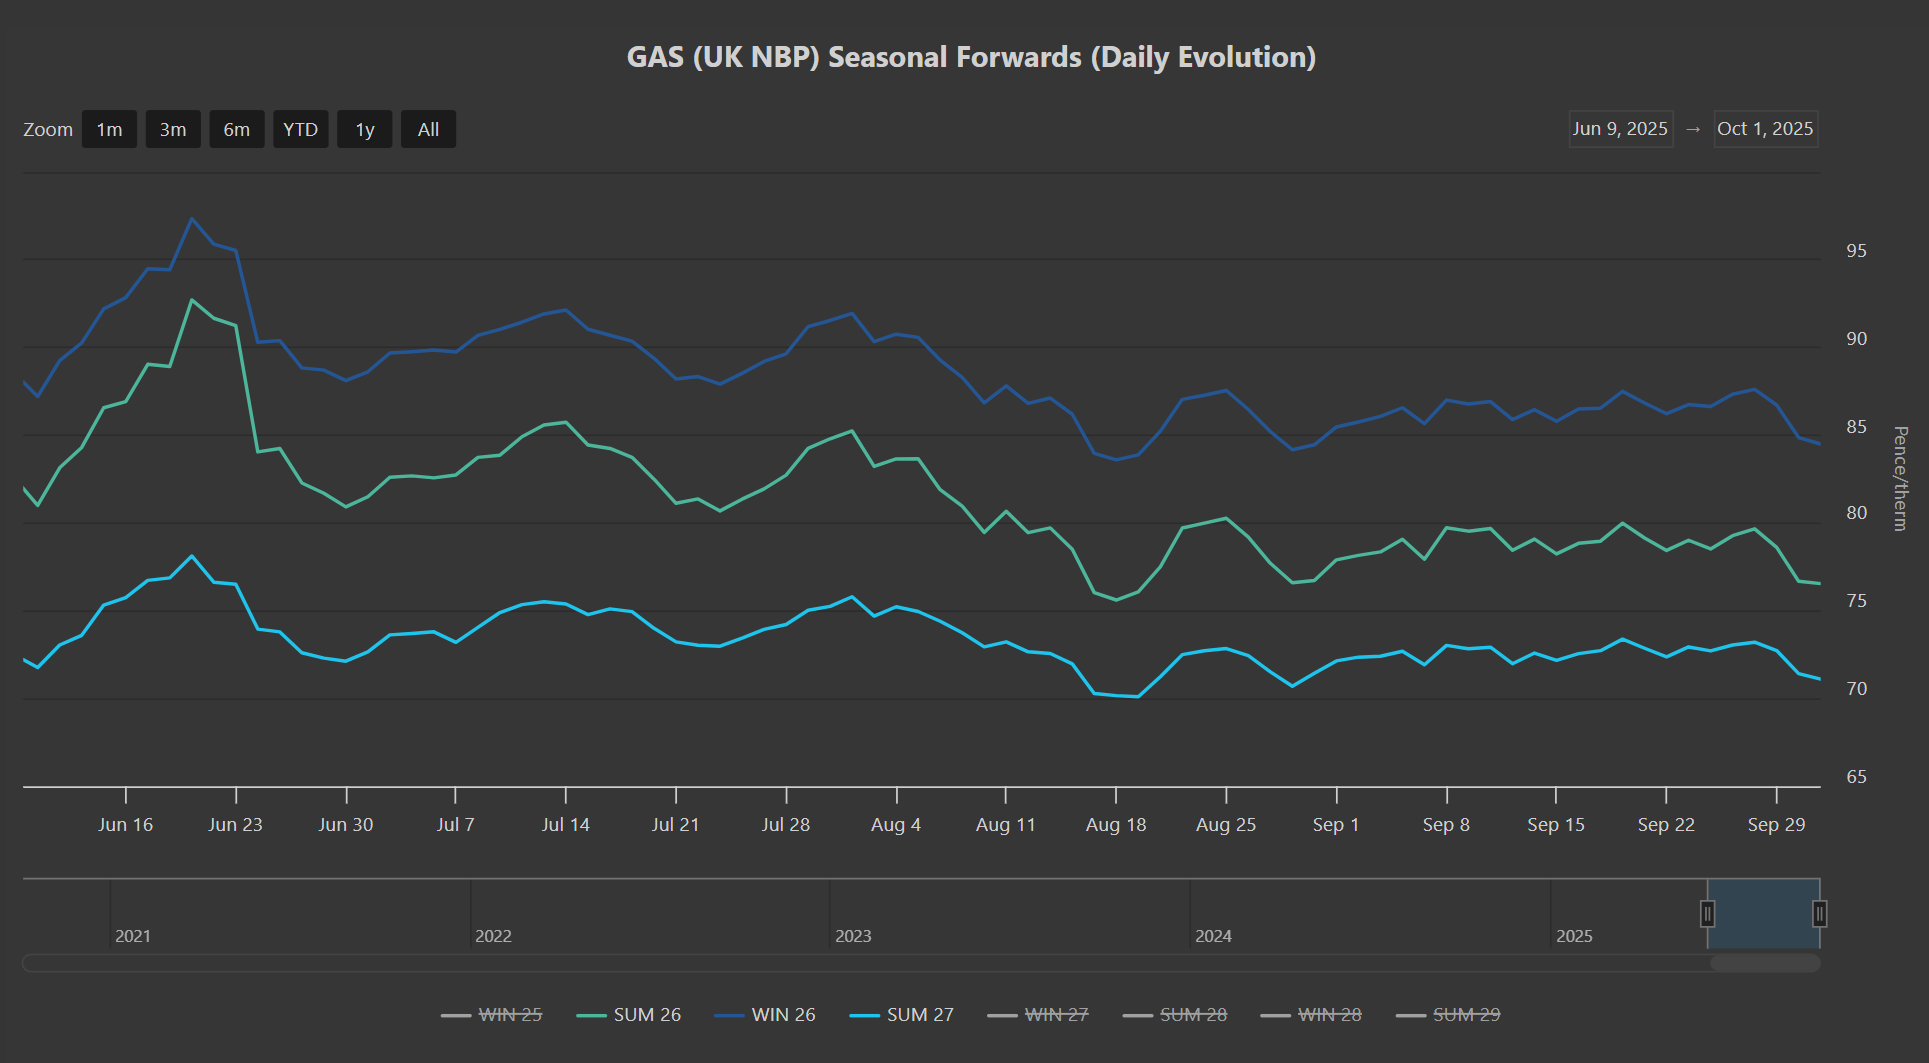
- Winter-25 is upon us (beginning 1st Oct).
- High wind outputs are limiting gas-for-power burn.
- Norwegian scheduled maintenance is all but over for another year.
- Following this summer’s stockpiling drive, European storage fullness is at 83% versus the 5-year average of 93% – just in time for the heating season!
- Despite lingering conerns over weather forecasts and geopolitical banana skins, market participants are undoubtedly confident that we have enough in the tank to make it through the winter months.
- We’ll also keep a close eye on Asian demand – though China’s spot purchases of LNG have fallen significantly Y-o-Y – inevitably freeing up more cargoes for Europe (and limiting associated price battles).
- Monthly Day-Ahead averages for September came in at 79p/therm (or 2.7p/kwh exc. non-gas).
- Monthly Day-Ahead averages for October so far are at 72p/therm (or 2.4p/kwh exc. non-gas).
- In short, we’re enjoying a late summer lull off the back of benign fundamentals with the front 3-Seasons drifting lower (please see chart below).
ELECTRICITY & CARBON
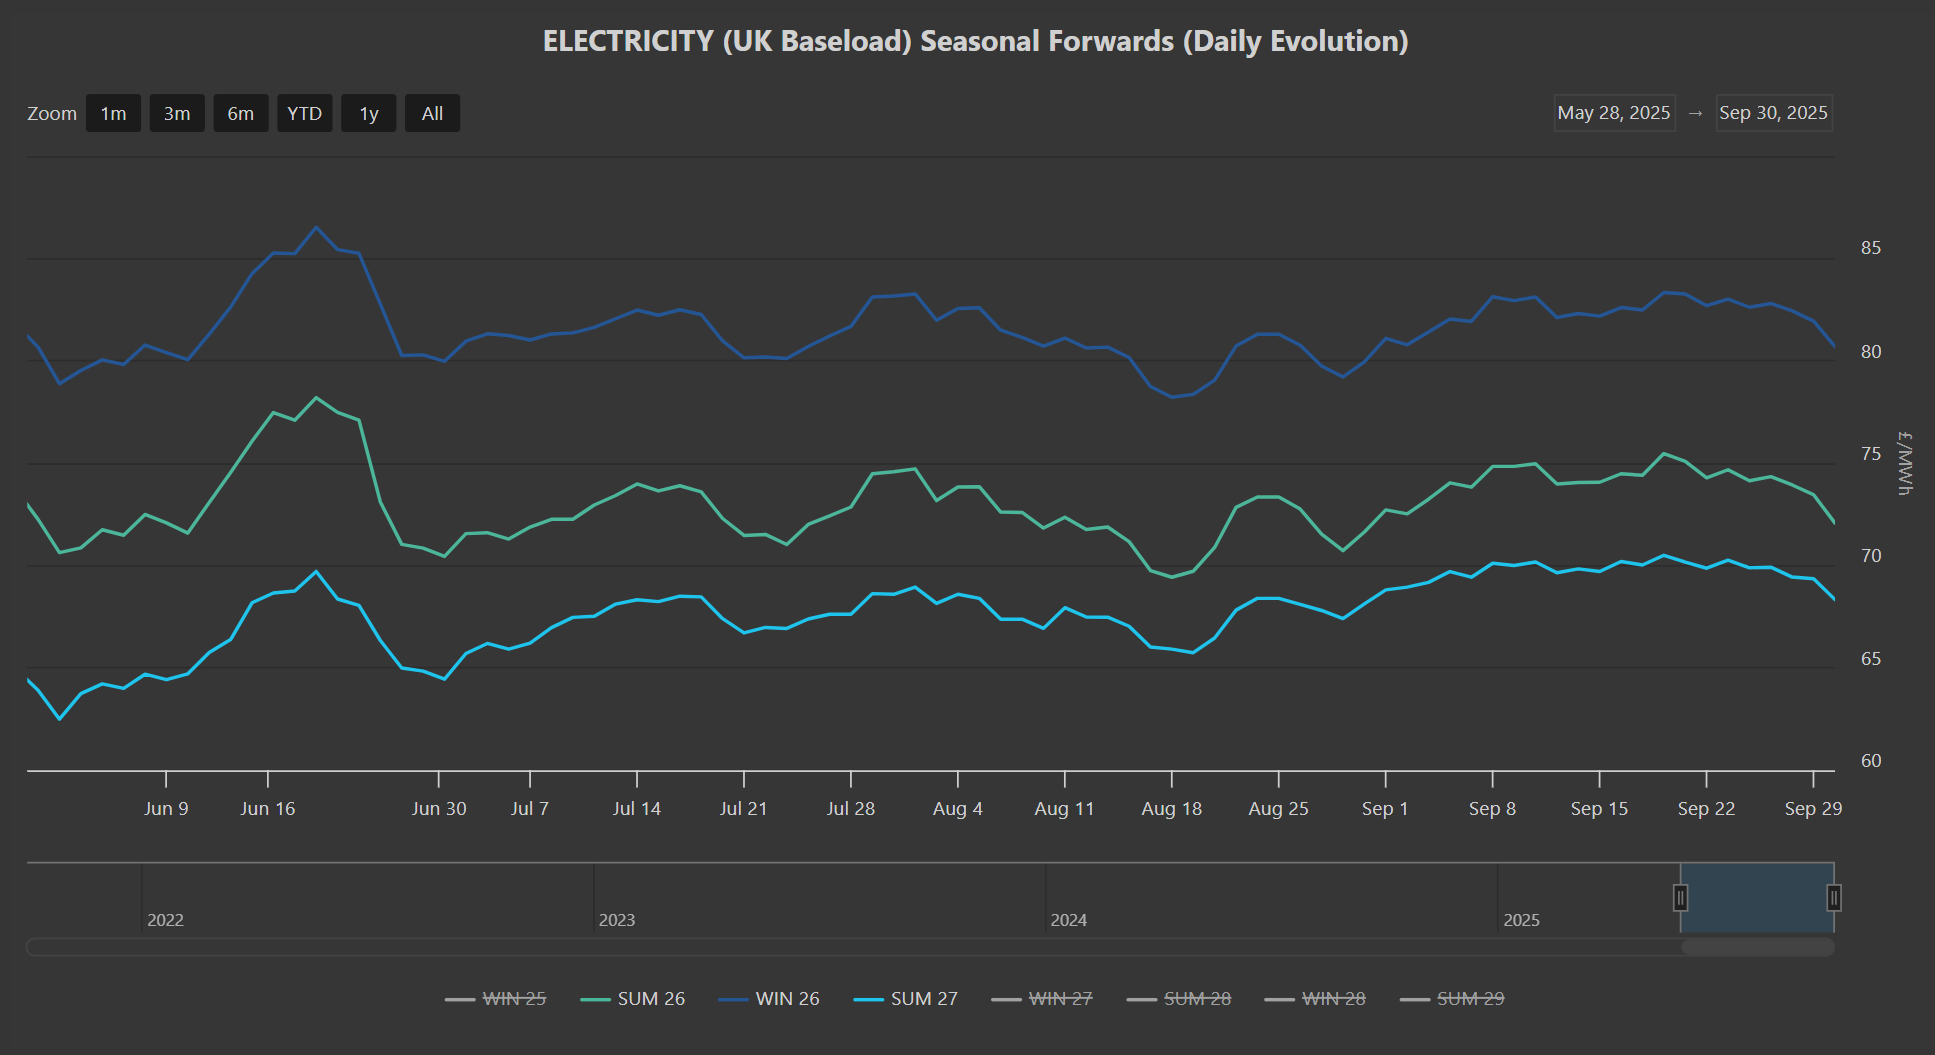
- Electricity prices are seeing a more modest drop-off compared to gas – nonetheless, the front 3-Seasons are rolling over despite the prospect of winter supply tightness around the corner.
- On the Carbon side of things, UKAs are increasingly correlated to EUAs (following the “common understanding” reached between the UK/Europe to link emissions markets at the UK-EU summit in London on 19th May).
- Dec ’25 UKA benchmark prices remain at £57/tn.
- Today’s UK electricity generation mix is bearish in nature – specifically, renewables are contributing 56%, thermal at 17% (gas and coal) and low carbon at 16% (nuclear and imports).
- Monthly Day-Ahead averages for September came in at £67/mwh (or 6.7p/kwh exc. non-energy).
- Monthly Day-Ahead averages for October so far are at £52/mwh (or 5.2p/kwh exc. non-energy).