



Wed, 23rd Oct ’24
GAS
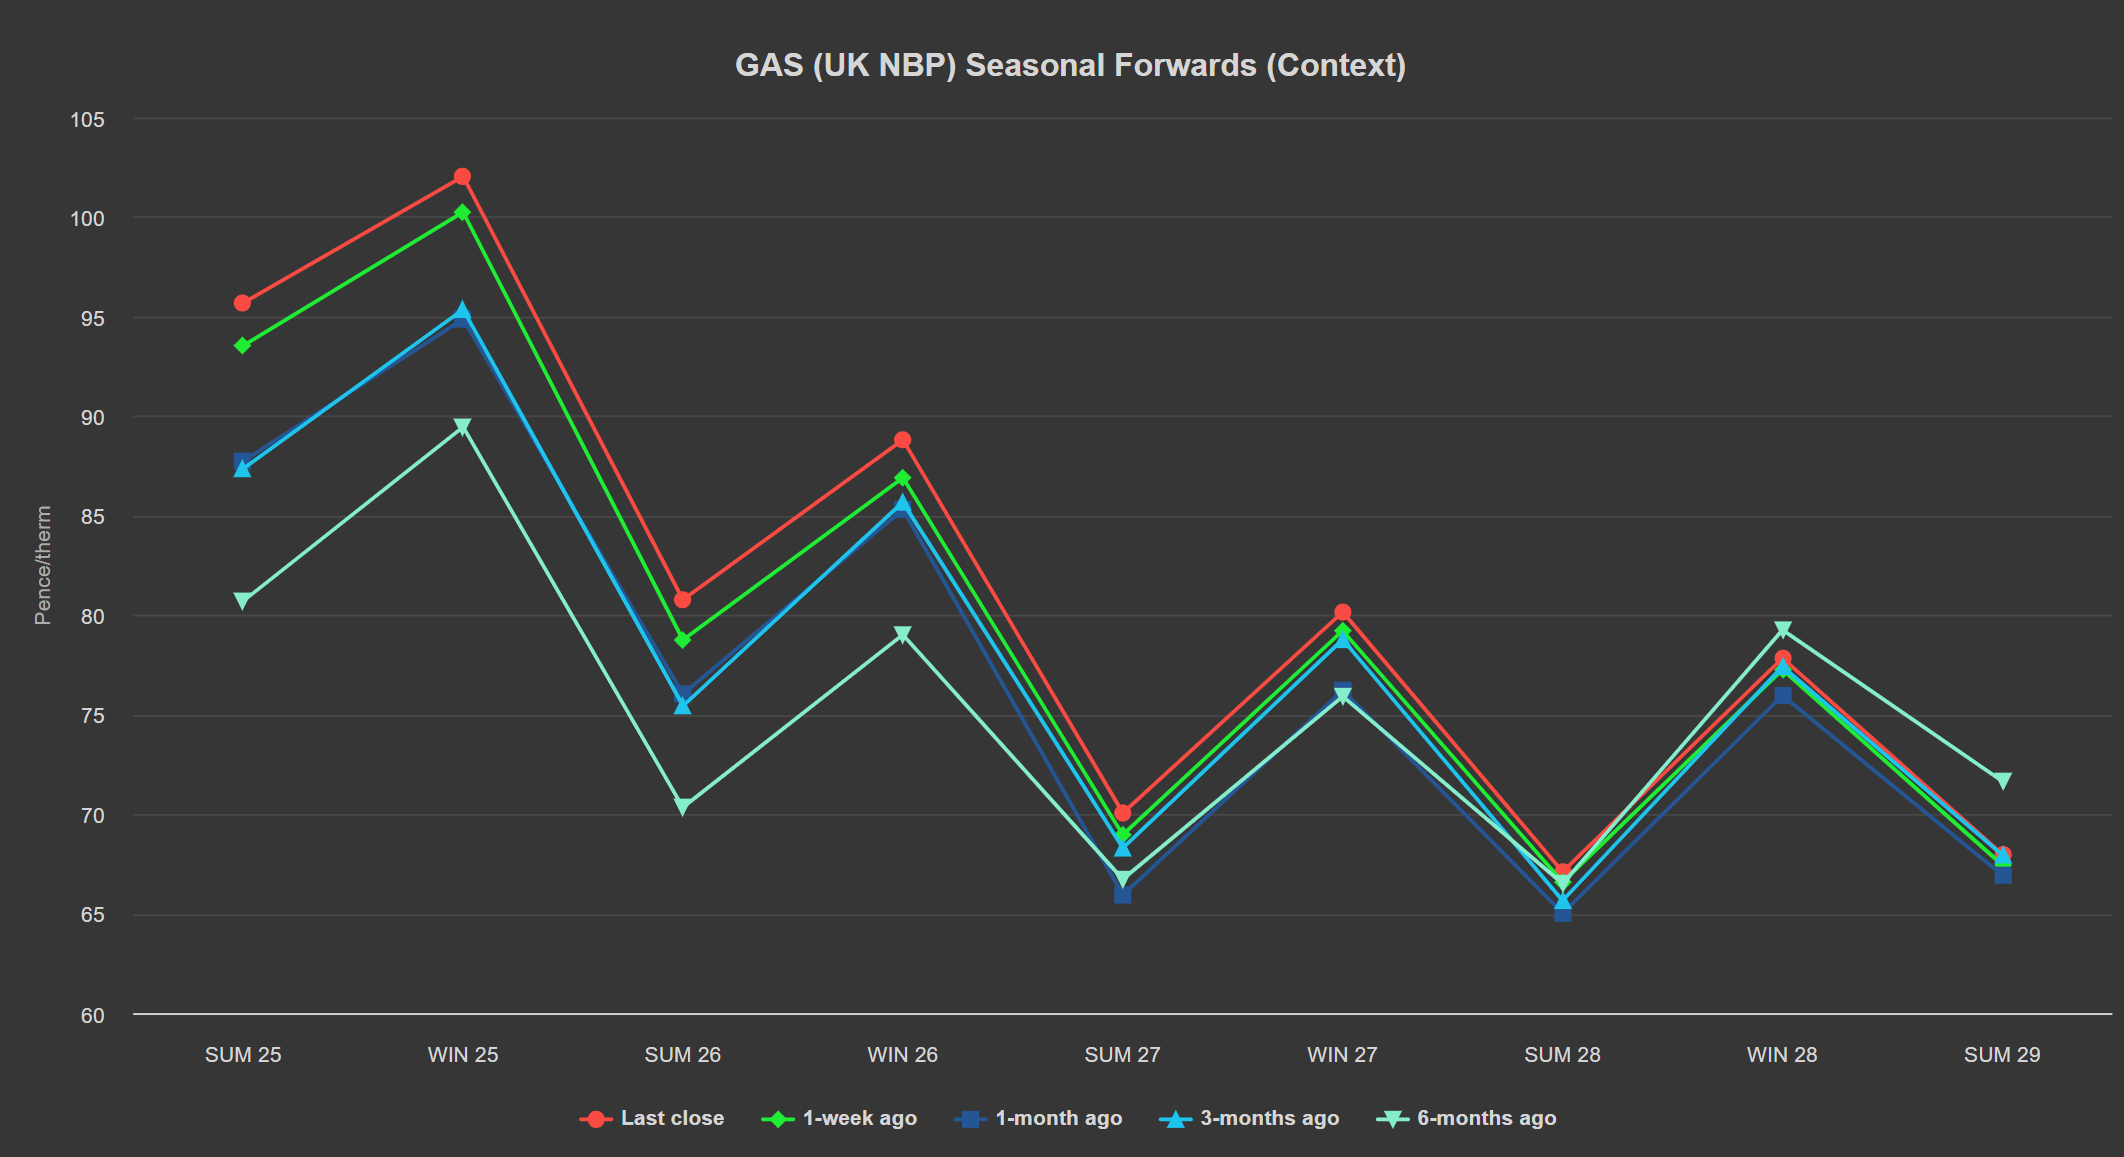
- Prices are starting to feel wintry – Seasonal Forwards are up versus 1-week/1-month/3-months ago/6-months ago (see chart below).
- Day-Ahead prices have now risen above Year-Ahead prices reflecting the wintry tone of near-term delivery.
- Norwegian outages remain a primary supportive element, as does a shortage of LNG arrivals to UK shores against a backdrop of global conflict.
- Yesterday’s price spike could be attributed to smoke being detected at the Sleipner field in Norway – leading to 7 million cubic metres of flow going offline.
- On the geopolitical side, leaked rumours of Israel’s imminent attack on Iran has given market participants the jitters.
- In more bullish news, the UK system opened long today (supply outstripping demand forecast) off the back of a significant reduction in storage injections.
- It’s fair to argue that European prices need to rise to attract more LNG cargos to our waters (and away from Asia).
- On the weather side, expect warm conditions for the time of year coupled with poor wind outputs (increasing gas-for-power generation).
- Solid European storage at 95% (versus the 5-year average of 97%) is keeping a lid on bullish momentum.
- Notably, Russia’s pipeline exports to China are up 40% y-o-y – meaning Russia is now exporting more gas to Asia than it does Europe.
- It’s likely these exports will increase still further with the completion of the Far Eastern pipeline in 2027.
- However, Chinese demand remains in question, with recent economic indicators reinforcing fears of deflation and the need for meaningful stimulus measures – though the Communist Party remain reluctant to devalue the yuan and trigger capital flight (which seems inevitable).
- Monthly Day-Ahead averages so far this month are on target to achieve 96.871p/therm (or approx. 3.305p/kwh excluding non-gas).
ELECTRICITY & CARBON
- Looking to the continent, French nuclear generation is now forecast to the high range of the previous years.
- EUAs began yesterday on a bearish note, rapidly making a €61.27/tn low early in the day.
- However, it quickly recovered making a €62.56/tn high by noon off the back of rising gas prices.
- Nonetheless, the Dec ’24 benchmark contract is making lower highs, day on day – reflecting a modest but defined downtrend underway.
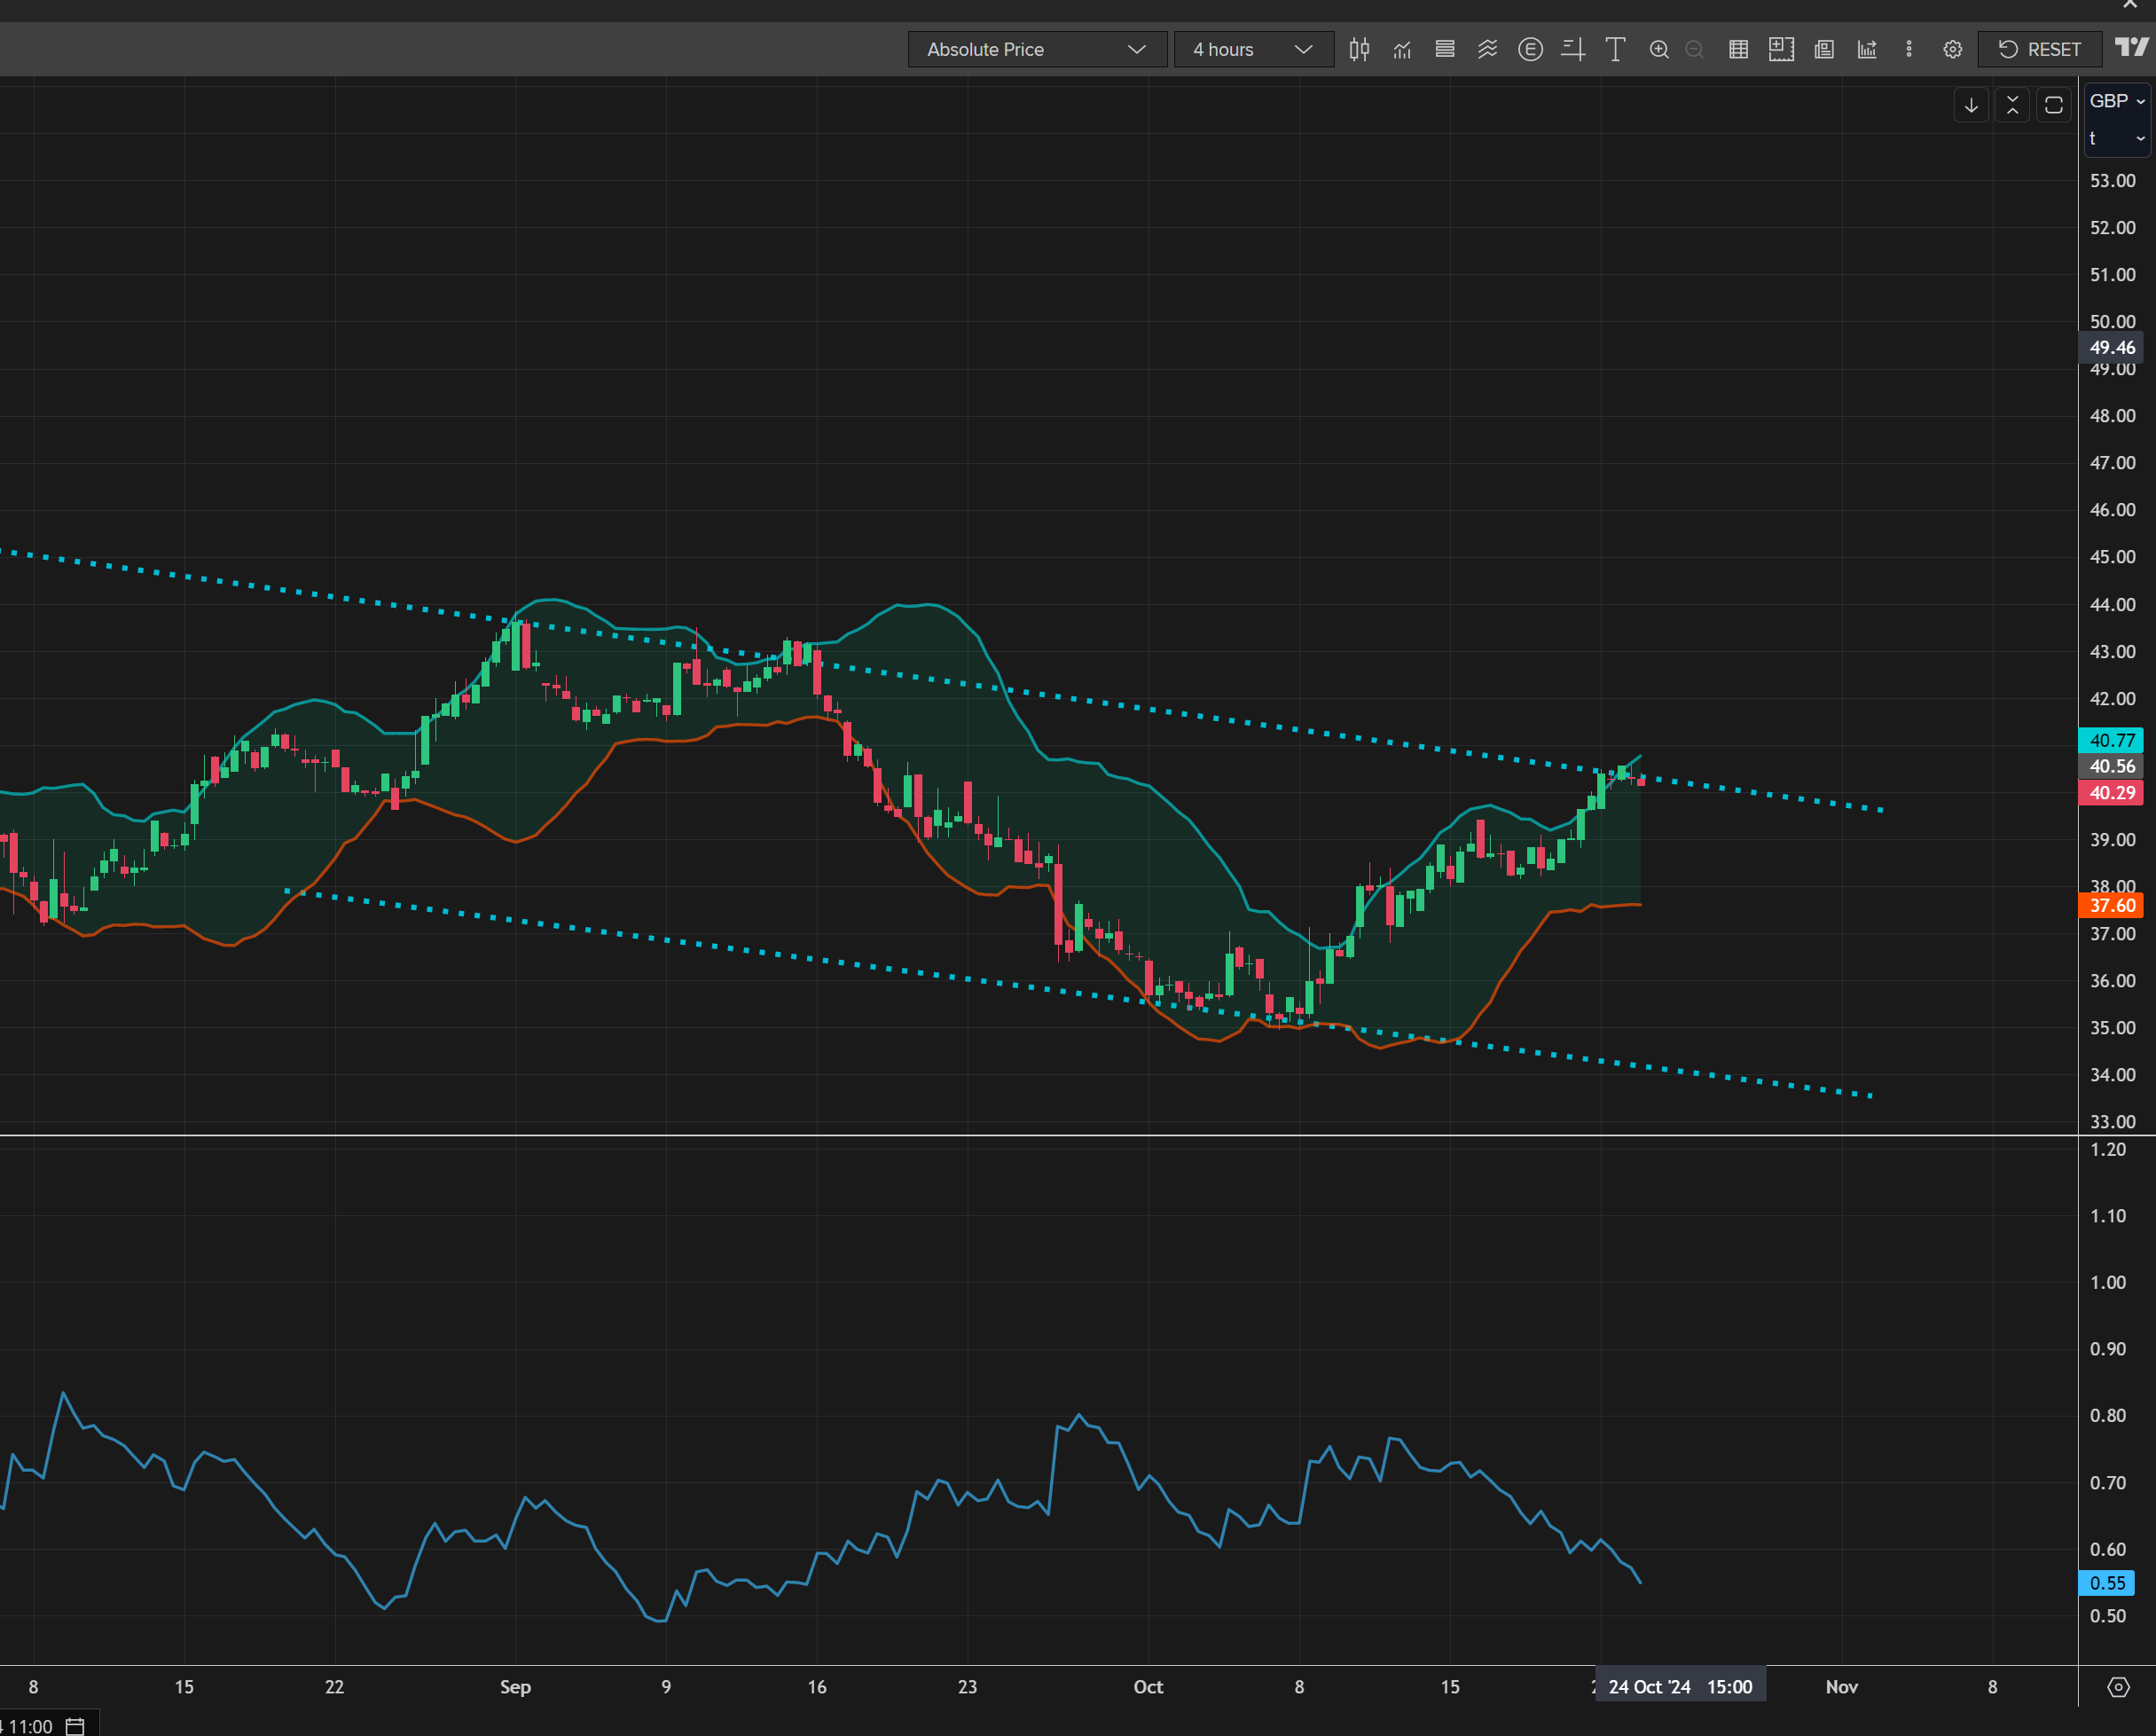
- Conversely, UKAs persist on an independent bull run – now at the upper extremity of descending trend channel that is the wider downtrend which began back in Jul-24.
- For now, compliance buyers appear to be sitting on the sidelines waiting for the speculators to complete their revised positioning.
- Fundamentally, the fall in UKAs over the summer was attributed to market participants’ reaction to UK policy review (or the Free Allocation Review).
- The outcome being that the expected scarcity of UKAs come 2026 has now been pushed back to 2027 – resulting in speculators reducing long (buy) exposure.
- However, the recent bull run is evidence of investors scaling back-in at lower levels given the great value on offer this last couple of weeks.
- Our electricity generation mix is neutral in nature today with renewables contributing 36%, thermal at 33% (gas and coal) and low carbon at 13% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £80.030/mwh (or approx. 8.030p/kwh excluding non-energy).