



Fri, 18th Oct ’24
GAS
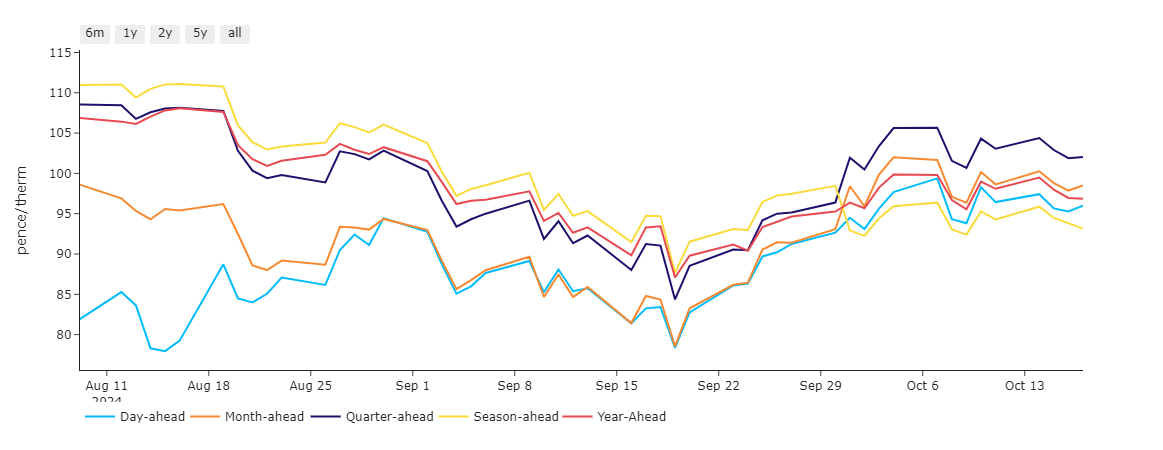
- At the end of a relatively flat/directionless/balanced week, Seasonal Forwards are marginally down on the week, but still up versus 1-month/3-months/6-months ago.
- It’s not surprising then (given the absence of volatility) that Prompt pricing (Day/Month/Quarter/Season/Year-Ahead) are flat for the week and at near parity – all priced within 9% of one another (see chart below).
- As of this morning, all Seasonal Forwards down the curve have found their way back below 100p/therm off the back of temperatures above seasonal norms meaning reduced heating demand, and solid wind outputs forecast for the coming days reducing gas-for-power demand.
- Geopolitically, fears over global supply disruption should conflicts escalate is evidently priced-in – as such, even the confirmed killing of Yahia Sinwar (the alleged mastermind of Hamas’ 7th Oct attack on Israel) has had little to no impact on market sentiment.
- On the supply side, extended Norwegian outages are limiting flow into Europe and the UK – though the picture is much improved versus the end of Sep-24.
- Demand has returned to seasonal norms today (after a couple of weeks being above seasonal norms) amid a backdrop of European storage at 95% fullness versus a 5-year average of 95%!
- For now it would seem markets have found an uneasy equilibrium, and current prices represent fair value.
- Increasingly, Chinese economic indicators are reinforcing fears of deflation and underline the need for meaningful stimulus measures – though the Communist Party remain reluctant to devalue the yuan and trigger capital flight (which seems inevitable).
- Monthly Day-Ahead averages so far this month are on target to achieve 96.161p/therm (or approx. 3.281p/kwh excluding non-gas).
ELECTRICITY & CARBON
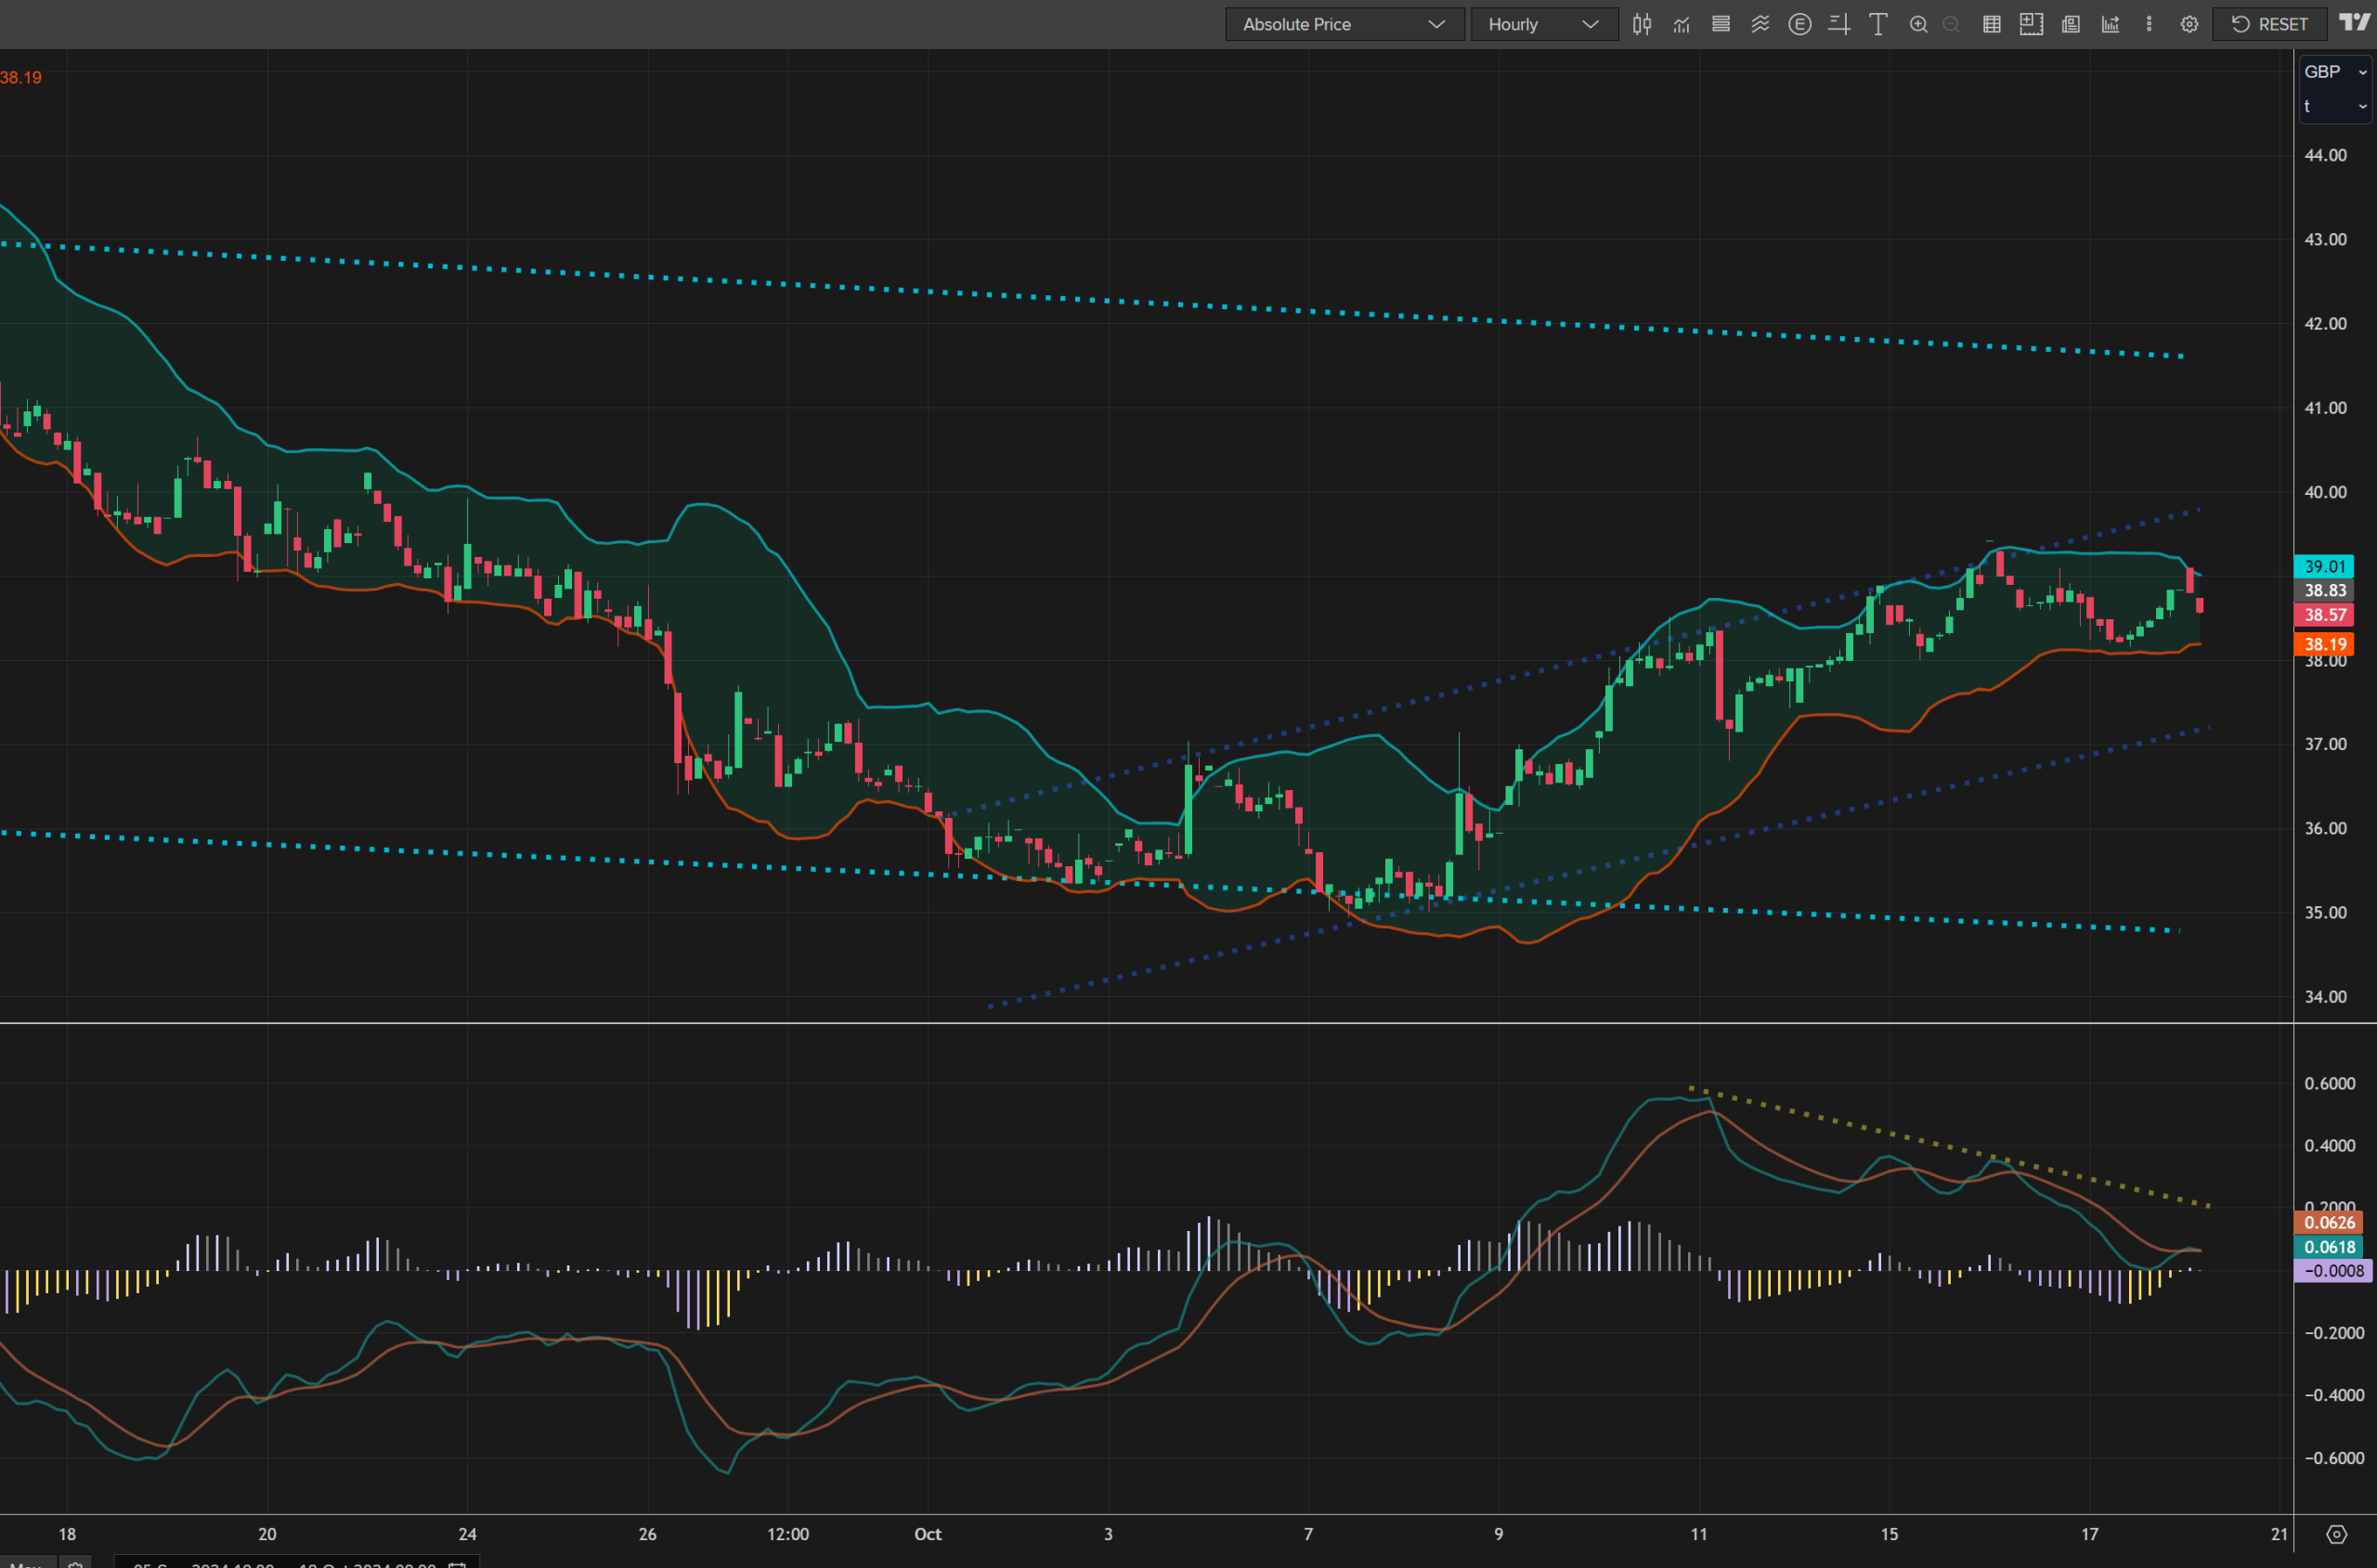
- Looking at UKAs Dec-24 benchmark on the hourly charts, prices have been observing a rising trend channel since the 7th Oct lows of circa. £35/tn – currently siting at £38.57 (see chart below).
- MACD is divergent, volume is low, and ATR (average true range) is falling reflecting surely an unconvincing bullish trend.
- Looking at UK electricity, the front 3 seasons (Summer-25/Winter-25/Summer-26) are barely changed versus 1-week/1-month/3-months/6-months ago – only a 2% difference!
- This reflects of course how flat Seasonal Forwards have been since the onset of Summer-24 following a 50% drop over Winter-23.
- As with gas, an absence of volatility has taken hold with Winter-24 now upon us and global conflicts having little or no impact on current supply/demand dynamics.
- UK electricity prices remain comfortably below £90/mwh front to back, all the way down the curve.
- Our electricity generation mix is neutral in nature today with renewables contributing 38%, thermal at 37% (gas and coal) and low carbon at 13% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £82.163/mwh (or approx. 8.22p/kwh excluding non-energy).