



Wed, 21st Aug ’24
GAS
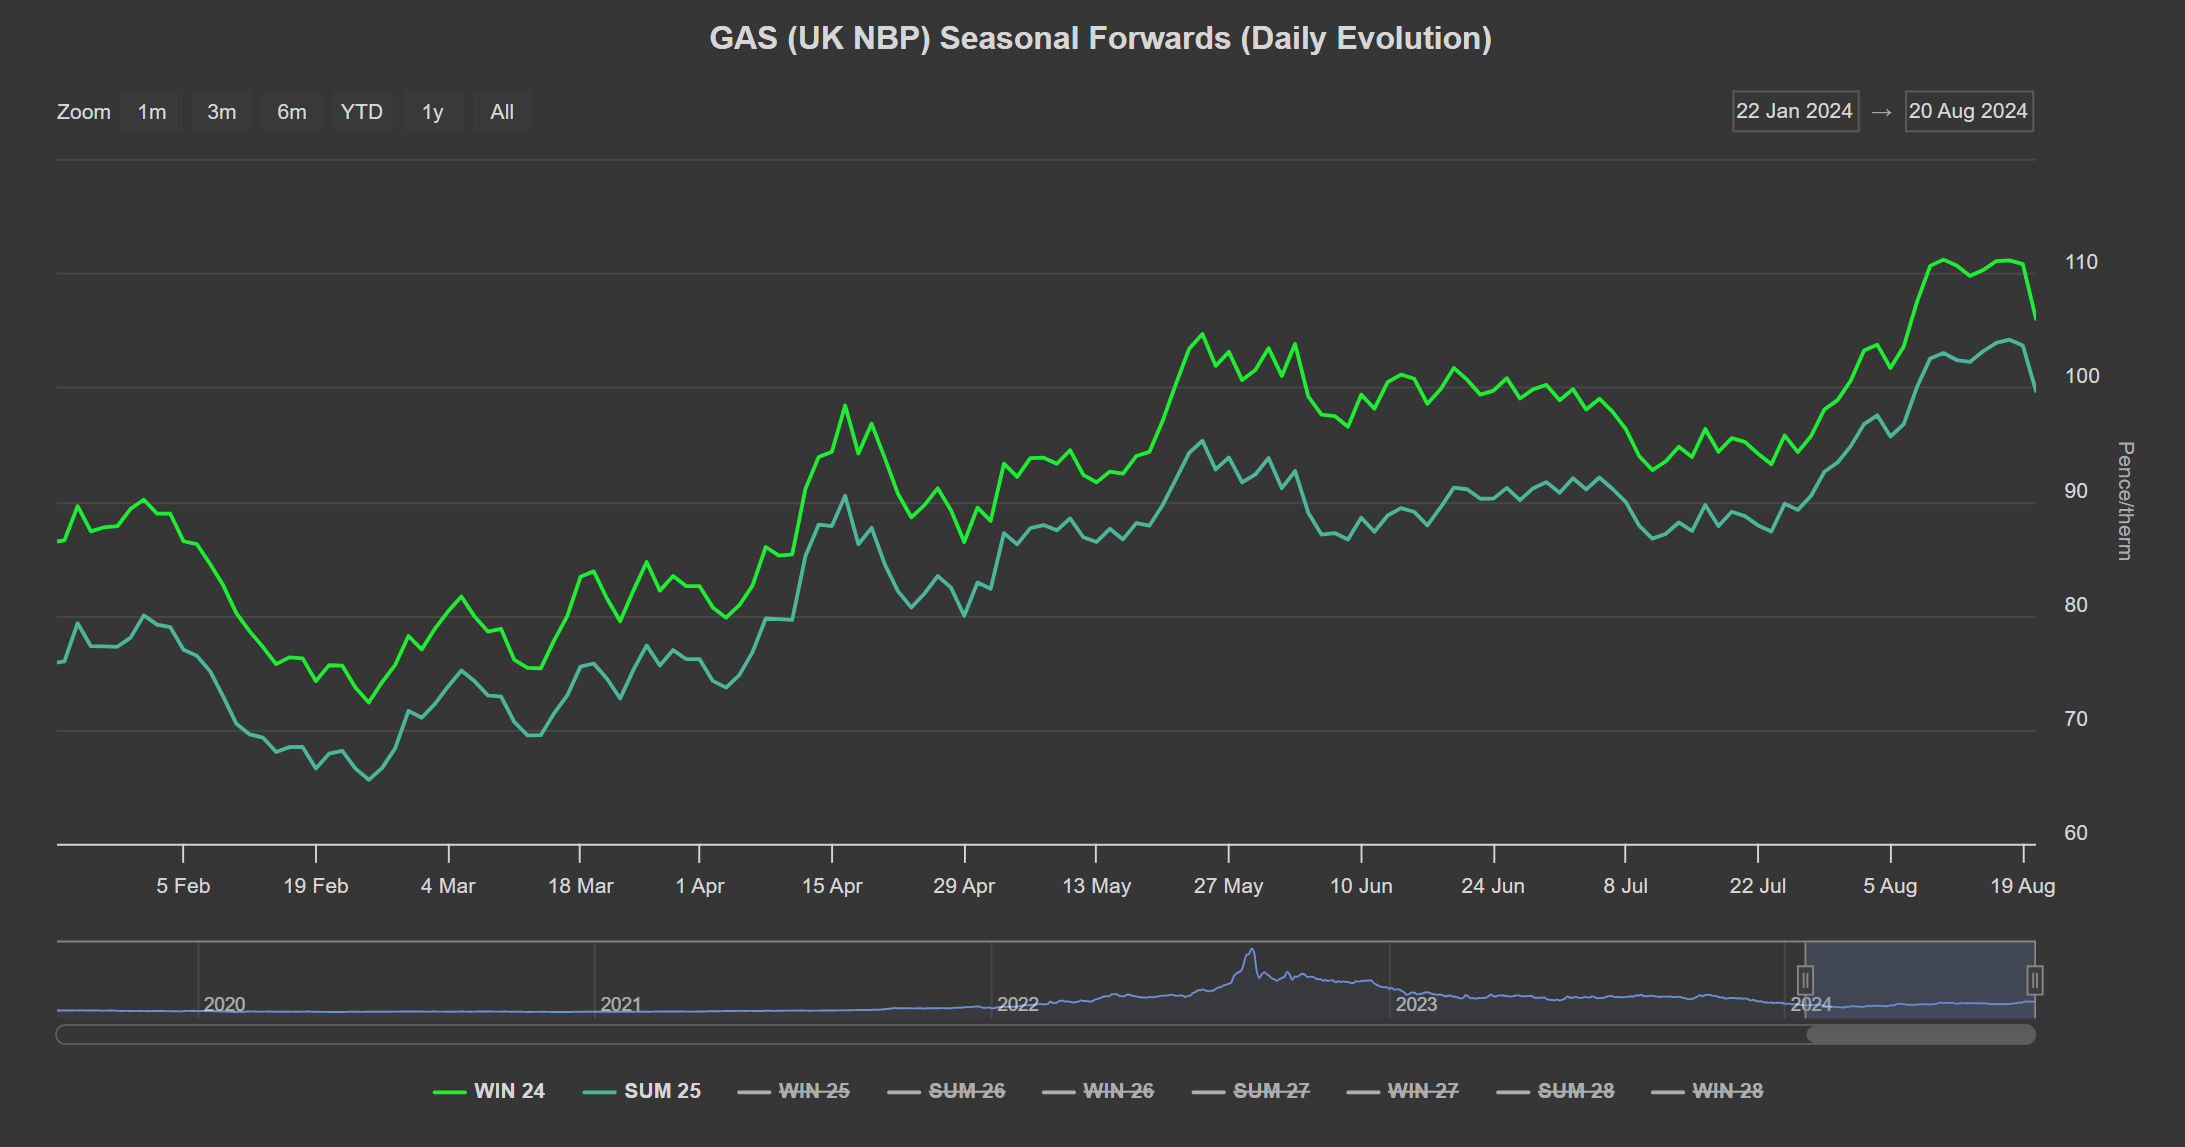
- The Front Seasons (Winter-24/Summer-25) have rolled-over this week (see chart below) off the back of flows continuing uninterrupted via Sudzha – bringing a degree of calm to energy markets following the bullish impacts of Ukraine’s incursion into Russian territory.
- The front of the curve has closed this afternoon approximately 10p/therm lower than the intraday highs we saw back on 12th Aug.
- Storage levels at the upper extremity of the 5-year range continue to limit upside momentum with European MRS (mid-range storage) having already hit the 90% fullness objective a full 2-months before the November target.
- Optimism abounds that a ceasefire of sorts between Israel/Hamas is now a very real prospect which is taking further heat out of the markets.
- Norway’s period of heavy scheduled summer maintenance is nearly upon us, which is likely to limit any meaningful bearish momentum before the onset of Winter-24.
- Lest we forget, notwithstanding recent anxiety over the Sudzha transit point, the transport deal between Russia and Ukraine is to expire at the end of 2024 anyway – will it be extended?
- LNG flows to Northwest Europe are now approx 8% below the 30-day average – reflecting a decline in European demand.
- We’re now also seeing cooling demand drop-off throughout Asia with inventories of LNG falling – if this trend persists, pressure will ease on the JKM/NBP spread, and competition for arrivals will soften.
- European storage is at 90% versus the 5-year average of 79%.
- On the hedging side, we’re now on the other side of Summer-24 – with 143 days having elapsed, and 41 remaining.
- Clients with open volumes for Winter-24 are now very much in the minority – with most having opted to close-out Positions against the backdrop of ongoing geopolitical uncertainties (and with winter conditions now on the horizon).
- Monthly Day-Ahead averages so far this month are on target to achieve 82p/therm (or circa. 2.8p/kwh excluding non-gas).
ELECTRICITY & CARBON
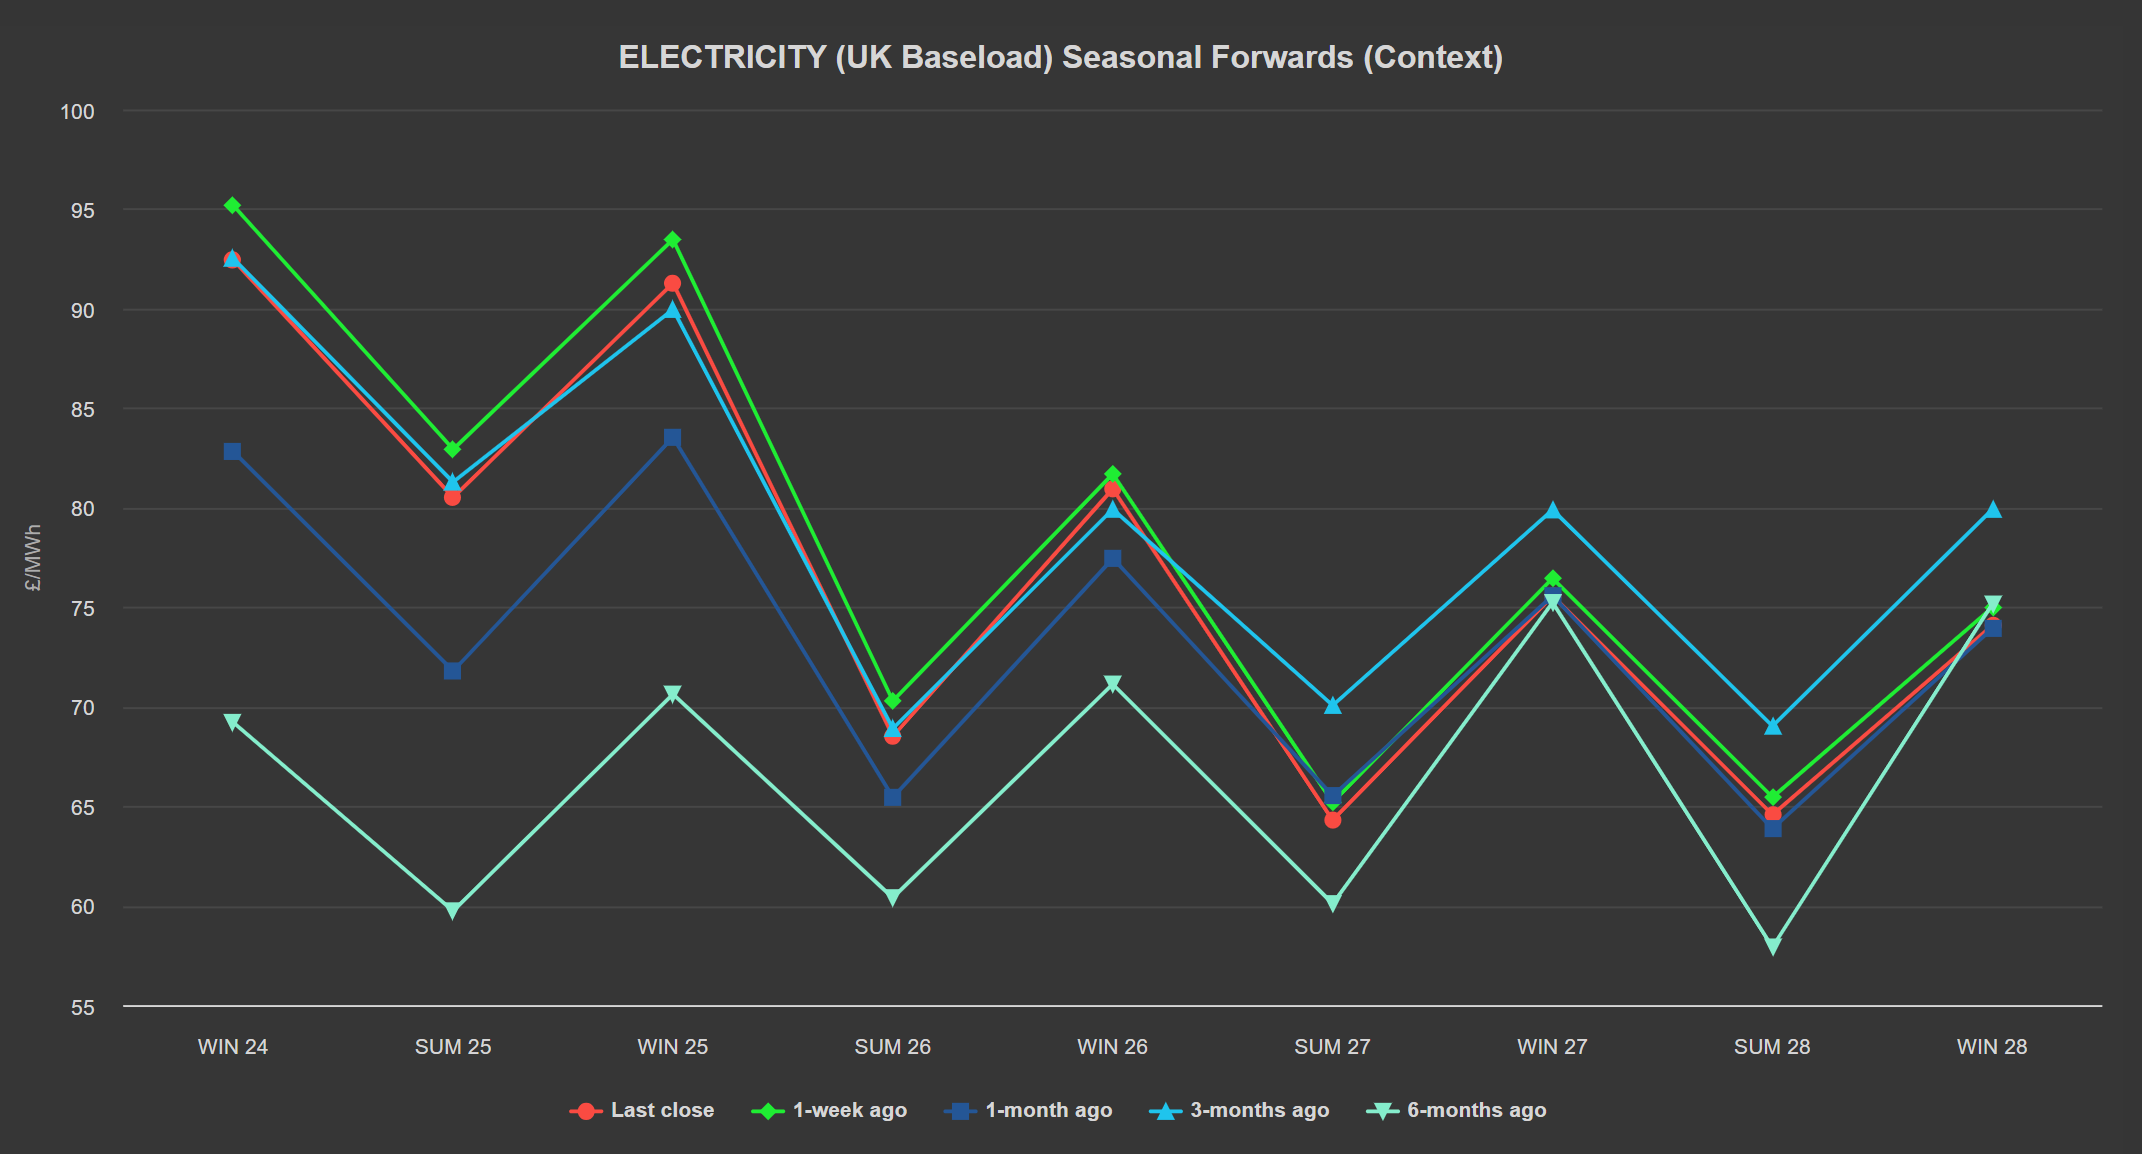
- UK Seasonal Forwards are now commensurate with 1-month ago, and below 1-week ago (see chart below).
- Looking to the continent, Europe’s near-term delivery prices averaged a 37% drop compared to Monday’s values.
- Indeed, intraday negative prices are expected in all European countries during sun hours while the cooling demand remains limited – limiting the evening price spike.
- Forward power prices have declined sharply off the back of easing fuel prices (gas/oil/coal).
- On the Carbon markets, EUA prices remain at a premium to UKAs, with EUAs edging higher.
- UKAs have rallied off last week’s lows (£37.87/tn on 9th august) – now trading back above £40/tn.
- At the time of writing, our electricity generation mix is bearish in nature today with renewables contributing 55%, thermal at 15% (gas and coal) and low carbon at 22% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £60/mwh (or circa. 6.0p/kwh excluding non-energy).