



Fri, 16th Aug ’24
GAS
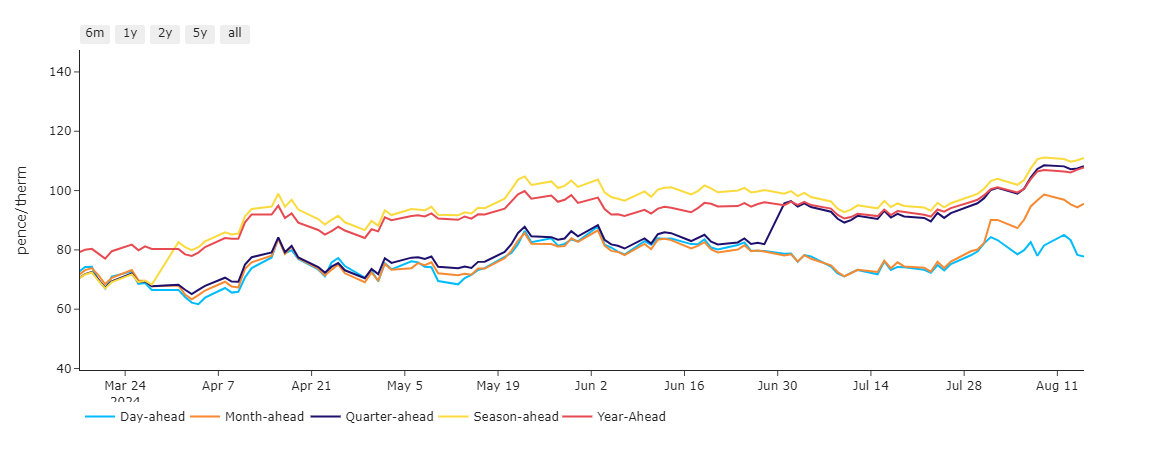
- Day-Ahead holds steady at approx. 80p/therm whilst Month-Ahead has diverged and rallied to hold approx. 95p/therm with Qrtr/Season/Year-Ahead at parity around 110p/therm – see chart below.
- Premium in current markets is primarily derived from risks to supply security – primarily geopolitical uncertainty in Ukraine/Russia (threatening Sudzha transit) and Israel/Iran (threatening Suez Canal LNG transit).
- UK gas prices opened marginally higher in early trading but have dropped off over the course of the morning – it’s sideways price action, but 110p/therm for Winter-24 delivery will need strong bearish momentum to break to the downside.
- The UK continues to export to the continent – a reflection the UK is generating more than demand requires.
- Forecasts of stronger wind generation for the middle of next week will help to reduce gas-for-power demand.
- So, we may see retests of 110p/therm for Winter-24 next week subject to geopolitical developments.
- More Norwegian maintenance is scheduled for the end of August.
- However, at the time of writing, Norwegian flows remain solid at the upper extremity of a 10-year range and above the 5-day moving average – thankfully, limiting upside/bullish momentum.
- European storage is at 88% versus the 5-year average of 78%.
- On the hedging side, we’re now on the other side of Summer-24 – with 138 days having elapsed, and 46 remaining.
- Clients with open volumes for Winter-24 are now in the minority – with most having opted to close-out Positions given the ongoing geopolitical uncertainties and with winter conditions now on the horizon.
- Monthly Day-Ahead averages so far this month are on target to achieve 82p/therm (or circa. 2.8p/kwh excluding non-gas).
ELECTRICITY & CARBON
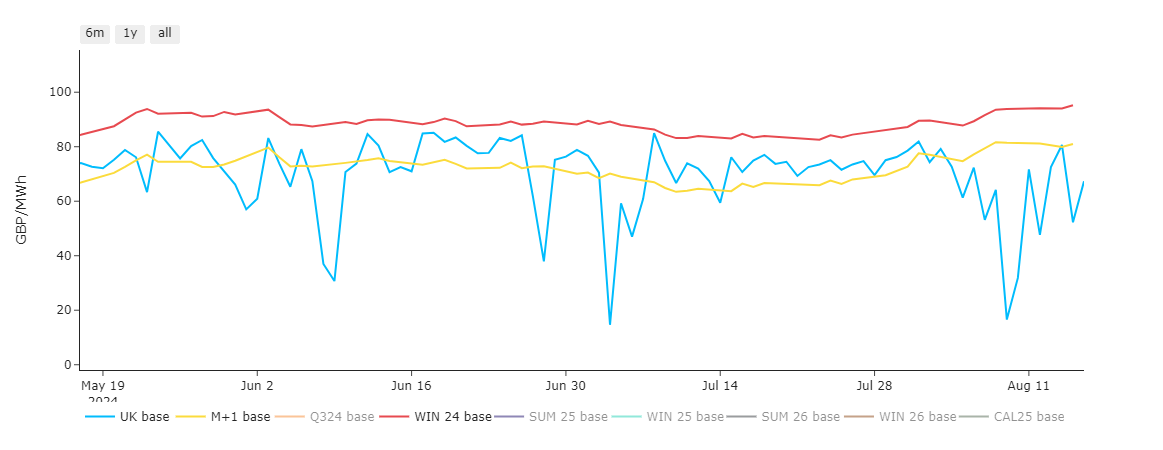
- Day-Ahead prices remain comfortably below Winter-24 delivery, and averaging well-below Month-Ahead – see chart below.
- On the Carbon markets, EUA prices remain at a premium to UKAs, with EUAs edging higher.
- UKAs have rallied off last week’s lows (£37.87/tn on 9th august) – now trading back above £40/tn.
- At the time of writing, our electricity generation mix is neutral in nature today with renewables contributing 46%, thermal at 11% (gas and coal) and low carbon at 31% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £63/mwh (or circa. 6.3p/kwh excluding non-energy).