



Tues, 3rd Jun ’25
GAS
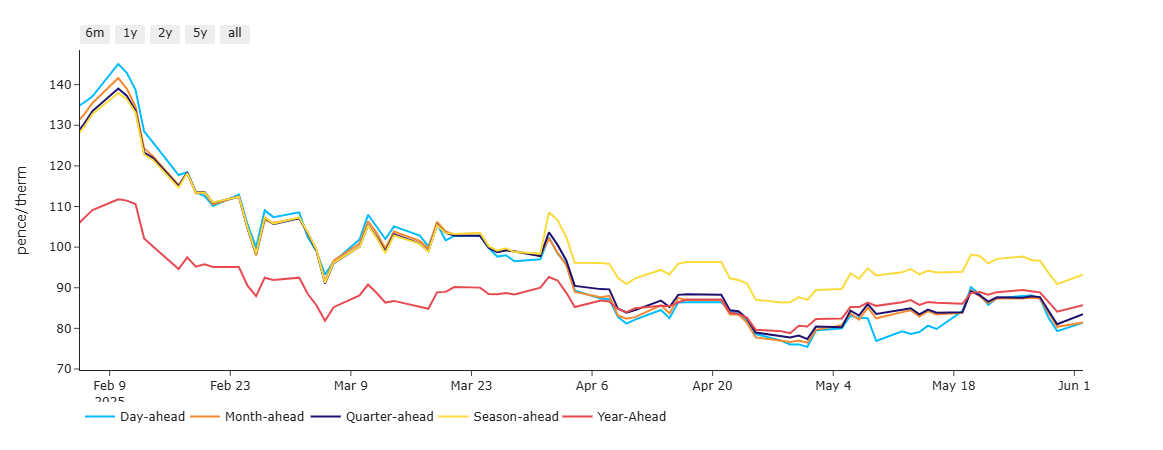
- Noise aside (of which there’s plenty), market movements are what you’d expect for the time of year.
- Near-term delivery prices have continued to soften in keeping with summer conditioning, reflecting lower risk-premium amid increasingly comfortable fundamentals (low demand, solid supply, lower withdrawals, increasing injections).
- Please see chart below detailing Day-Ahead selling at a premium to all other periods of delivery back in Feb-25, only then to fall to posting a discount to all other periods of delivery beginning Summer-25 (1st Apr).
- Forward prices (for periods of delivery further out) continue to find support against a backdrop of geopolitical impacts (which, in turn of course, influence supply dynamics).
- The traditional summer maintenance season is well underway, with Norwegian flows operating some way below capacity – limiting supply, and putting more pressure on LNG arrivals to Europe.
- 68% of Europe’s LNG imports in April came from the US – however, due to a combination of scheduled/unscheduled outages, US LNG exports to Europe fell in May whilst also increasing slightly to Asia (off the back of marginally increased Asian cooling demand).
- Nonetheless, US LNG netbacks still favour Europe as a more profitable destination for LNG vessels (another reason why prices look destined to remain supported for the rest of summer, to ensure LNG continues to arrive at our shores with a view to achieving sufficent storage in time for the heating season beginning Oct-25).
- Other supportive key drivers include the Ukraine conflict and the US-China trade standoff.
- With yet another round of failed ceasefire talks yesterday (amid ongoing drone attacks from both sides), an end to hostilities seems all too distant – as do the resumption of Russian gas flows.
- Bizarrely, worsening US-China relations would likely be bearish for the wider energy complex – as Chinese demand would invetiably fall amid worsening production outputs, and more LNG would be made available to Europe (at reduced competition) – but for now the standoff is contributing to volatility.
- So, whilst prices have softened significantly versus Feb/Mar-25, we’re reaching a stage in the summer where it’s difficult to see how prices will fall further (despite lower demand and increasing storage levels).
- European storage is now at 48% versus the 5-year average of 56% – so any cause for alarm has surely abated.
- On the trading side, clients running flexible capability are increasingly picking up significant volumes of the attractive Forward Summer prices currently on offer.
- It would seem prudent for buyers to continue to scale-in modest hedges over the coming days/weeks whilst the going is good.
- This month’s UK gas Day-Ahead averages are holding steady at 81p/therm (or approx. 2.8p/kwh excluding non-gas).
ELECTRICITY & CARBON
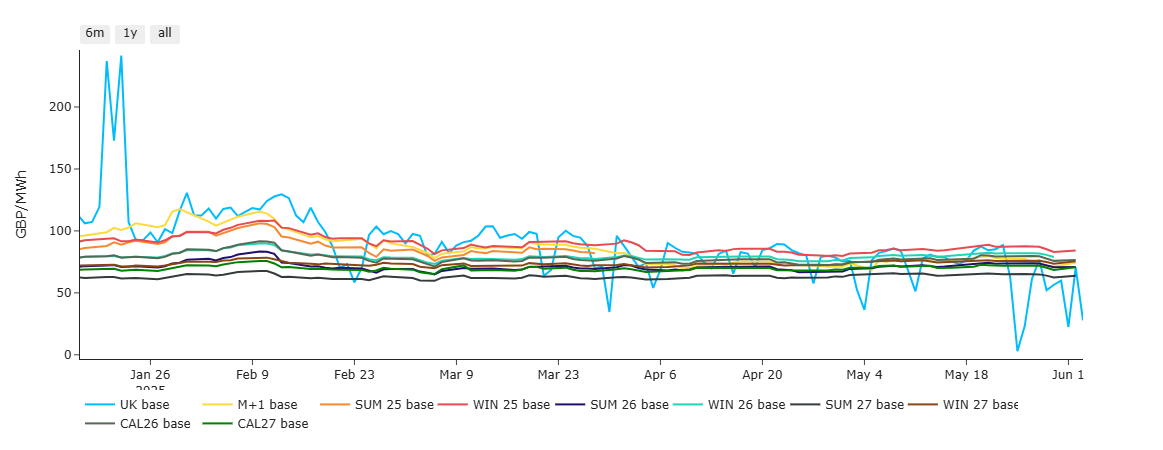
- Mirroring the gas markets, please see chart below detailing electricity Day-Ahead selling at a premium to all other periods of delivery back in Feb-25, only then to fall to posting a discount to all other periods of delivery beginning Summer-25 (1st Apr) – as such, clients floating on the Day-Ahead across the summer months remain in good shape.
- Electricity prices down the curve remain tethered to gas movements.
- Winter-25 is having another go at breaking below £85/mwh at the time of writing (though still someway above the £80/mwh lows printed on 1st May).
- On the Carbon side of things, markets are flat and consolidating in a tight range just above £50/tn on the mid-price.
- Today’s UK electricity generation mix is very bearish (and ‘summery’) in nature reflecting warm and windy conditions – specifically, renewables are contributing 66%, thermal at 11% (gas and coal) and low carbon at 20% (nuclear and imports).
- So far this month, electricity Day-Ahead averages have dropped off due to a reduction in gas-for-power burn over the last week or so – currently very low at £39/mwh (or approx. 3.9p/kwh excluding non-energy).
- On the trading side, clients running flexible capability are encouraged to scale-in modest hedges over the coming days/weeks whilst markets still offer solid comparative value.