



Mon, 9th Jun ’25
GAS
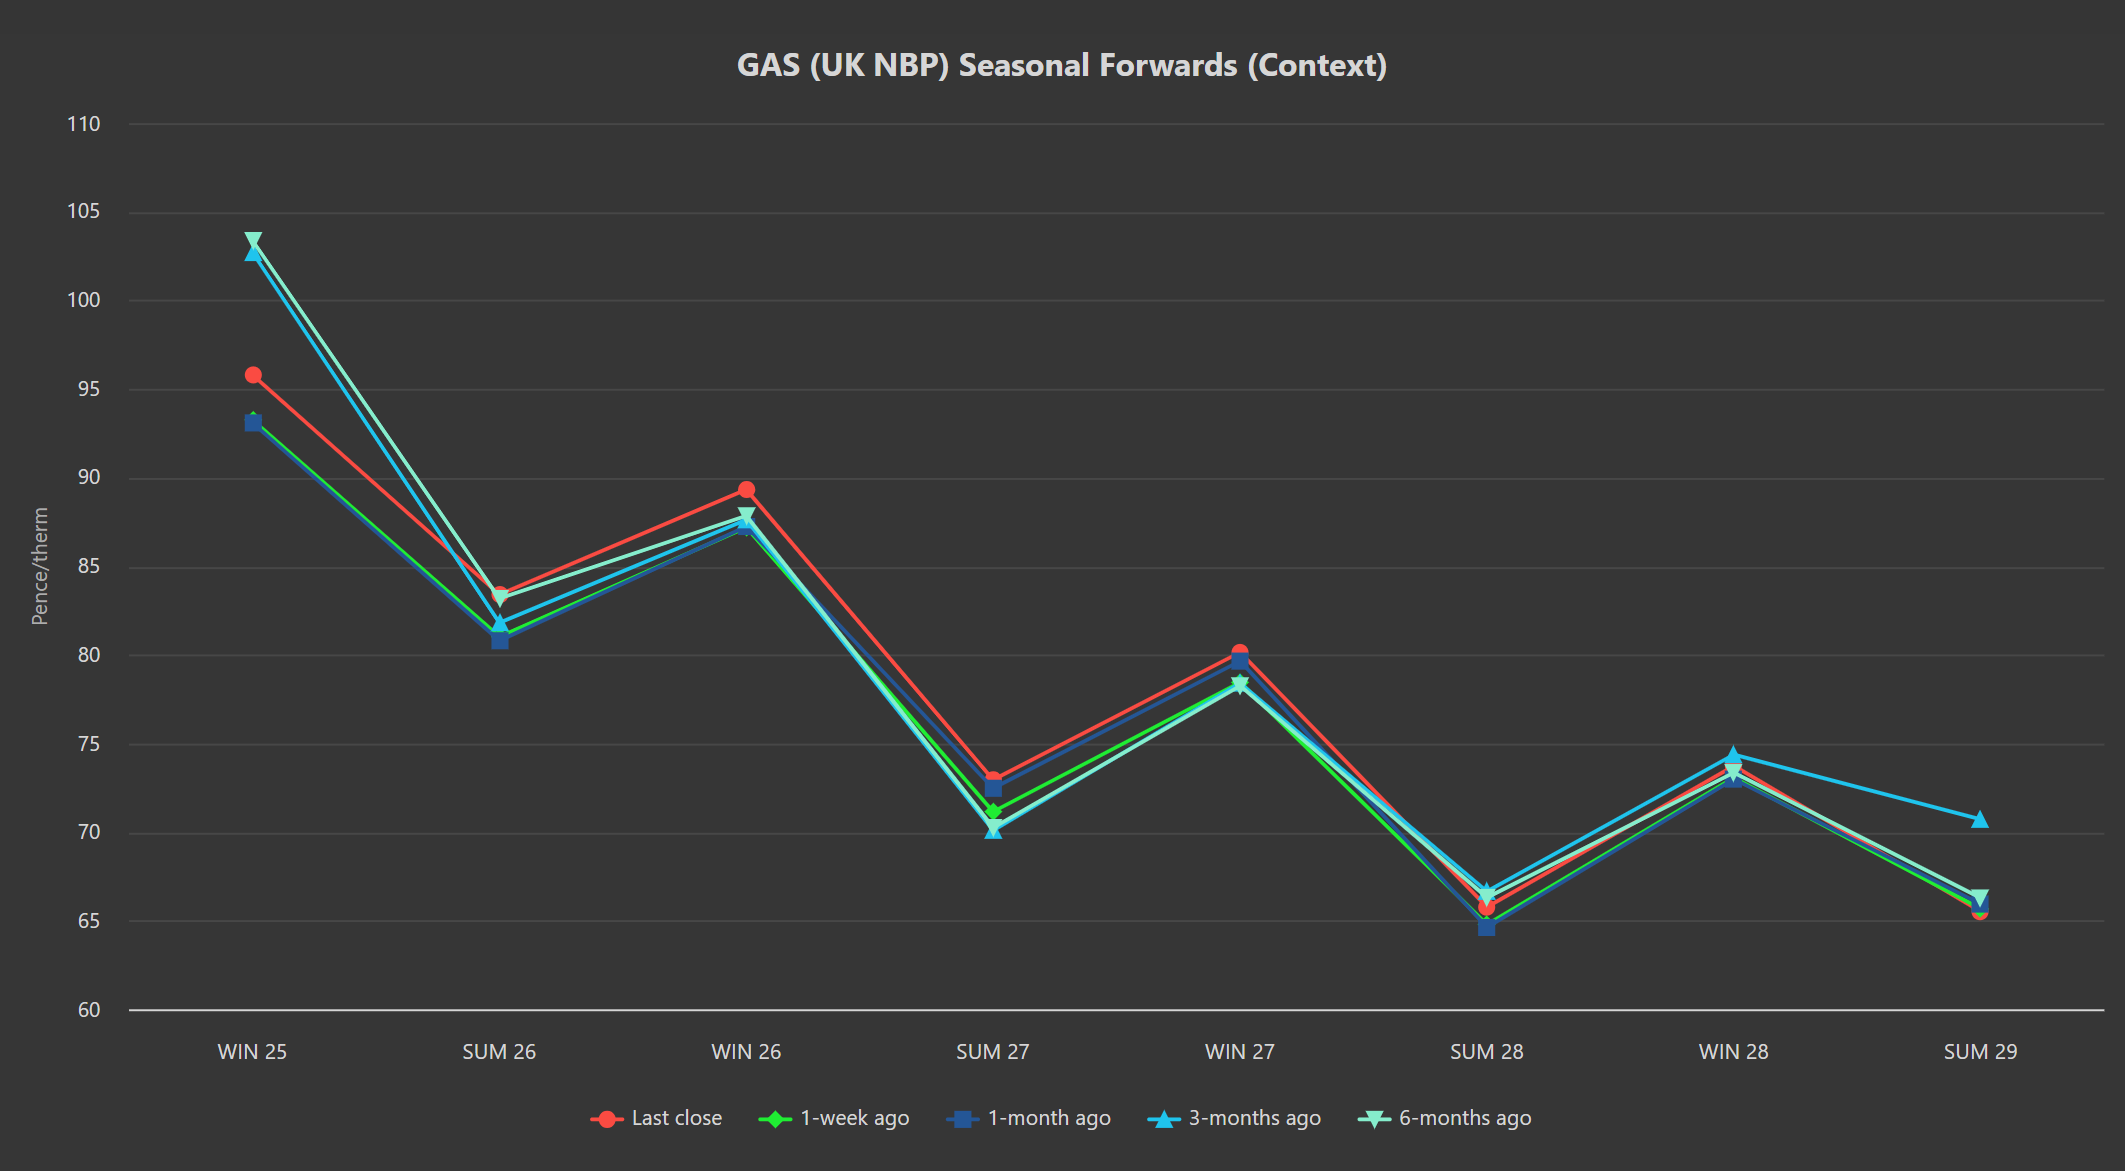
- Seasonal Forwards have been trading in a tight range since early April-25 (the onset of Summer-25).
- Winter-25 delivery fell below 100p/therm on 4th Apr ’25 – thereafter, prices have traded within a 10% range.
- As the chart below further illustrates, Seasonal Forwards have operated within a 10% range as far back as 6-months ago.
- As such, it’s fair to assert that prices have found an equilibrium – supported by geopolitical and associated supply risks; pressured by benign weather conditions and a quiet optimism amongst market participants that storage replenishment (in time for the winter heating season) is on track.
- So, from a buyer’s POV, why is it that markets remain backwardated? i.e., periods of delivery further down the curve are at a discount to periods of delivery in the nearer term?
- Well, market participants evidently believe that prices are set to fall as the years unfold.
- But how can that be (given markets still seem so unsettled)?
- In short, it all comes down to good old-fashioned supply/demand dynamics.
- If we look back to the start of 2025, weakness in Chinese LNG demand coupled with Plaquemines LNG in the US coming online significantly calmed the supply outlook for Europe/the UK.
- Nonetheless, with all known variables considered, it looks likely we’ll only just manage to replenish European stocks to the required level in time for Winter-25 – so that very narrow margin for error is propping up front-season prices.
- Not to mention all the potential banana-skins that lie in wait for us in the coming months – US hurricanes, liquefaction outages, Norwegian maintenance drifts, heatwaves and the associated cooling demand rush for LNG arrivals across Asia.
- In addition, the possibility of the resumption of Russian flows into Europe now looks dead in the water (both LNG and pipeline) – amid fading hopes for a quick peace deal in Ukraine and Europe’s determination to step-up sanctions against Russian energy.
- However, when we look a little further out, global LNG outputs are forecast to double throughout 2026 (made possible by capacity additions from the US, Qatar, Canada, Western Africa and Mexico) – this will drive an increase in European/UK LNG imports (further mitigating winter storage risks).
- As such, cumulative volumes from new LNG projects look likely to tip the global gas market into a glut/oversupply come 2028/2029 – notwithstanding further disruptive golbal conflict between now and then.
- Given the solid comparative value being offered for delivery further down the curve (beginning Summer-27), buyers are encouraged to scale-in Forward hedges so as to build a budget of secured step-down prices y-o-y.
- Back to this week (and short-term risk), Norwegian outages (both scheduled and unscheduled) will feature in the coming days forcing significant pipeline volumes offline (tightening supply, adding price support).
- Though bullish fervour should be tempered by an improving weather outlook with Europe as a whole enjoying temperatures well above seasonal norms before the weekend.
- European storage fullness continues to resemble 2022’s trend – currently at 51% versus the 5-year average of 58%.
- The consensus amongst analysts now expects storage to achieve around 87% by the time Winter-25 kicks-in (hopefully making it more difficult for the alarmists to spike the market higher for no discernible reason over the coming months).
- This morning, markets are softer than Friday’s closing prices off the back of a long system (supply outstripping demand forecast).
- On the trading side, clients running flexible capability are increasingly picking up significant volumes of the attractive Forward Summer prices currently on offer.
- It would seem prudent for buyers to continue to scale-in modest hedges over the coming days/weeks whilst the going is good.
- This month’s UK gas Day-Ahead averages are holding steady at 84p/therm (or approx. 2.9p/kwh excluding non-gas).
ELECTRICITY & CARBON
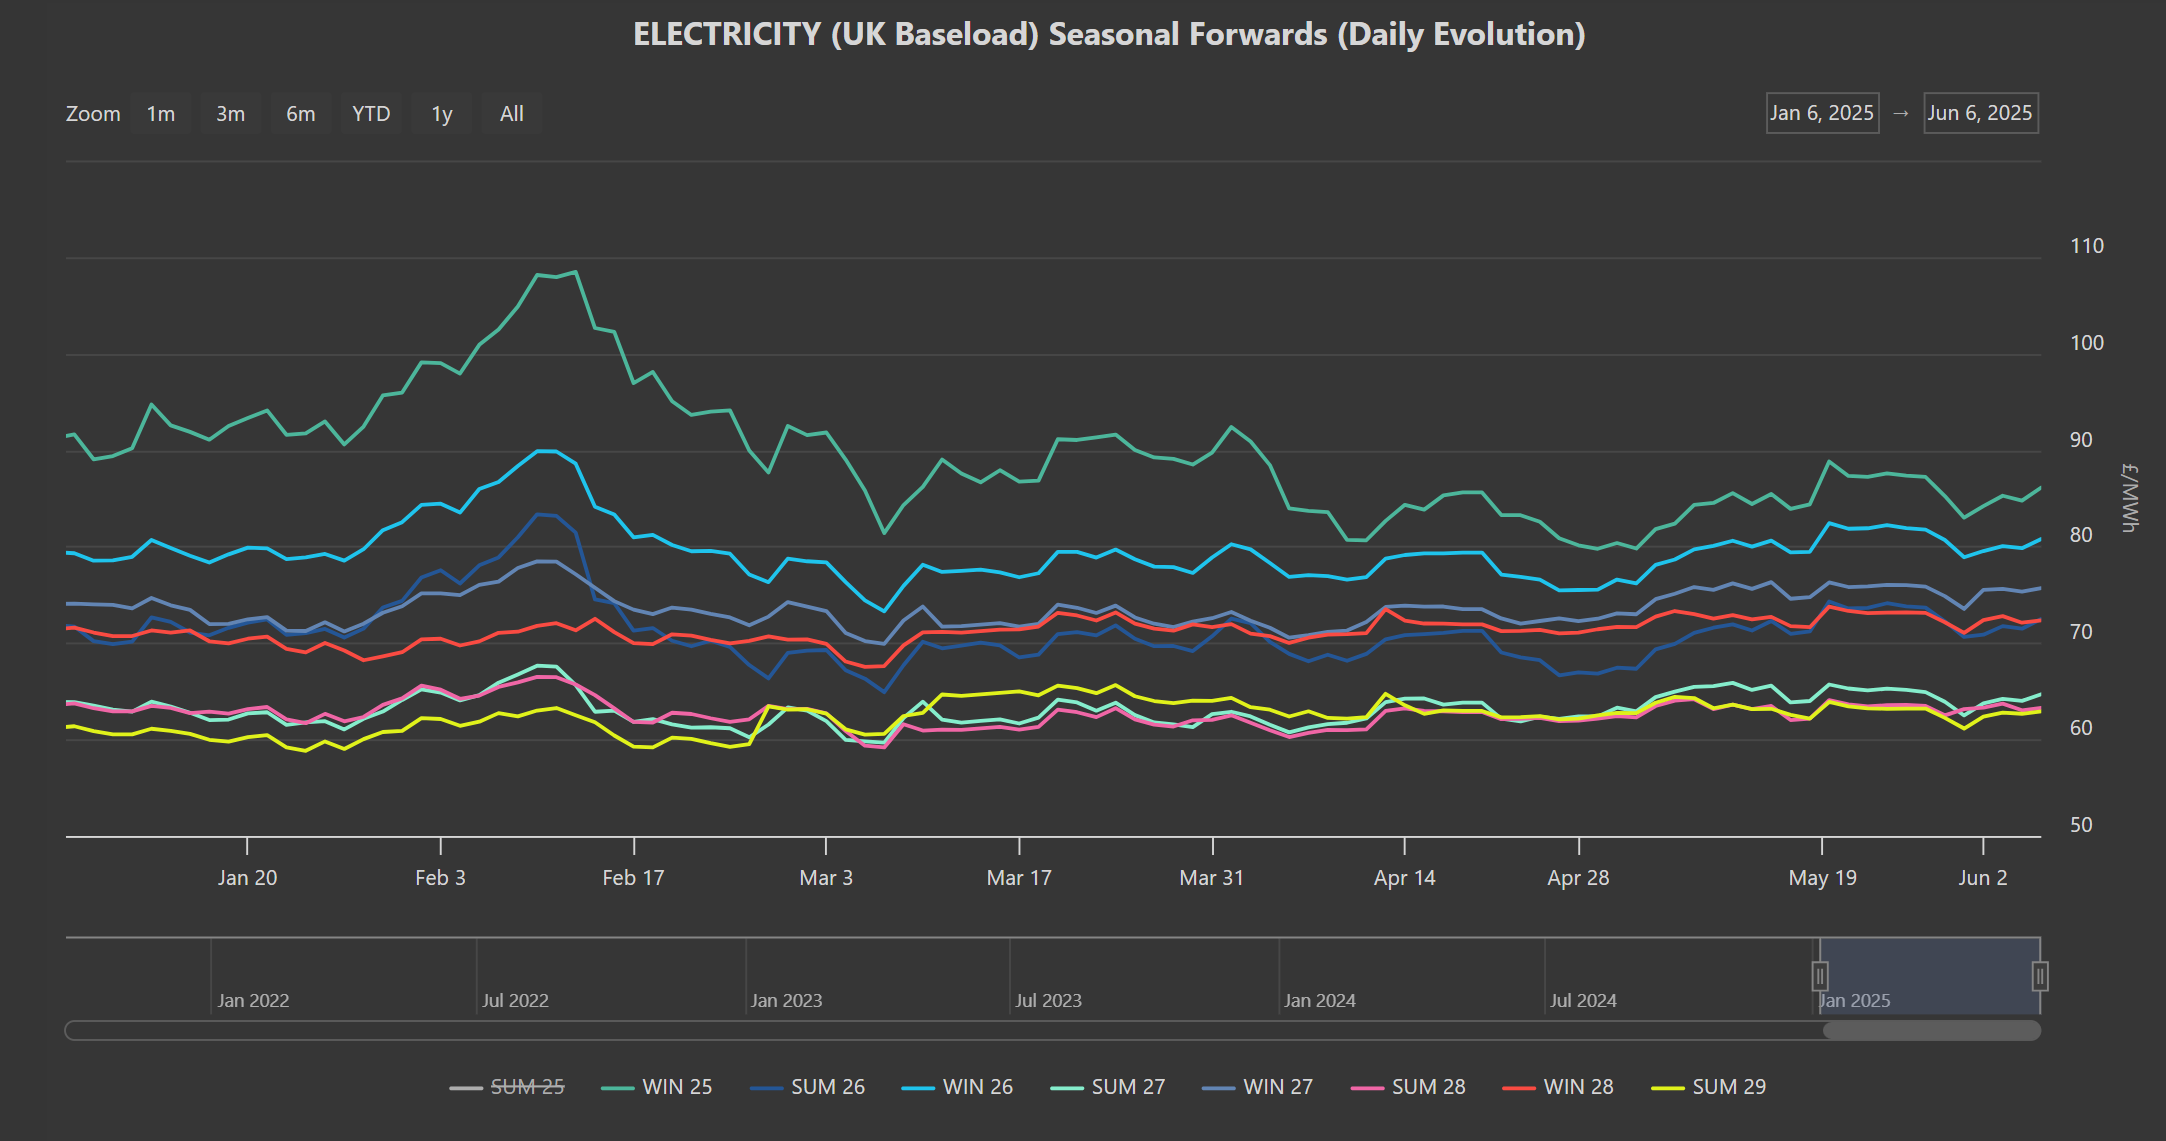
- Electricity prices remain closely correlated to gas movements – so, in the main, it’s sideways price action.
- Further to the falls in price seen in Feb/Mar ’25, Seasonal Forwards are trading in a tight consolidation (please see chart below).
- Today’s public holiday in the majority of EU states is likely to mean illiquid trading conditions (and so not a good day to hedge given the risk of wider bid/offer spreads).
- On the Carbon side of things, markets are flat and consolidating in a tight range just above £50/tn on the mid-price.
- Today’s UK electricity generation mix is nutral to bearish in nature reflecting essentially benign weather conditions – specifically, renewables are contributing 34%, thermal at 25% (gas and coal) and low carbon at 22% (nuclear and imports).
- So far this month, electricity Day-Ahead averages are low and reflect summer-demand – currently at £62/mwh (or approx. 6.2p/kwh excluding non-energy).
- On the trading side, clients running flexible capability are encouraged to scale-in modest hedges over the coming days/weeks whilst markets still offer solid comparative value.