



Tues, 20th Feb ’24
GAS
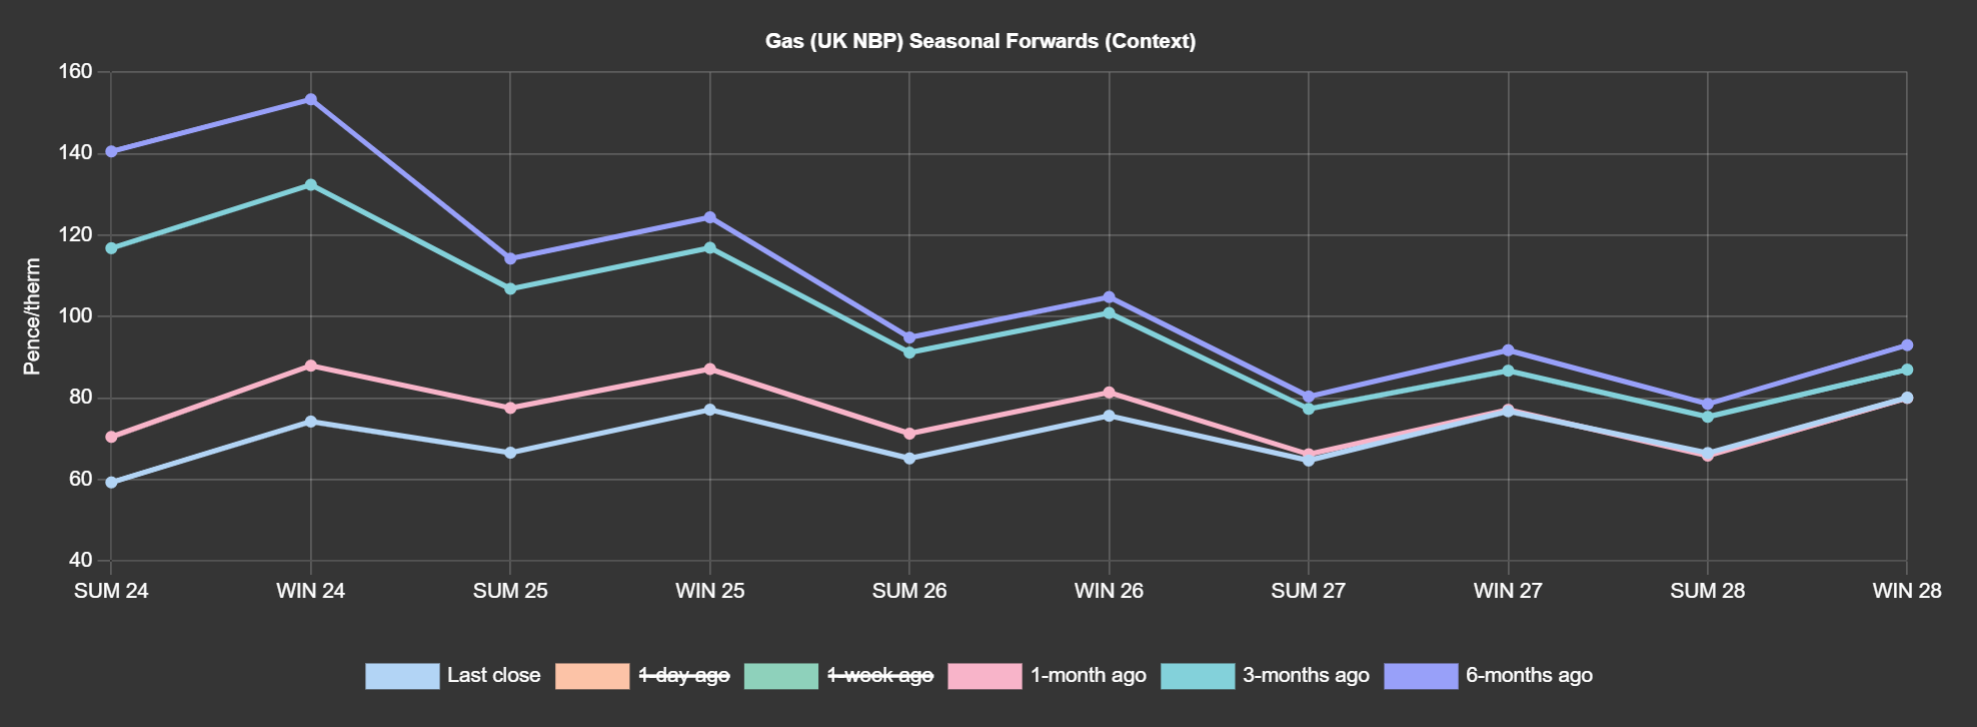
- Summer-24 delivery is now at a 58% discount versus 6-months ago! (see chart)
- Near-term delivery prices continue to soften amid overwhelmingly bearish fundamentals.
- Day-Ahead fell as low as 55p/therm yesterday – its lowest level since 1 November 2022.
- Notwithstanding any unforeseen geo-political impacts, expect more of the same this week before residential heating demand picks up due to colder temperatures by the weekend.
- Until then, the UK’s Day-Ahead discount versus TTF (Europe’s benchmark gas exchange) is likely to remain wide enough to continue incentivizing IUK (interconnector) exports to the Continent.
- Ample supply and historically high storage makes any potential upside risk to near-term delivery prices limited.
- In short, the bear-trend that began in Q422 is still in place.
- With Summer-24 only 40 days away, only geo-political unrest poses any risk to a continuation of the prevailing bear trend.
- Monthly Day-Ahead averages are on target this month (so far) to achieve 65p/therm (or circa. 2.2p/kwh).
ELECTRICITY & CARBON ALLOWANCES
- Looking to the continent, demand should remain contained over the next week as temperatures remain above long-term averages across Europe.
- Thereafter, temperatures fall toward the end of the month and into early March potentially triggering a late rebound of winter demand before Summer-24 officially begins on 1st April.
- On the supply side, strong wind outputs are forecast by Thursday of this week – limiting gas-for-power generation.
- However, this wind event will quickly fade, and lower outputs are expected for the weekend and early next week.
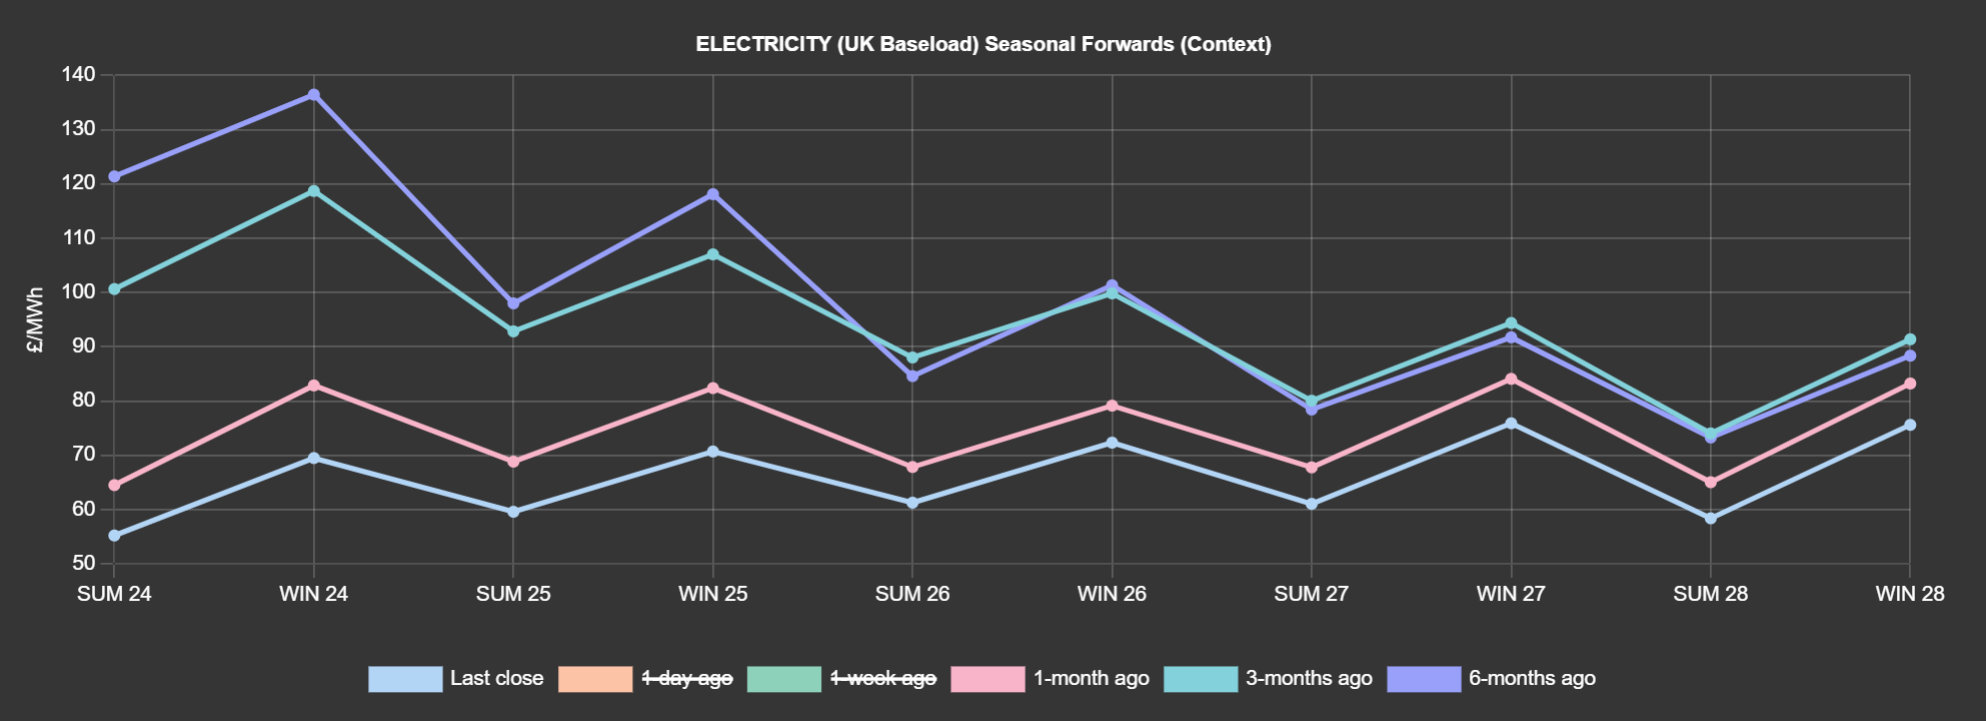
- Down the curve, prices extend their slide, tracking falls in the fuel basket, primarily driven by falling carbon values.
- EUAs have fallen to a 2-year low reaching €52.90/tonne before closing at €53.54/tonne.
- UKAs followed suit dropping to £33/tonne, looking likely to test the lows of late Jan ’24 (£30/tonne).
- These drops in UK/European carbon are being driven by warm weather (limiting thermal generation) and low gas to coal switching potential (due to declining gas forward prices).
- Back in the UK, our generation mix is bearish with renewables contributing 46% and gas-for-power burn at 23%.
- Monthly Day-Ahead averages for UK electricity are on target this month (so far) to achieve £60/mwh (or 6p/kwh).