



Thurs, 22nd Feb ’24
GAS
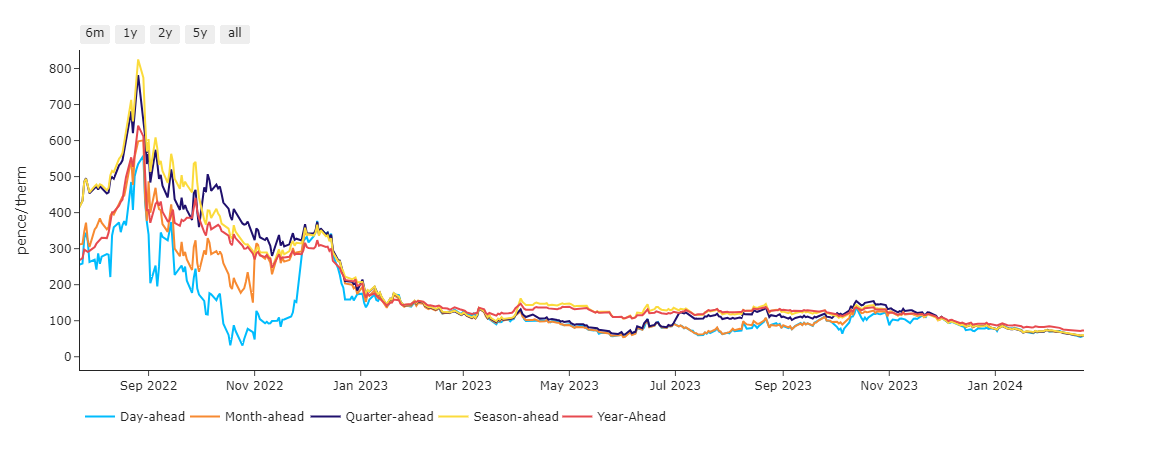
- Bias remains neutral to bearish, with volatility almost flat compared to the chaos of 2022 (see chart).
- Temperatures remain above seasonal norms amid decent wind outputs (limiting gas-for-power burn).
- Down the curve, Forward contracts are meandering on decent volume but with little discernible direction!
- European gas fullness is at 65% versus 5-year average of 45%.
- On the supply side, Norwegian flows are at steady capacity despite extended unscheduled outages.
- Ample supply and historically high storage makes any potential upside risk to near-term delivery prices limited.
- In short, the bear-trend that began in Q422 is still in place.
- With Summer-24 only 38 days away, only geo-political unrest poses any risk to a continuation of the prevailing bear trend.
- Monthly Day-Ahead averages are on target this month (so far) to achieve 65p/therm (or circa. 2.2p/kwh).
ELECTRICITY & CARBON ALLOWANCES
- Looking to the continent, the fundamental situation is bearish until the evening and likely marginally bullish thereafter.
- Demand is dropping on the weekly cycle.
- Wind supply is lifted and solar power generation is climbing (as the days get longer).
- Moderate to high winds are expected to persist across Europe for the next 10-days or so.
- On the carbon markets, the weekly COT( Commitments of Traders Report) published yesterday showed marginally lowered speculative interest.
- Prices remain in a narrow trading range, mostly due to the lack of auctions yesterday and support from investment funds.
- Energy fundamentals are relatively weak and unsupportive – as such, carbon may continue to take direction from gas.
- Back in the UK, our generation mix is bearish with renewables contributing 37% and gas-for-power burn at 23%.
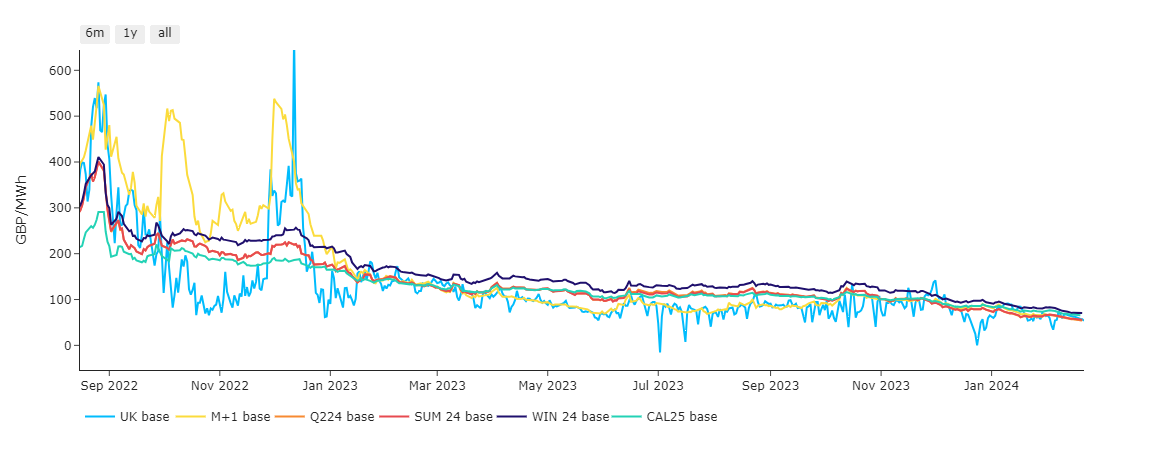
- Monthly Day-Ahead averages for UK electricity are on target this month (so far) to achieve £60/mwh (or 6p/kwh).