



Tues, 18th Jun ’24
GAS
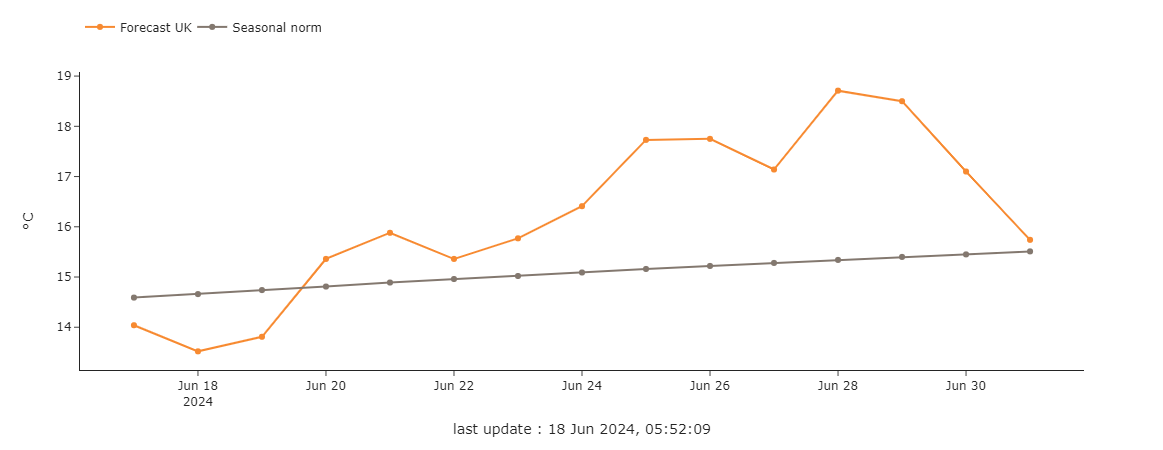
- Markets have dropped off last week’s mini bull-rally, and temperatures next week are forecast to rise above seasonal norms (see chart).
- The LNG outlook is also marginally improved – weirdly, Russia has overtaken the US as Europe’s leading gas supplier (notwithstanding several EU nations lobbying for sanctions).
- Following Russia’s invasion of Ukraine back in Feb ’22, Europe became significantly dependent on US LNG, which then supplied 20% of the region in 2023.
- According to the most recent figures, LNG from the US has now fallen to 14% of Europe’s overall supply, whilst Russian exports (gas and LNG) made up 15%.
- W-o-w, global LNG supply is little changed.
- Notably however, we’ve seen a 15% weekly increase of LNG cargoes at sea for 20 days or longer – due primarily to vessels being forced to navigate around the Cape of Good Hope to avoid Houthi rebels in the Red Sea area.
- Whilst India LNG imports remain at historic highs, China LNG imports thankfully slowed significantly compared to May – mitigating global supply tightness (and keeping a lid on the commodity price).
- Back in the UK, our system was long at this morning’s open (supply outstripping demand forecast).
- Supply/demand dynamics are stable with exports to Europe reducing d-o-d.
- We’re 79 days into Summer-24 (105 days remaining).
- Fundamental drivers have softened from last week allowing for decent storage injections.
- Norwegian flows are increasingly stable, and the single-day maintenance at Skarv today should see flows rise again tomorrow.
- Overall, bullish drivers look weak, and as long as the geo-political landscape remains “quiet” (!), the trajectory will be one of sideways/bearish price action.
ELECTRICITY & CARBON
- Looking to the continent, European near-term delivery prices remained at equilibrium yesterday with prospects of soaring French nuclear availability and hydro generation at odds with forecasts of weakening wind output.
- Down the curve, prices dropped sharply to start the week – pressured by weaker EUAs (European Carbon Allowances) and falling gas prices against a backdrop of steady Norwegian gas flows and slowing LNG imports into Asia.
- But again (as has been the case for weeks now), the benchmark TTF month-ahead contract (European gas) appeared to find support at its 1-year moving average, potentially indicating market caution in committing to a more meaningful retracement (or trend reversal).
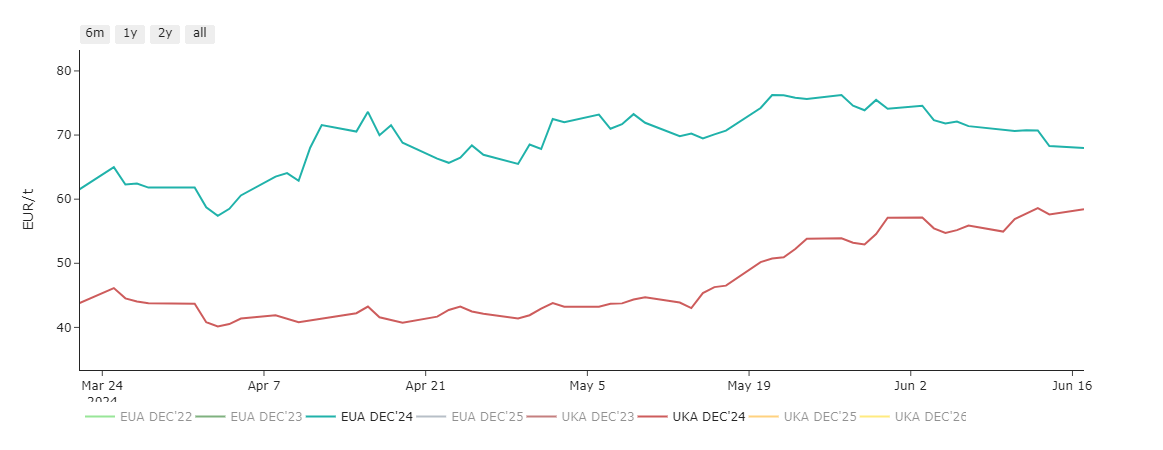
- On the Carbon markets, the EAU downtrend took a breather yesterday – though with UKAs (UK Allowances) still drifting northwards headed seemingly to test £50/tonne, the two markets grow ever closer to parity (see chart).
- Our electricity generation mix is neutral in nature today with renewables contributing 27%, thermal at 31% (gas and coal) and low carbon at 29% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £69/mwh (or 6.9p/kwh excluding non-energy).