



Fri, 14th Jun ’24
GAS
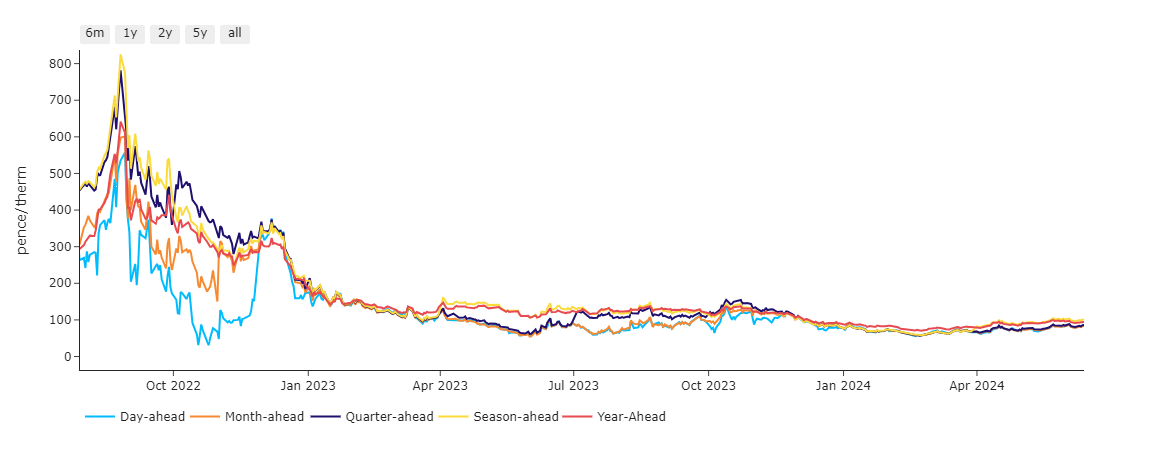
- It’s been another week of sideways price action – with Seasonal Forwards barely altered versus 1-week ago.
- Looking at the bigger picture, market volatility for near-term delivery remains relatively flat versus the chaos of ’21/’22/’23 – see chart.
- Any bullish momentum has been driven by fears of supply tightness further to the unscheduled, ongoing maintenance at Wheatstone LNG terminal in Australia – it’ll be weeks before the site comes back online.
- This perceived tightness is coupled with high temperatures across Asia (and the associated high cooling demand) – prices are higher in Asia, so that’s where cargos are headed.
- Whilst Europe has gone a long way toward diversifying gas supply since Russia invaded Ukraine, risks persist.
- As we’ve seen recently with Freeport in Texas, and now with Australian LNG fields, Europe is being forced to compete with Asia (China) – this competition will always be price supportive.
- Though as outlined in recent reports, if gas prices go too high, Asia will likely turn to coal – so the price support has its limits.
- The UK system was long this morning (supply outstripping demand forecast), notwithstanding temperatures below seasonal norms (sustaining LDZ, or heating demand).
- Prices have softened to end the week despite confirmation that maintenance at both the Barrow North terminal (UK) and the the Visund gas plant (Norway) is to be extended.
- As we head deeper into summer conditioning, demand is on a downwards trend and will gradually loosen the UK balance – allowing storage injections.
- Whilst it’s conceivable we’ve already seen the bottom of summer pricing, it’s not panic stations just yet.
- The consensus amongst Industrials continues to be one of scaling-in whilst adopting a wait-and-see approach to any remaining open volumes for Winter-24/winter-25.
- 109 days of Summer-24 remain (with 75 days now used up) – so a significant chunk of Summer-24 is still ahead of us.
- Europe remains on track to achieve 100% storage levels by Winter-24 (early Oct ’24).
- Monthly Day-Ahead averages are on target this month to achieve 83p/therm (or approx. 2.8p/kwh excluding non-gas).
ELECTRICITY & CARBON
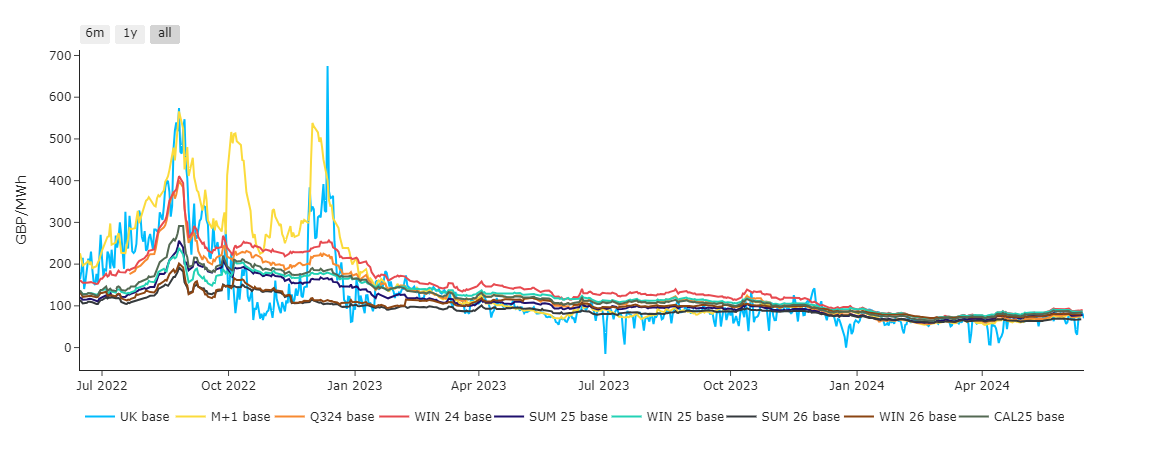
- Looking to the continent, European near-term delivery prices dropped off yesterday, pressured by prospects of weaker demand and stronger wind outputs.
- Prices are expected to fall further this weekend off the back of sustained renewables generation.
- On the European Carbon markets (EUAs) , it’s been the same pattern all week – up in the morning to mirror gas prices, then losing steam toward the end of the session.
- Back in the UK, UKAs (UK Allowances) are treading water – now trading at approx. £48/tn (Dec-24 benchmark) – having failed to break above the upper extremity of the confirmed price channel, with momentum indicators in overbought territory and rolling over.
- Our electricity generation mix is bearish in nature today with renewables contributing 39%, thermal at 19% (gas and coal) and low carbon at 27% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £67/mwh (or 6.7p/kwh excluding non-energy).