



Thurs, 13th Mar ’25
GAS
- Geopolitical developments over the last few days coupled with lower temperatures across the UK/Europe have meant both near- and far-term delivery contracts have recovered some of last weeks losses.
- At yesterday’s meeting in Saudi Arabia, the US agreed to resume security support for Ukraine (in return for Kyiv confirming a willingness to accept a ceasefire proposal).
- Unfortunately, Russia’s response today has been to criticise the offer, stating it would give Ukrainian forces a reprieve (just when Putin feels his forces are close to regaining Kursk).
- On the Trump tariff side of things, the EU has responded to to the imposition of 25% tariffs (on European steel and aluminium) with €26bn of ‘countermeasures’ including on such US favourites as bourbon, jeans, and Harley-Davidson motorbikes.
- Thankfully, Europe is not threatening to impose tariffs on imports of US LNG…
- Despite the cold spell, the UK system opened long this morning (supply outstripping demand forecast).
- Nonetheless, heating demand and gas-for-power burn is rising d-o-d in line with temperatures falling.
- On the supply side, Norwegian flows are on the up following Asgard coming back online.
- Withdrawals are ongoing despite very solid LNG send-out – reflecting high demand, poor renewable outputs.
- European storage is at 40% versus the 6-year average of 49%.
- Rumours abound that a resumption of the Ukrainian gas transit agreement is still in the offing (assuming Putin comes to the table over the ceasefire).
- It seems unthinkable that Putin will resist Trump’s efforts to broker a peace deal in the long-term – otherwise, Trump will be left with egg on his face and Putin’s opportunity to exit the mess (that is the Ukraine invasion) will have passed him by.
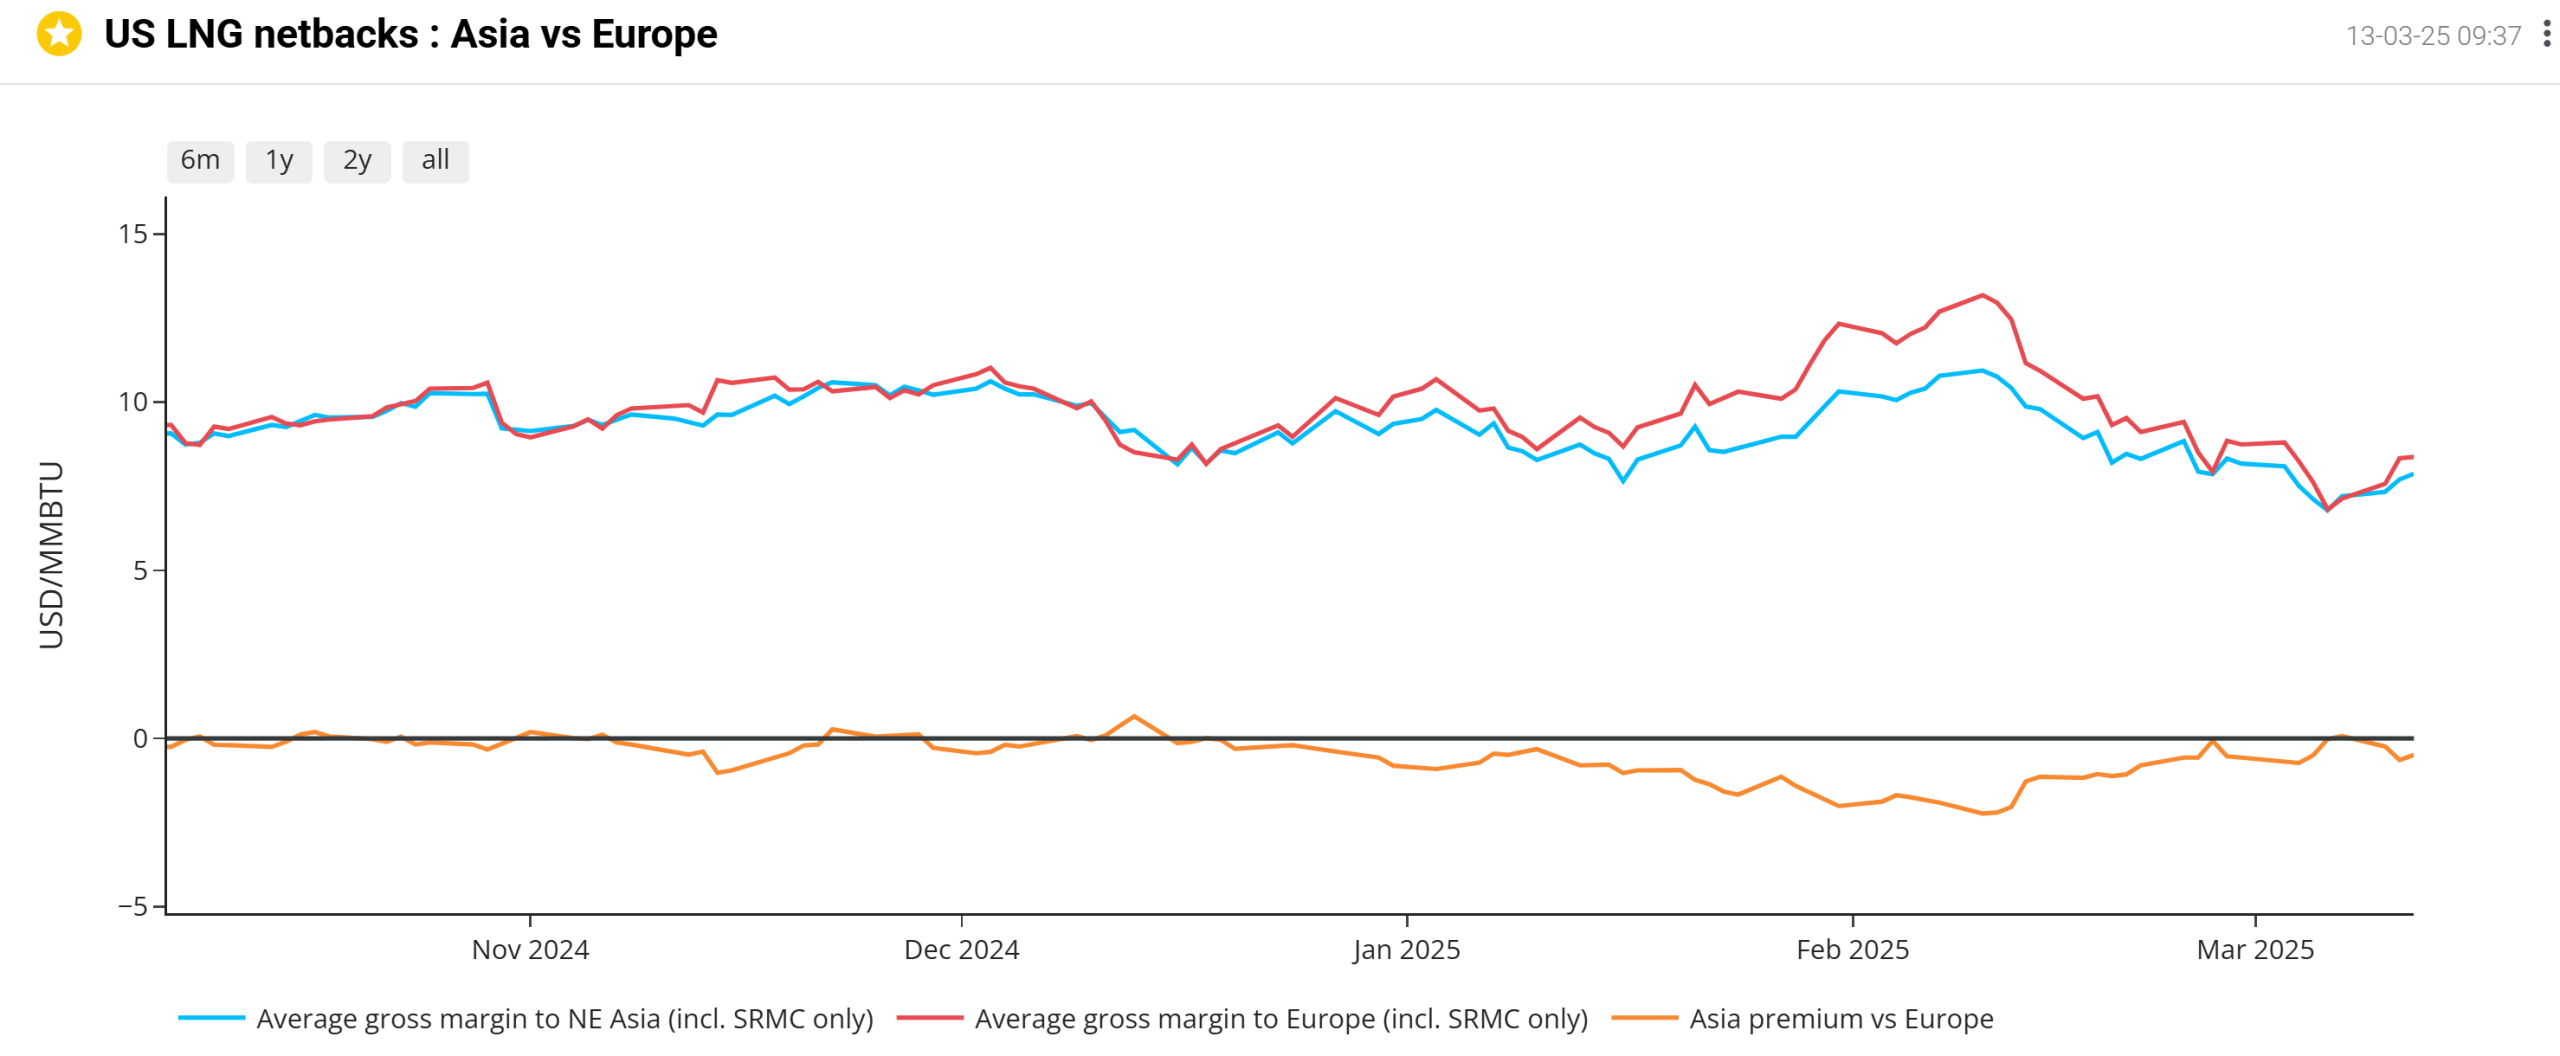
- For US LNG cargoes at least, Europe retains its attractiveness over Asia – please see chart below.
- Monthly Day-Ahead averages for this month so far are on track to improve on last month’s final number (124p/therm), with averages at 103p/therm at the time of writing (or approx. 3.5p/kwh excluding non-gas).
ELECTRICITY & CARBON
- Mirroring gas prices, Seasonal Forwards have risen at the front of the curve, but are relatively unchanged beyond Winter-26.
- On the Carbon markets, prices remain range-bound, caught between geopolitical uncertainties (Trump’s tariffs and Ukraine) — whilst the recent declines (and improved value) may start attracting compliance buyers (driving the market up).
- Nonetheless, speculators still hold a significant long (buy) position, in the belief of course that Carbon MUST rise in the long term if global sustainability goals are to be met.
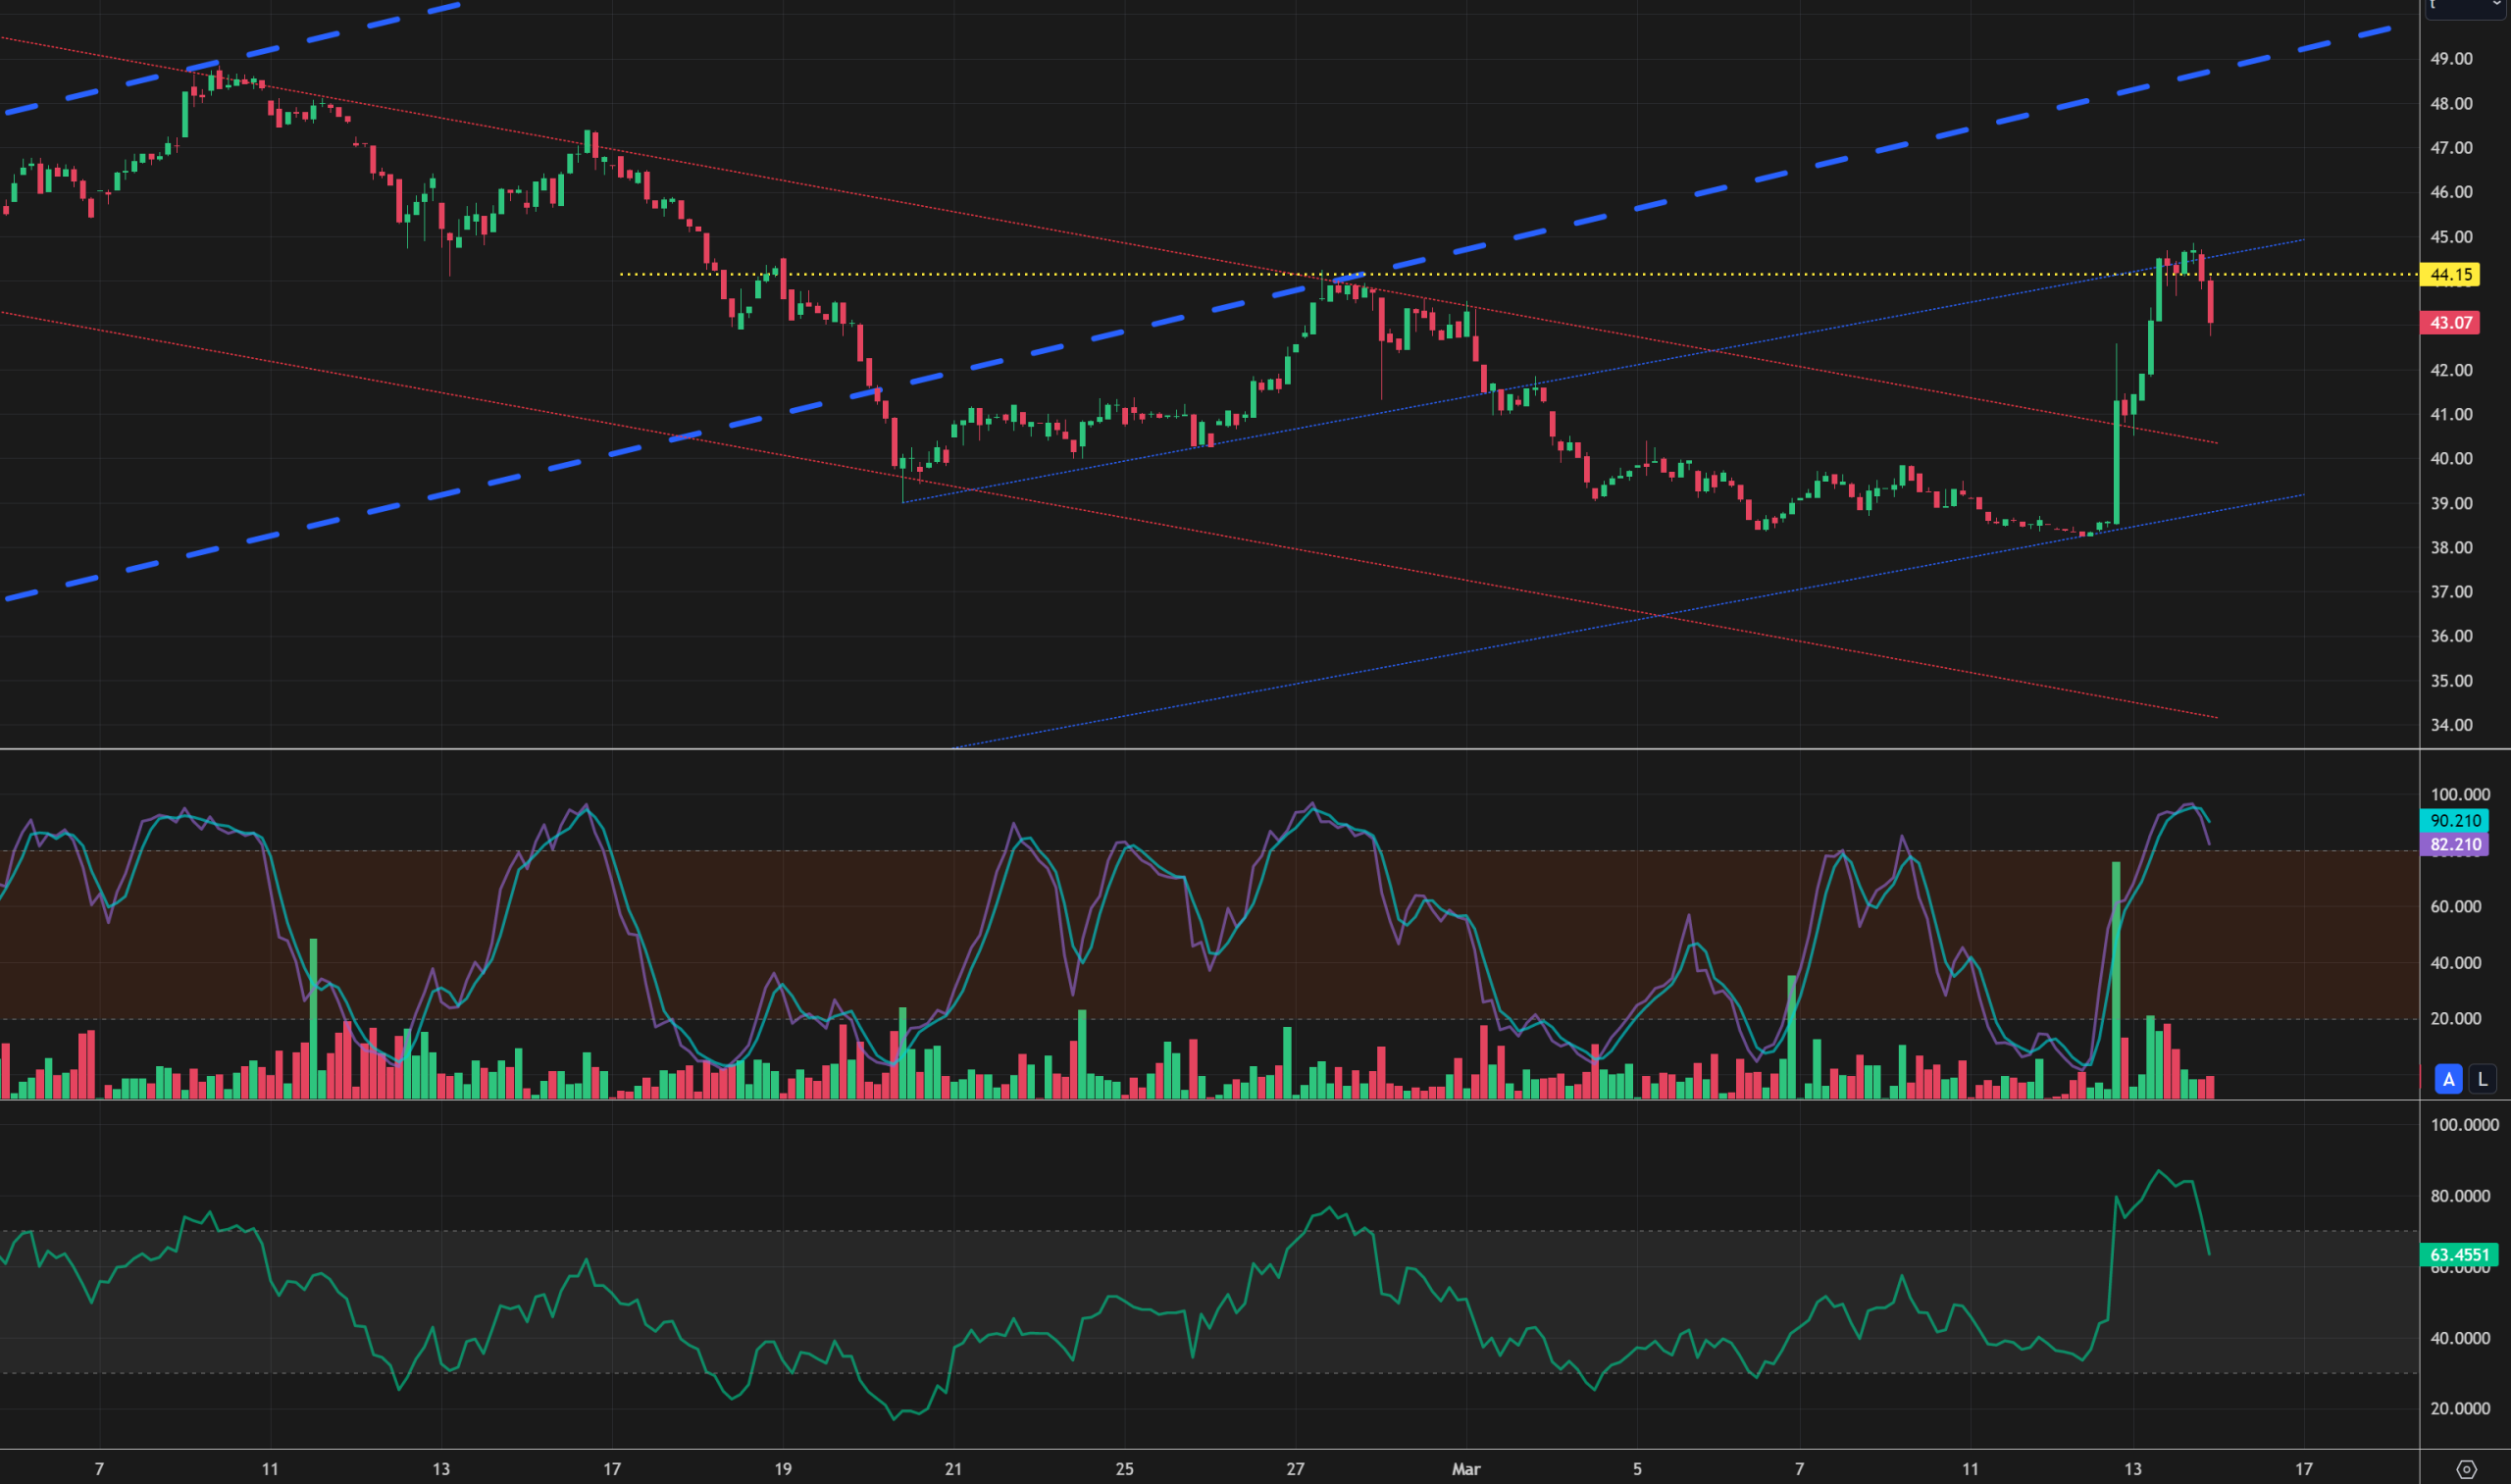
- Looking at UK mandatory Carbon allowances for heavy emitters (UKAs), the Dec-25 benchmark has rejected upside resistance at £44/tn – please see chart below.
- A new bullish trend channel is forming, and if resistance at £44/tn holds, a retest of the lower extremity of the bullish trend channel (at £40/tn) looks likely.
- UK electricity Monthly Day-Ahead averages so far for this month are back below £100/mwh and sliding – now at £93/mwh (or approx. 9.3p/kwh excluding non-energy).