



Mon, 10th Mar ’25
GAS
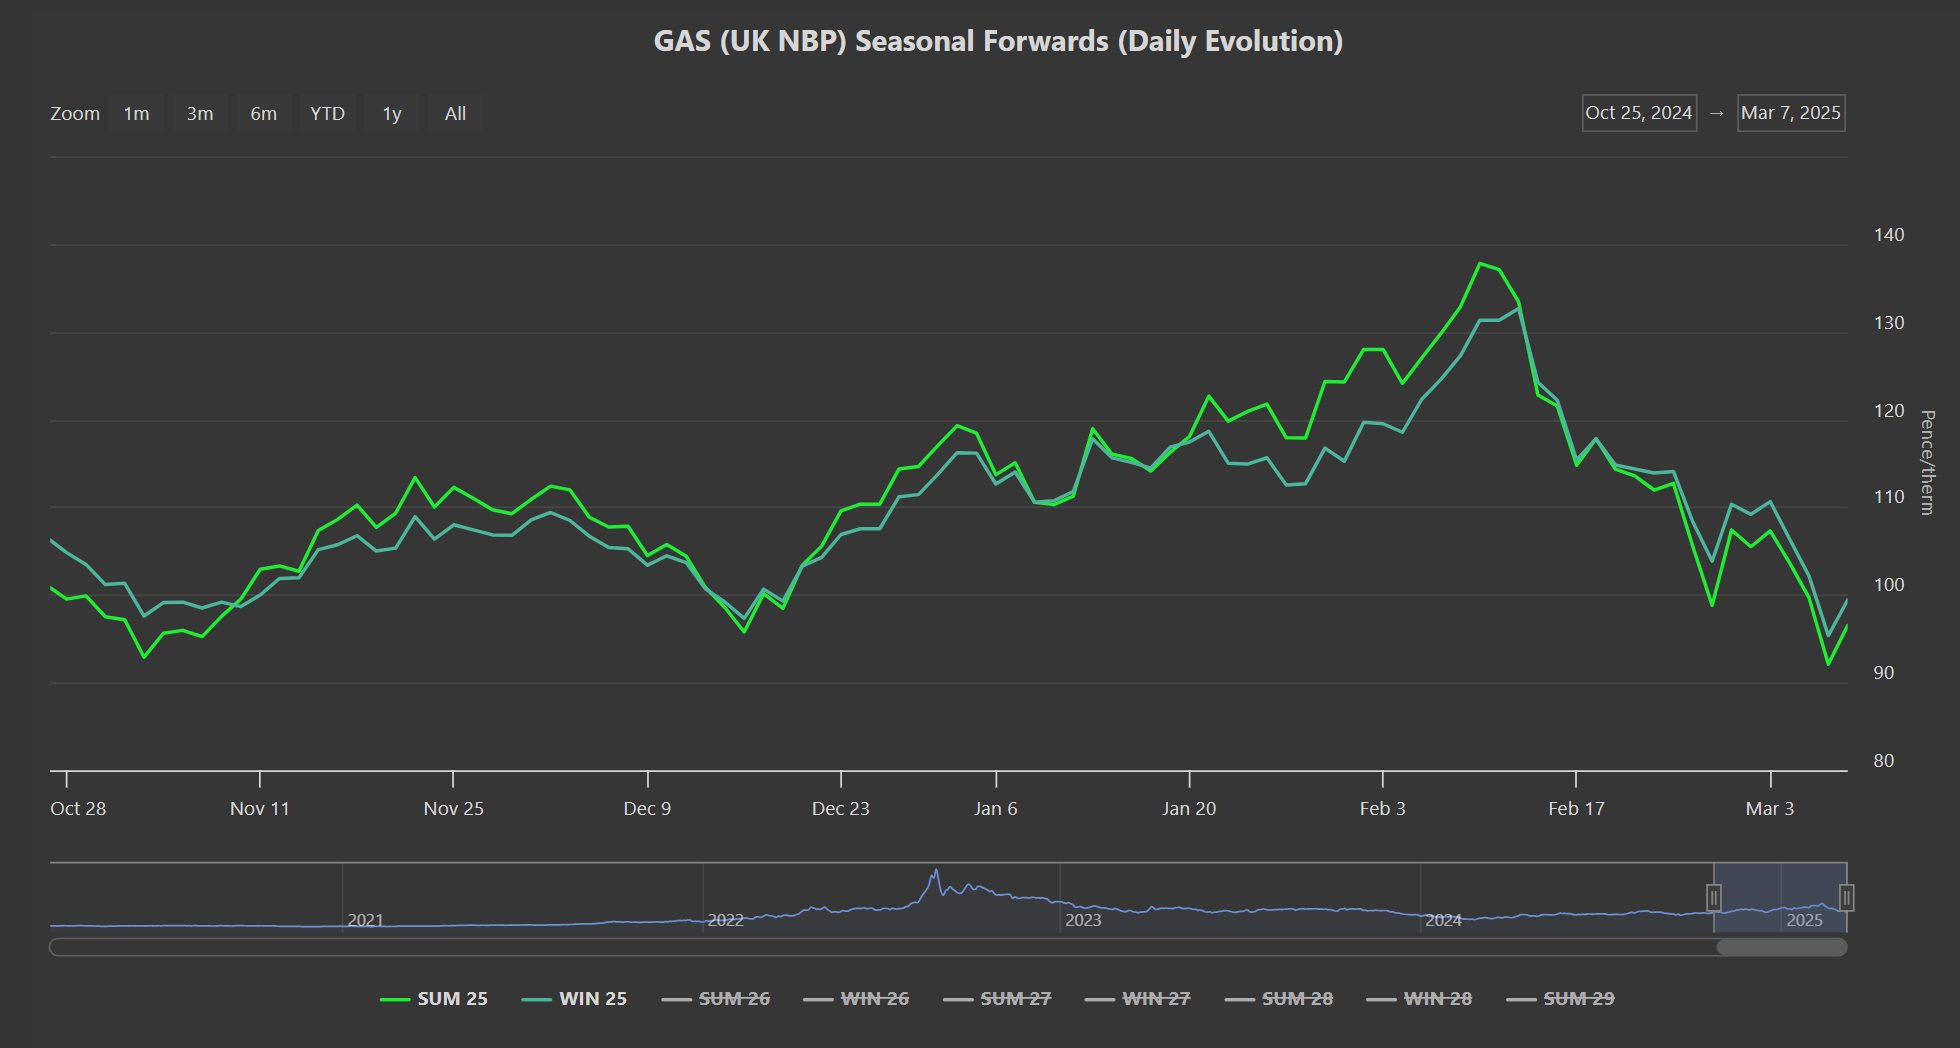
- For the time being, the anomalous backwardation of Summer-25 over Winter-25 (which first appeared back on 11th Nov ’24) is no more – please see chart below.
- This reflects, surely, a heightened confidence amongst market participants of Europe’s ability to replenish storage inventories over the coming summer in time for Winter-25 conditions.
- As things stand, Summer-25 is now at a comfortable discount to Winter-25 (so BAU has been restored).
- Markets retraced some of last week’s losses to end the week amid expectations of lower temperatures to start this week.
- No doubt, a significant chunk of this bullish retracement was driven by market participants covering short positions – but also it was likely a reaction to news of Russian forces retaking some of the Kursk region (adding weight to Putin’s negotiating position).
- Geopolitically, the markets could do without the intensification of Russian attacks on Ukrainian gas production infrastructure, which only serves to further weaken prospects for a ceasefire.
- On the demand side, (as expected) temperatures are set to fall back below seasonal norms by the end of the week, supporting near-trm delivery prices.
- This coupled with wind outputs below seasonal norms with inevitably result in higher gas-for-power burn and the associated pressure on withdrawals.
- Storage is now at 36.8% (below the 2018 to 2024 average) – but above this point in 2021 and 2022.
- For month-ahead LNG deliveries at least, (due to falling prices) Europe is losing its attractiveness compared to Asia – further highlighting what a difference it would mke to supply/demand dynamics were Russian flows be reintroduced to the European system.
- Monthly Day-Ahead averages for this month so far are on track to improve on last month’s final number (124p/therm), with averages at 102p/therm at the time of writing (or approx. 3.48p/kwh excluding non-gas).
ELECTRICITY & CARBON
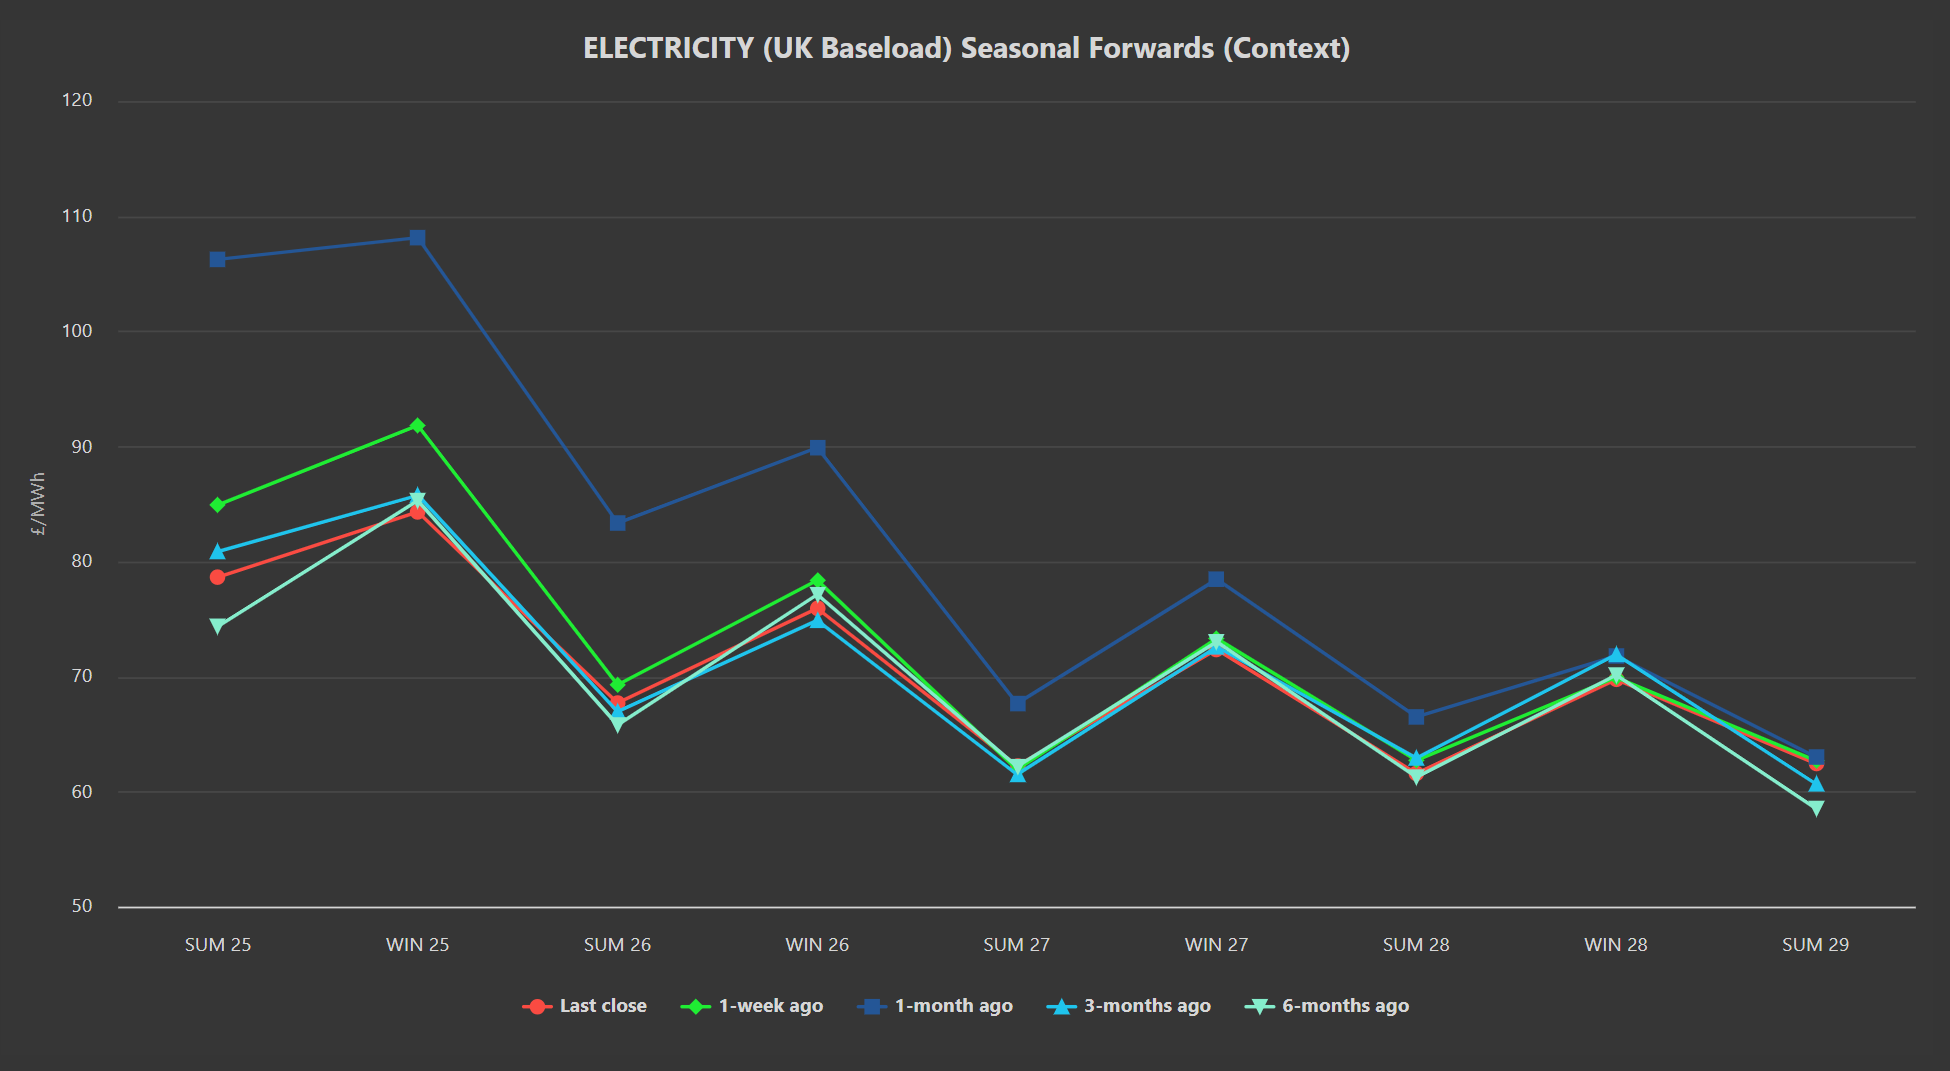
- Seasonal Forwards are now down on the week, the month, 3-months ago – and commensurate with 6-months ago (please see chart below).
- As you’d expect, electricity prices have followed much of the gas retracement we saw during Friday’s session.
- Following this weekend’s benign weather conditions, market participants are now eyeing the impending cold spell,
- Global economic data is increasingly pointing toward a slowdown (amid ongoing Trump tariff threats) – should lower interest rates fail to stimulate improved activity, demand will inevitably fall.
- Today’s UK electricity generation mix however, is bearish in nature with renewables contributing 53%, thermal at 12% (gas and coal) and low carbon at 22% (nuclear and imports).
- The Carbon markets remain closely correlated to fossil fuel prices – so as you’d expect given recent price falls, EUAs and UKAs are mirroring.
- Talk of Starmer’s intentions to merge EUAs/UKAs has gone from the headlines, and UKAs resumed their bearish bias with a confirmed downward trend channel forming back on 10th Feb.
- Prices (now at £39.35/tn on the mid) fell out of the bottom of the long-term bullish trend channel on 20th Feb, then retested this resistance level from beneath on 27th Feb, rejecting to the downside.
- If prices sustain a break below £39/tn, the next target below is £37/tn as per the high of 3rd Jan.
- UK electricity Monthly Day-Ahead averages so far for this month are back below £100/mwh and sliding – now at £90/mwh (or approx. 9p/kwh excluding non-energy).