



Thurs, 10th Oct ’24
GAS
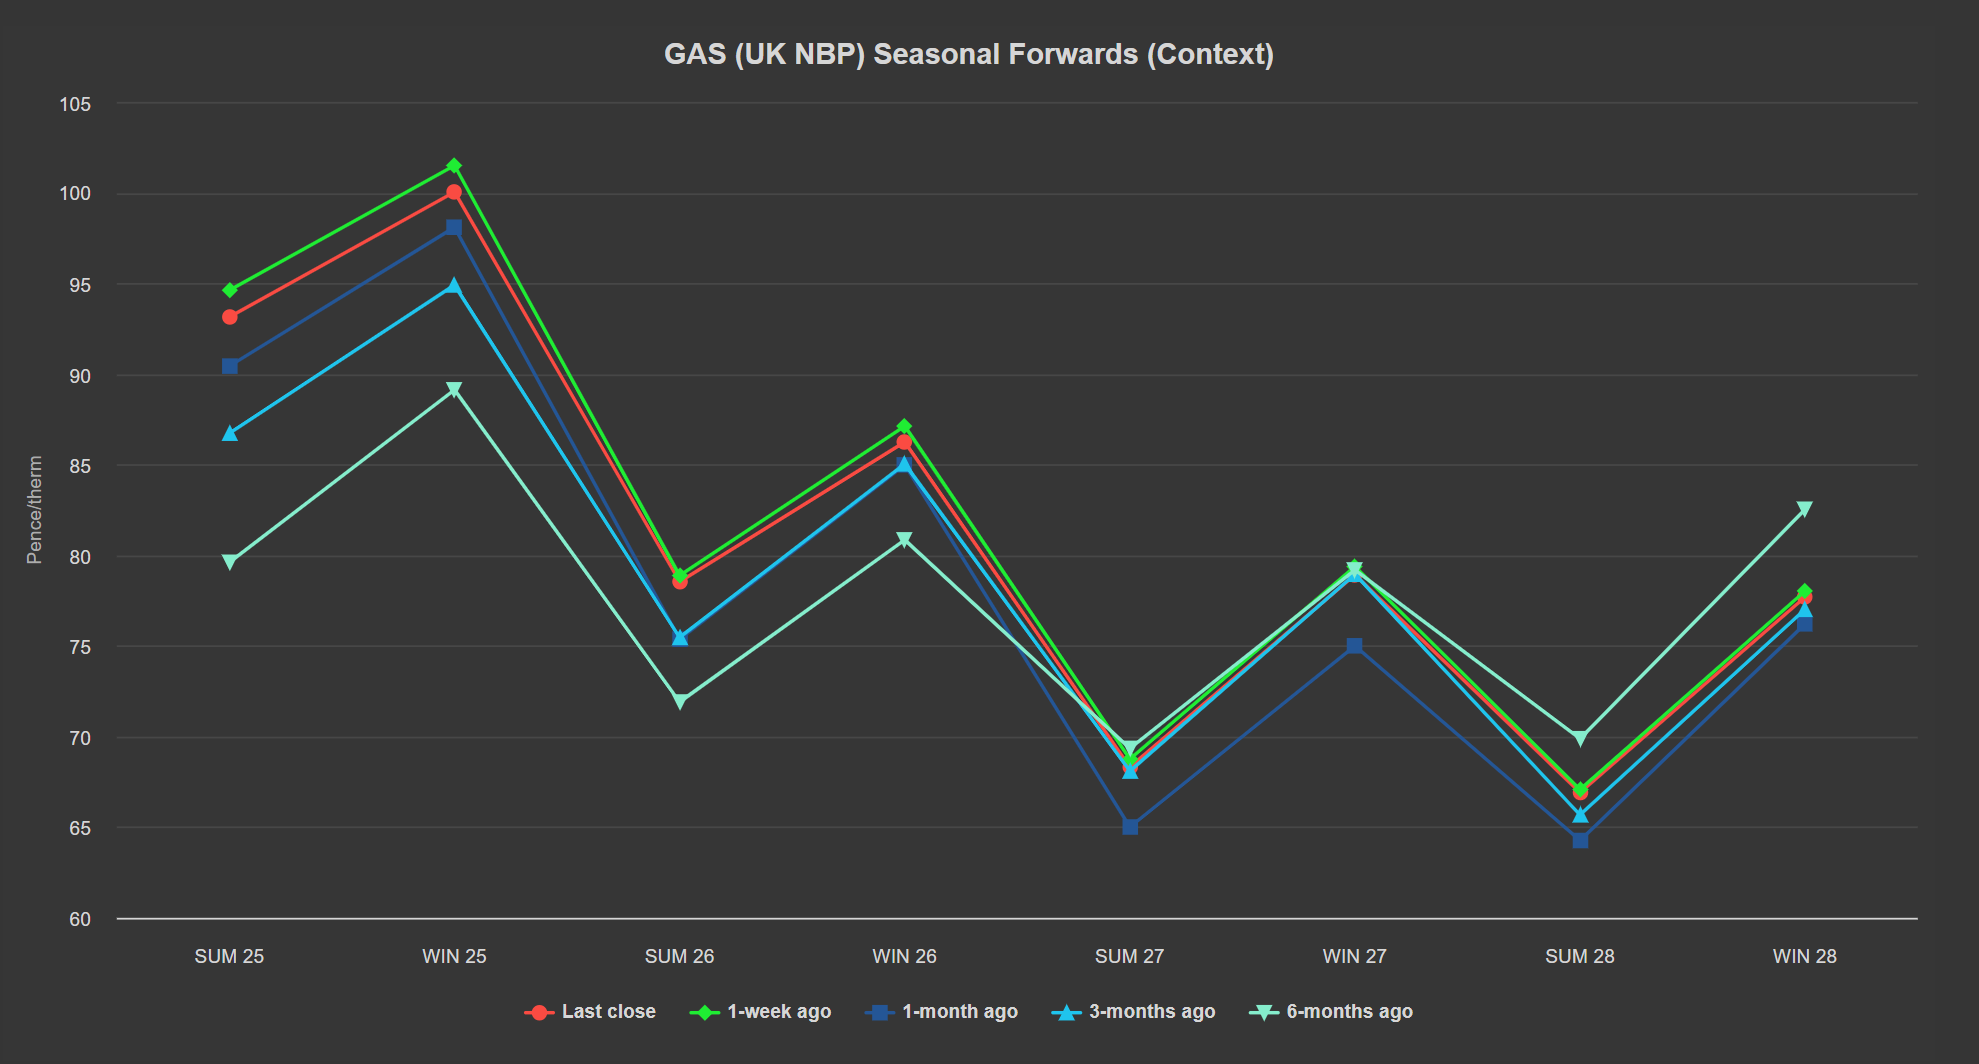
- Seasonal Forwards are down on the week, but up on the month/3 months ago/6 months ago (see chart below).
- Markets are flat today amid a long UK system (supply outstripping demand forecast).
- Geopolitical risk premium persists with the ongoing threat of further escalation across the Middle East and the ever-present supply worries linked to Eastern Europe.
- US and Israeli governments met yesterday to discuss next steps with regards Iran – the outcome remains unknown though Israel’s Defence Minister has suggested the retaliation will be “lethal and surprising”.
- On the supply side, four more LNG arrivals are expected to degasify at UK ports by 15th November.
- Unscheduled outages (blamed on compressor issues) persist at the Gullfaks and Asgard gas plants reducing Norwegian flows into Europe/UK.
- However, the combination of healthy European storage levels (at 95% fullness verus the 5-year average of 91%) and temperatures forecast to rise back above seasonal norms by mid-month, continue to keep a lid on prices.
- Globally, some nations are crying out for fresh gas supplies – with Germany not seeing sustained quarterly growth since 2022.
- Whilst Europe’s last two winters have been exceptionally mild, the colder temperatures already being forecast this season will likely heighten competition with Asia for global LNG – ultimately resulting in shortages for countries unable to purchase them (scarcity of course means higher commodity prices).
- Monthly Day-Ahead averages so far this month are on target to achieve 96.871p/therm (or approx. 3.305p/kwh excluding non-gas).
ELECTRICITY & CARBON
- Looking to the continent for price signals, EUAs briefly dipped below €60/tn yesterday.
- The benchmark Dec’24 contract closed the day at €62.01/tn, gaining overall 2.85% on the day.
- Amid unsupportive fundamentals, we could see a short lived rebound to the daily MAs (with a cluster around €63.6/tn), before moving back lower towards €60/tn as the downtrend is expected to continue.
- UKAs are on a bullish retracement having tested £35/tn on the mid-price – now at £38/tn – though next week’s auction settlement (if low) will bring about a continuation of the downtrend.
- Wind generation aross Europe (especially Germany) will likely bring about some negative intraday pricing.
- Clouds will limit solar output for the next week or so.
- Rain is forecast to soak Southern and Central Europe before the weekend, boosting hydro production.
- EDF has warned of the impact of two potential events:
- 1) Potential flooding in the Durance valley in the Alps from 8th Oct, significantly reducing hydro capacity.
- 2) A delay restarting three nuclear plants by a combined 14 days amid a depreciated price environment (so as not to flood the market with over-supply and further depress value).
- Back in the UK, our electricity generation mix is bearish in nature today with renewables contributing 44%, thermal at 24% (gas and coal) and low carbon at 17% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £81.141/mwh (or approx. 8.1141p/kwh excluding non-energy).