



Mon, 7th Oct ’24
GAS
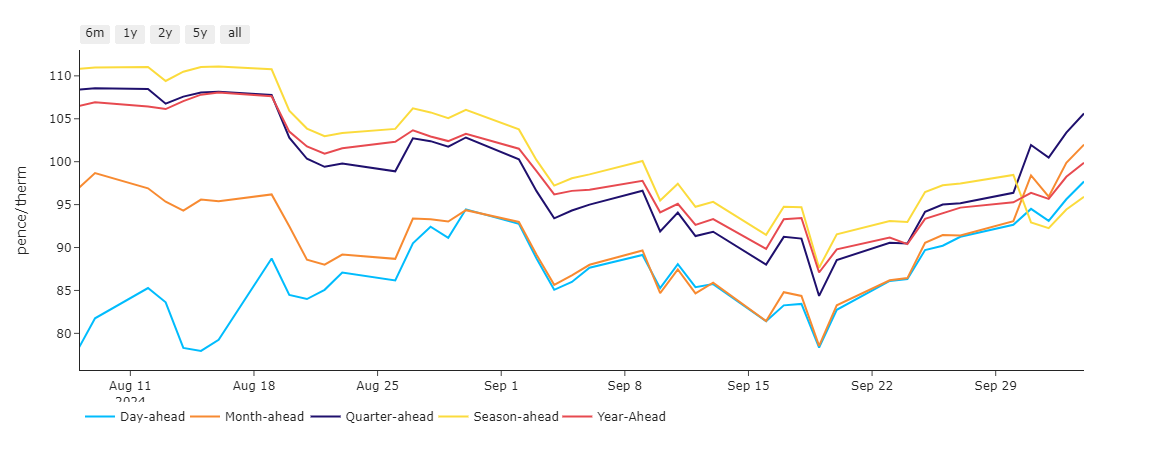
- Whilst Day-Ahead remains the least expensive way to buy gas, it’s worth noting that near-term delivery has begun the Winter-24 season on a bullish note (see chart below).
- With the onset of Winter-24, geopolitical events seem to be the focus of bullish fervour – with concerns persisting over disruptions to exports and key transit routes across the Middle East (and Eastern Europe).
- Market participants are watching closely to see how Israel might respond to Iran’s recent ballistic missile attack.
- On the supply side, the ongoing outage at Troll (taking 13 million cubic metres of Norwegian flow offline) is also a major supportive driver this morning.
- Our system opened short this morning (demand forecast outstripping supply) – though total demand is on par with seasonal norms.
- Temperature forecasts are showing a dip below seasonal norms this weekend, but should be back up above seasonal norms come mid-month.
- Monthly Day-Ahead averages so far this month are on target to achieve 96.903p/therm (or approx. 3.306p/kwh excluding non-gas).
ELECTRICITY & CARBON
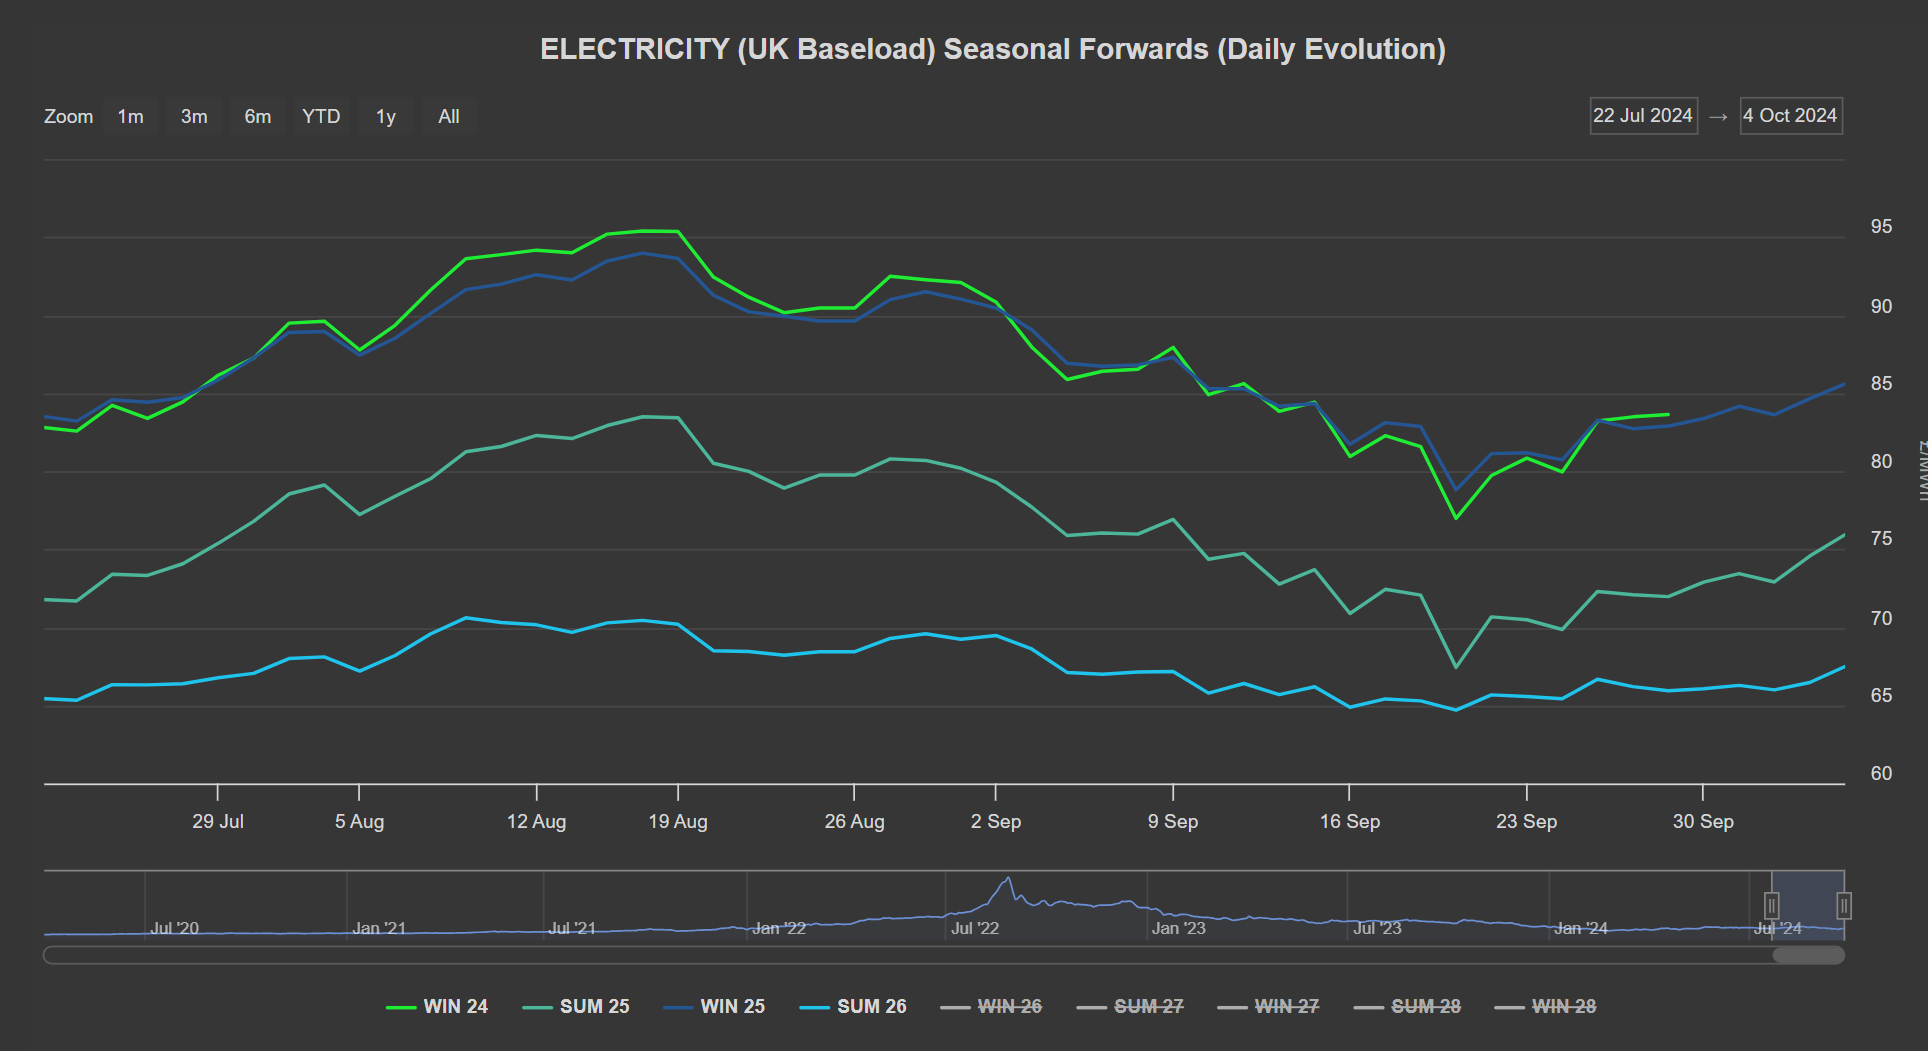
- With Winter-24 having now begun, the Front Seasons (Summer-25/Winter-25/Summer-26) are turning ominously Northwards (see chart below).
- In typical winter-fashion, prices down the curve are starting to stretch, with Summer-26 posting a 21% discount versus Winter-25.
- Looking to the continent for price direction, cyclone Kirk is providing warmer conditions this week across Central Western Europe, where 3°C above normal is forecast for tomorrow in Germany.
- EUAs closed in a downtrend last week – low demand for credits resulting in a decoupling from surging gas prices.
- The bearish trend continues at the time of writing, the Dec’24 benchmark contract already having lost an additional -2.26%.
- Back in the UK, UKAs are also very much in a downtrend having dropped below and out of the confirmed daily triangle pattern, then breaking below the mid-August lows on good bearish volume.
- £33.50/tn is now a viable target to the downside marking an area of confluence (historical low plus lower extremity of descending trend channel) – see 30th Sep’s technical chart here.
- Fundamentally, the fall in UKAs is being attributed to market participants’ reaction to UK policy review (or the Free Allocation Review).
- The outcome being that the expected scarcity of UKAs come 2026 has now been puished back to 2027 – no doubt resulting in speculators reducing long (buy) exposure.
- Last week’s auction cleared at £34.91/tn.
- Our electricity generation mix is bearish in nature today with renewables contributing 40%, thermal at 22% (gas and coal) and low carbon at 20% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £81.976/mwh (or approx. 8.1976p/kwh excluding non-energy).