Markets consolidate pending the US congressional mid-terms in 27 days’ time
GAS
We’re now 7 days into Winter-26, and little has changed on the week – the Strait of Hormuz remains all but closed to LNG transit, and vessels that do venture across the stricken waterway continue to be sporadically targeted by “projectiles”.
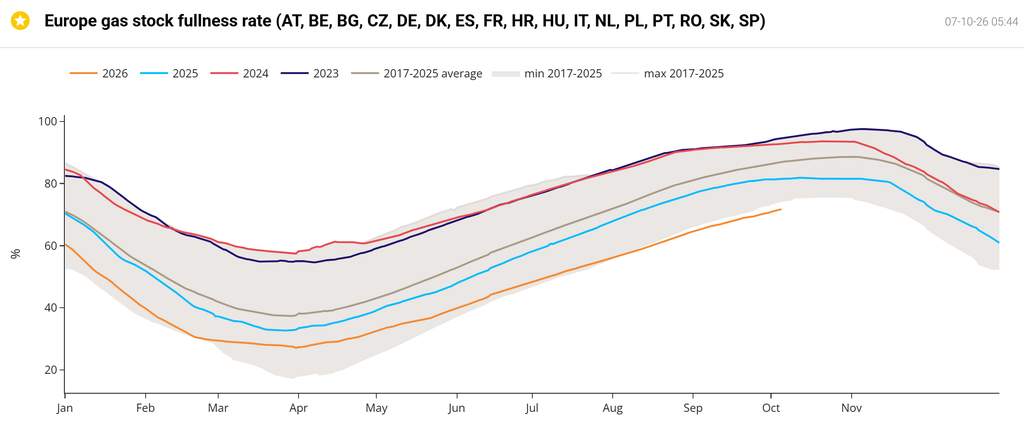
Fundamentally speaking, European storage fullness is at 72% versus the 8-year average of 87% – so bad, but not desperate:
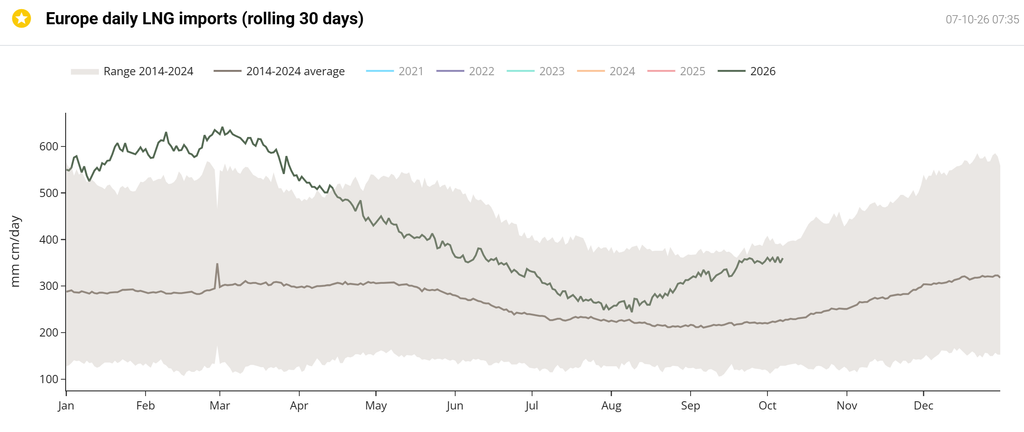
LNG imports into Europe as a whole have increased 33% since 8th Sep (the increase having been served pretty much entirely by US exports):
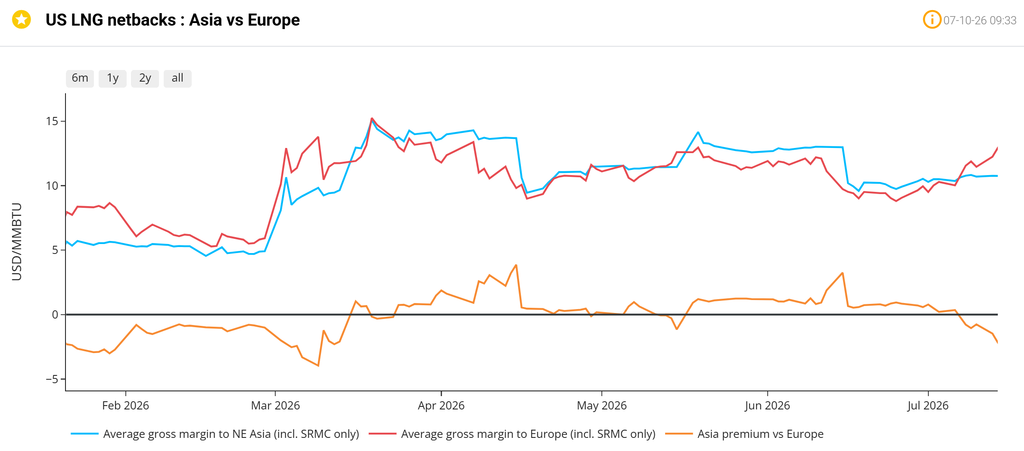
So not surprisingly, US LNG netbacks (which delineate vessel profitability for Asia versus Europe) shows that vessels headed to Europe are making more money than if they head across the Pacific to China (so European prices need to stay high to keep imports at the required levels to replenish storage over the ienter months):
Across NW Europe, an Arctic front is expected to lower temperatures to 10°C–12°C beginning tomorrow (goodbye summer!) – however, blustery wind coditions are expected to cap any reliance on gas-for-power burn (limiting demand).
The front season is now, of course, Summer-27. Ordinarily, summers are discounted versus winters (given lower demand in the warmer months) – however, Summer-27 remains more expensive to buy than Winter-27 (this condition began a month or so ago). Summer-28 onwards remains at a significant discount to front-end prices – accordingly, we’re seeing an increasing proportion of clients beginning to hedge volumes for these periods of delivery given the values on offer down the curve:
View as table
| Season | Last close (p/therm) | 1 week ago | 1 month ago | 3 months ago | 6 months ago |
|---|---|---|---|---|---|
| SUM 27 | 146.07 | 131.13 | 122.51 | 81.36 | 96.29 |
| WIN 27 | 140.24 | 125.85 | 118.30 | 82.17 | 95.01 |
| SUM 28 | 89.52 | 82.40 | 78.95 | 62.57 | 68.66 |
| WIN 28 | 95.73 | 89.98 | 86.21 | 70.91 | 74.54 |
| SUM 29 | 73.16 | 69.81 | 66.85 | 56.78 | 63.97 |
| WIN 29 | 81.91 | 78.85 | 74.96 | 66.14 | 71.92 |
Trump’s approval rating is languishing down at 32%, and on paper, it looks as though the Democrats will take both houses back off the Republicans come 3rd Nov – if Trump is worried about potential humiliation/impeachment, he’s not showing it. Instead, he continues to talk of further military strikes AFTER the mid-terms. Should they retake the majority (as is widely anticipated), we’d think it unlikely that the Democrats would get behind such a plan!
And so, all the markets can do is wait and see, and hope that supply networks outside of the Middle East continue to function without disruption, and that temperatures over the coming months don’t fall too far, for too long.
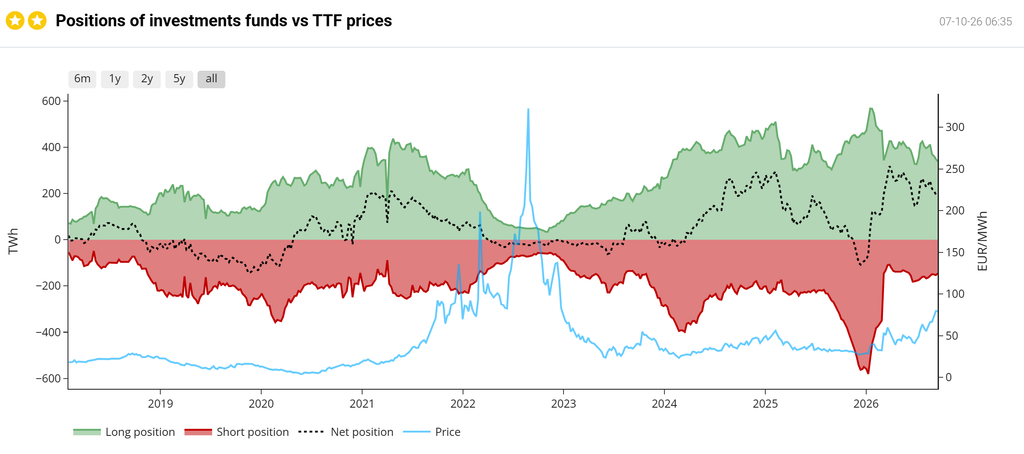
For the third week in a row, investment funds have decreased their net long Positions in the TTF (European gas benchmark) – so profit-taking persists, but more importantly, bullish fervour has dissipated amid an underlying sentiment that Trump’s ability to wage war (and incite global discord in the interests of US protectionism) is losing steam:
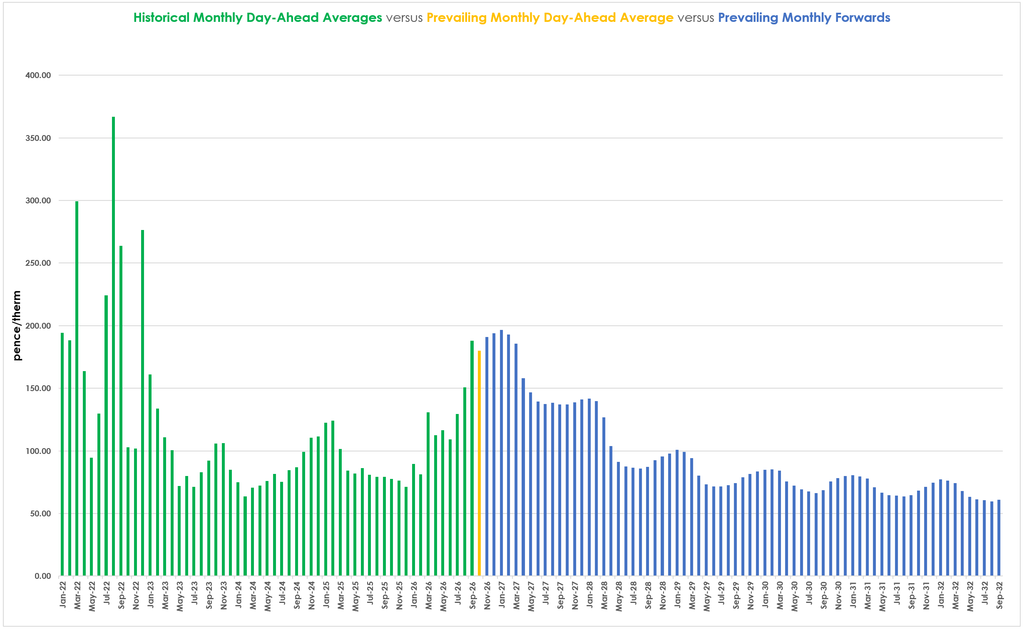
Monthly Day-Ahead Averages for October so far are at 180p/therm (or 6.1p/kwh exc non-gas) – marginally down on last month’s final number of 188p/therm (or 6.4p/kwh exc non-gas):
ELECTRICITY & CARBON
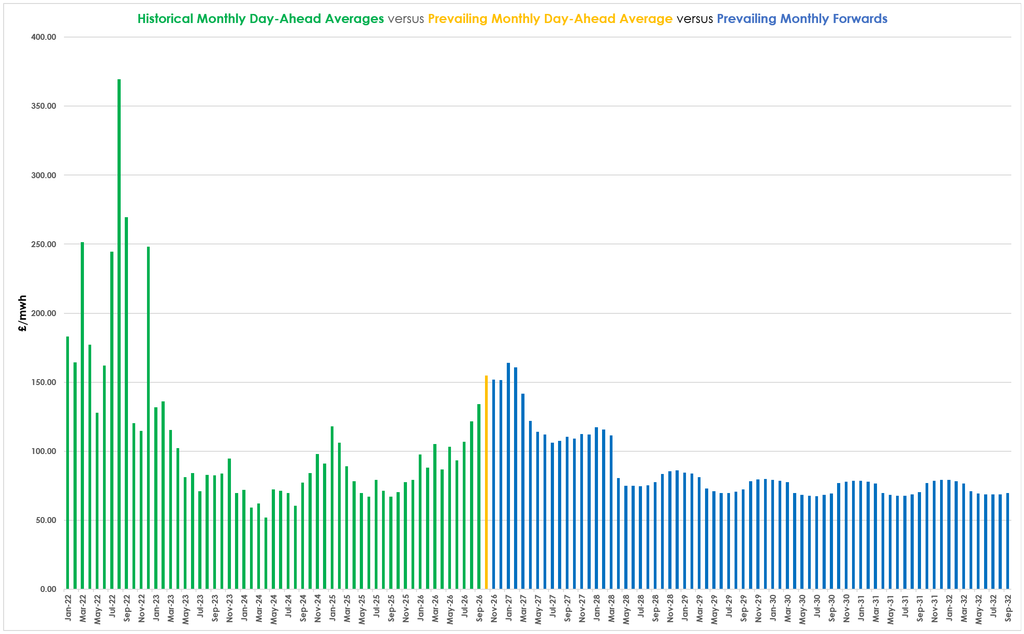
Far-curve Forward prices (available to secure now) are at almost a 60% discount versus Winter-26 delivery – this reflects the market’s underlying hopes that life will return to normal beyond the November mid-terms.
Electricity Seasonal Forwards remain at a comparative discount to gas, this is down to solid renewables outputs limiting gas for power burn over the summer months – though of course this will change in the coming weeks as the days get shorter, and the wind drops (usually around mid-November):
On the Carbon side of things, mid-price Dec-26 UKA delivery sits at at £63.07/tn (and the spot is at mid 62s) – prices are significantly up this week if for no other reason than winter is upon us, and gas-for-power burn is likely to increase in the coming weeks (as net injection into storage shifts to net withdrawal).
UK electricty Monthly Day-Ahead Averages for October so far are at £155/mwh (or 15.5 p/kwh exc non-energy), up from last month’s final number of £134/mwh (or 13.4p/kwh exc non-energy):