



Wed, 8th Apr ’26
GAS
- Last night, less than two hours before Trump’s midnight deadline (GMT), a Pakistani-brokered ceasefire was agreed (and the world breathed a collective sigh of relief).
- Not surprisingly, this morning markets were significantly down, particularly at the front-end.
- Prices have continued to slide throughout the day – with all eyes now on the Strait of Hormuz for the first signs of safe LNG transit.
- However, rumours abound that an exodus of ships through the waterway over the coming days remains a question-mark, with the Iranian regime still claiming full control – this will have to change ASAP if today’s optimism is the be sustained.
- For now, traders are glued to tracking-data, monitoring which vessels are attempting to transit (and if they do so safely!)
- To reiterate, not a single LNG vessel has transitted the Strait of Hormuz since 28th Feb – so early movements will be a fundamental driver of prices this week.
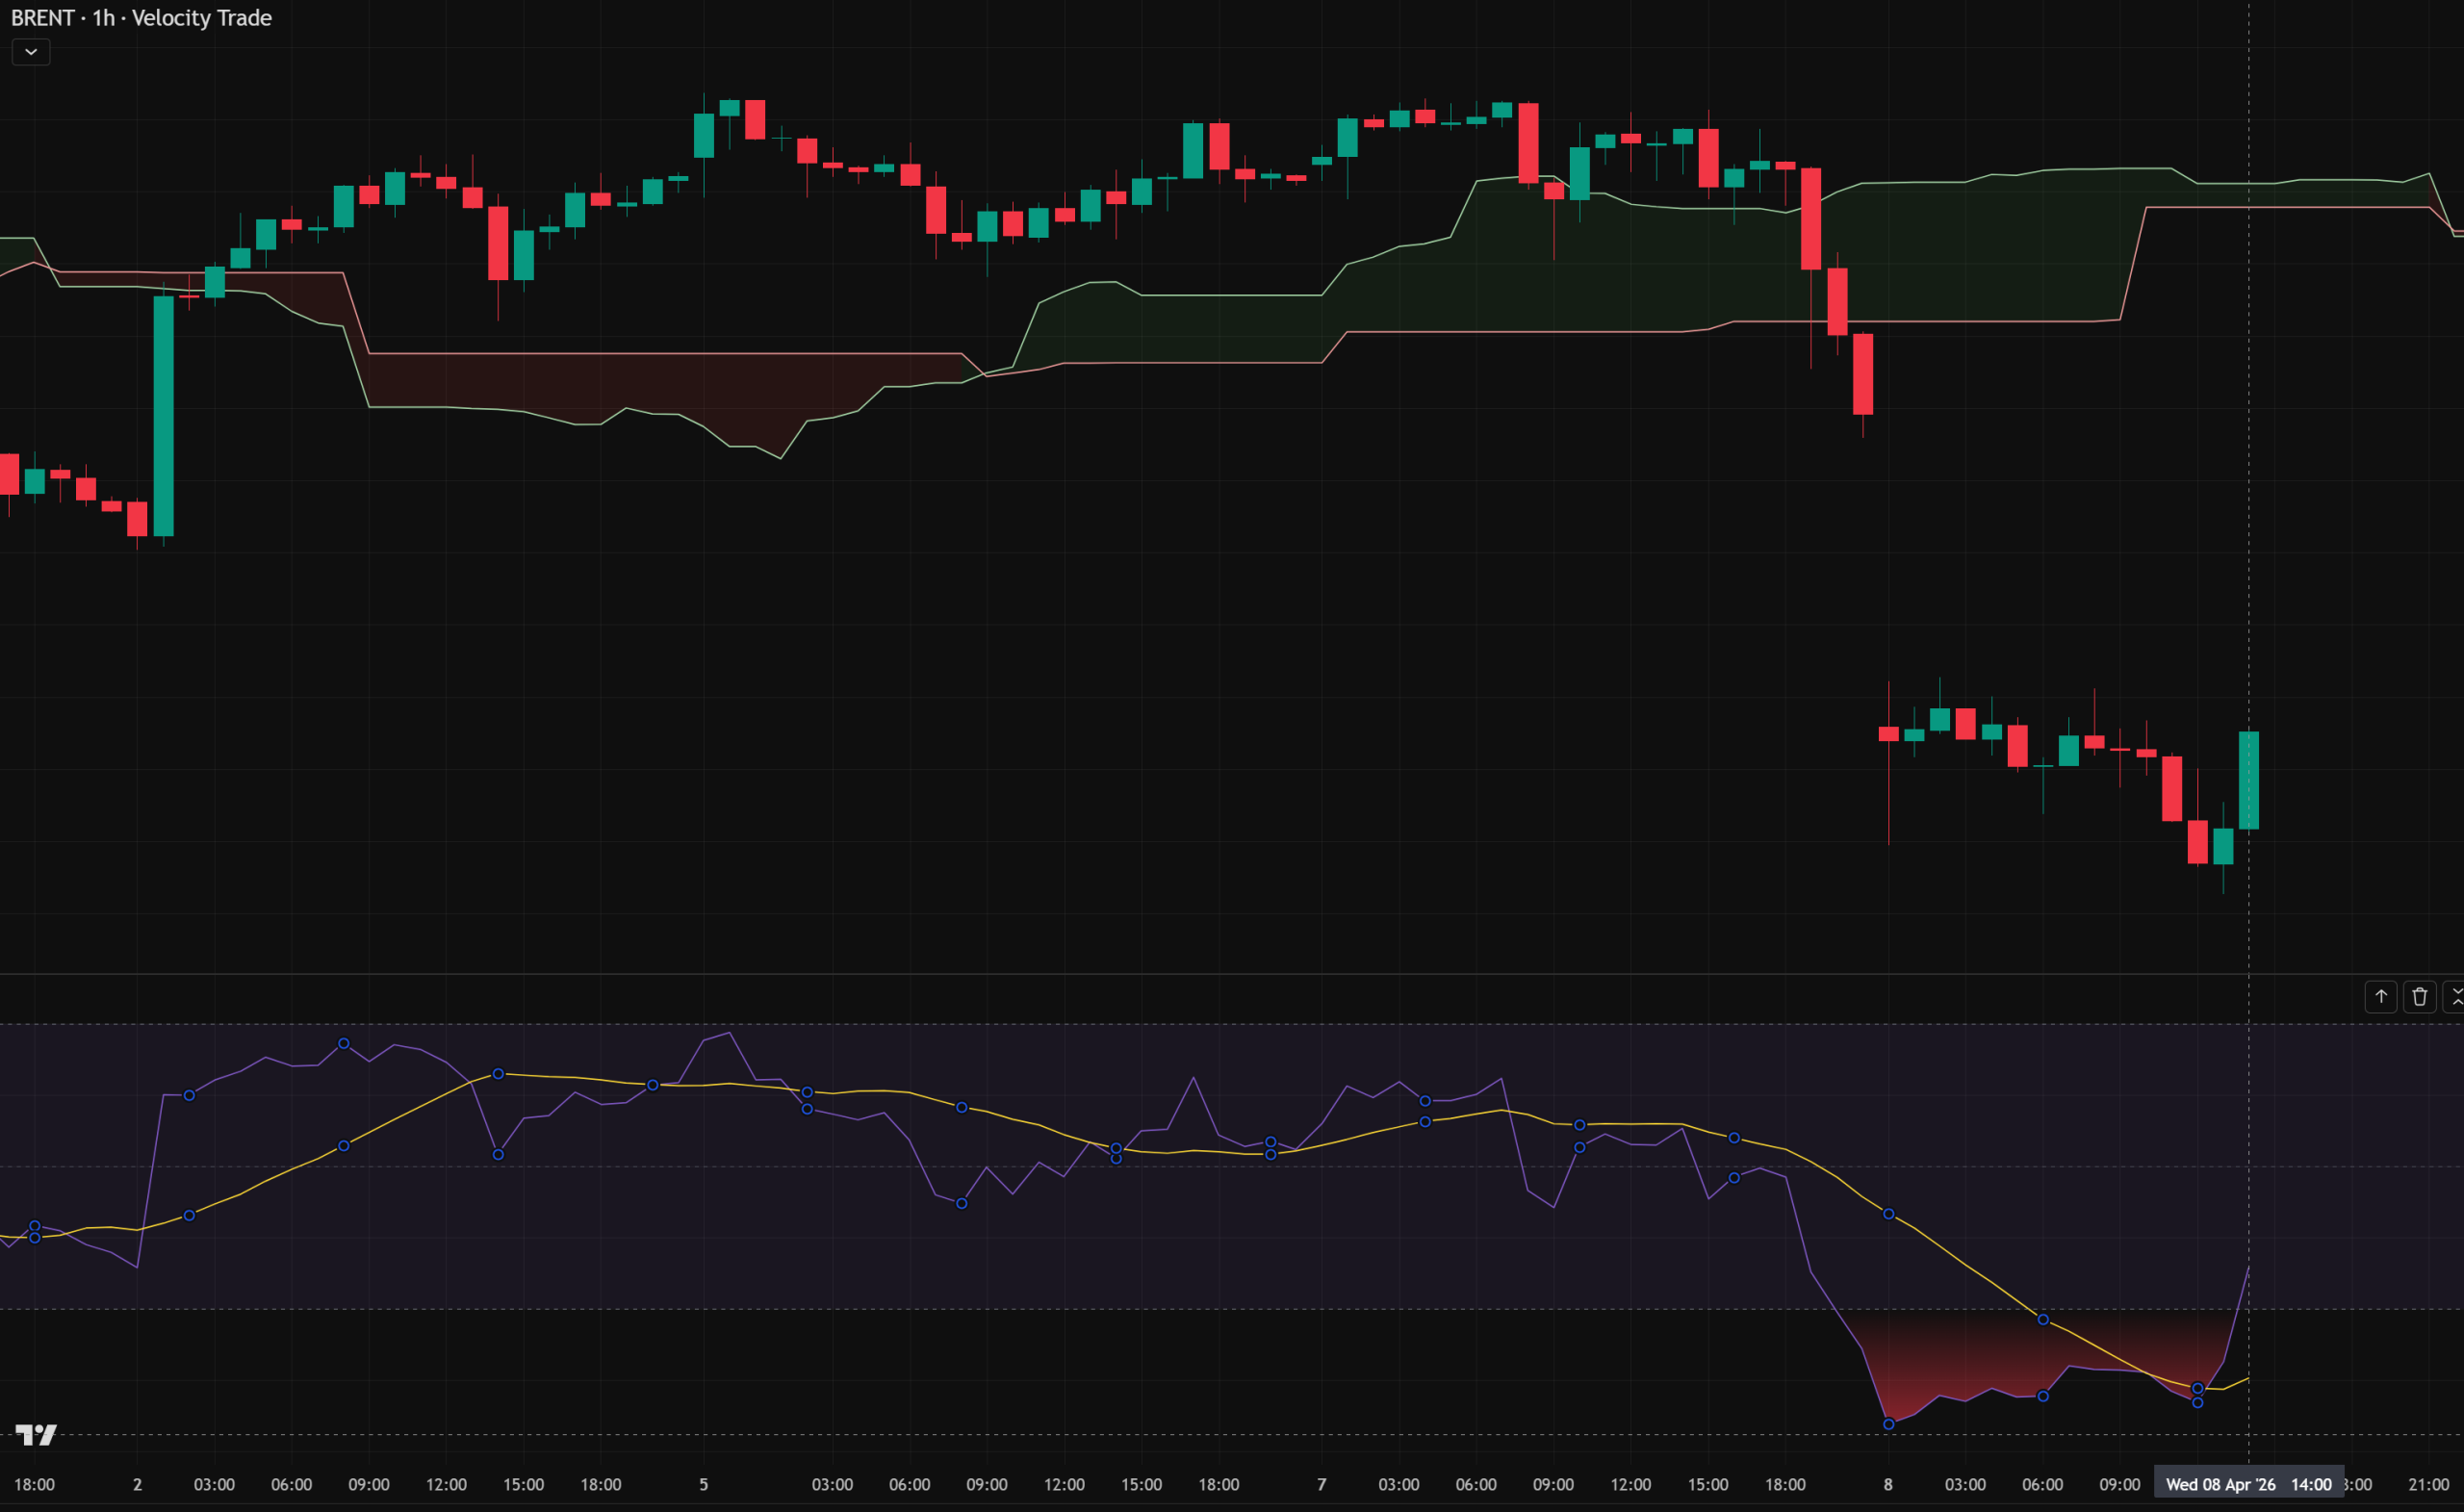
- On other markets, equities have surged as investors piled back into stocks, gilts have risen (yields have fallen), and brent crude gapped down by $7 to start the day well below the $100 psychological level (please see chart below).
- So, in the short term, markets are down, and the coming days should bring good opportunities to hedge the front-months whilst the market is in this dip.
- However, looking forward, Trump’s original reasons for the offensive remain unresolved – the Iranian regime are still in control; the regime’s stocks of enriched uranium are still out-of-sight; their missile and drone capability is still very much in place.
- So, will the ceasefire hold?
- Well, Israel is still pounding Lebanon, and Iran was still firing missiles at its Gulf neighbours this morning (most notably, the East-West Saudi pipeline).
- So, the coming days will establish if the truce has legs – or if the ceasefire is just a hiatus (in advance of the still-threatened US ground invasion).
- In other fundamental news, the summer maintenance season is nearly upon us – so, Norwegian capacity is expected to see a slight decrease this week (beginning Thursday).
- Right now, European storage fullness is at 29% versus the 5-year average of 38%.
- Monthly Day-Ahead Averages for the month so far are holding steady at 124p/therm.
ELECTRICITY & CARBON
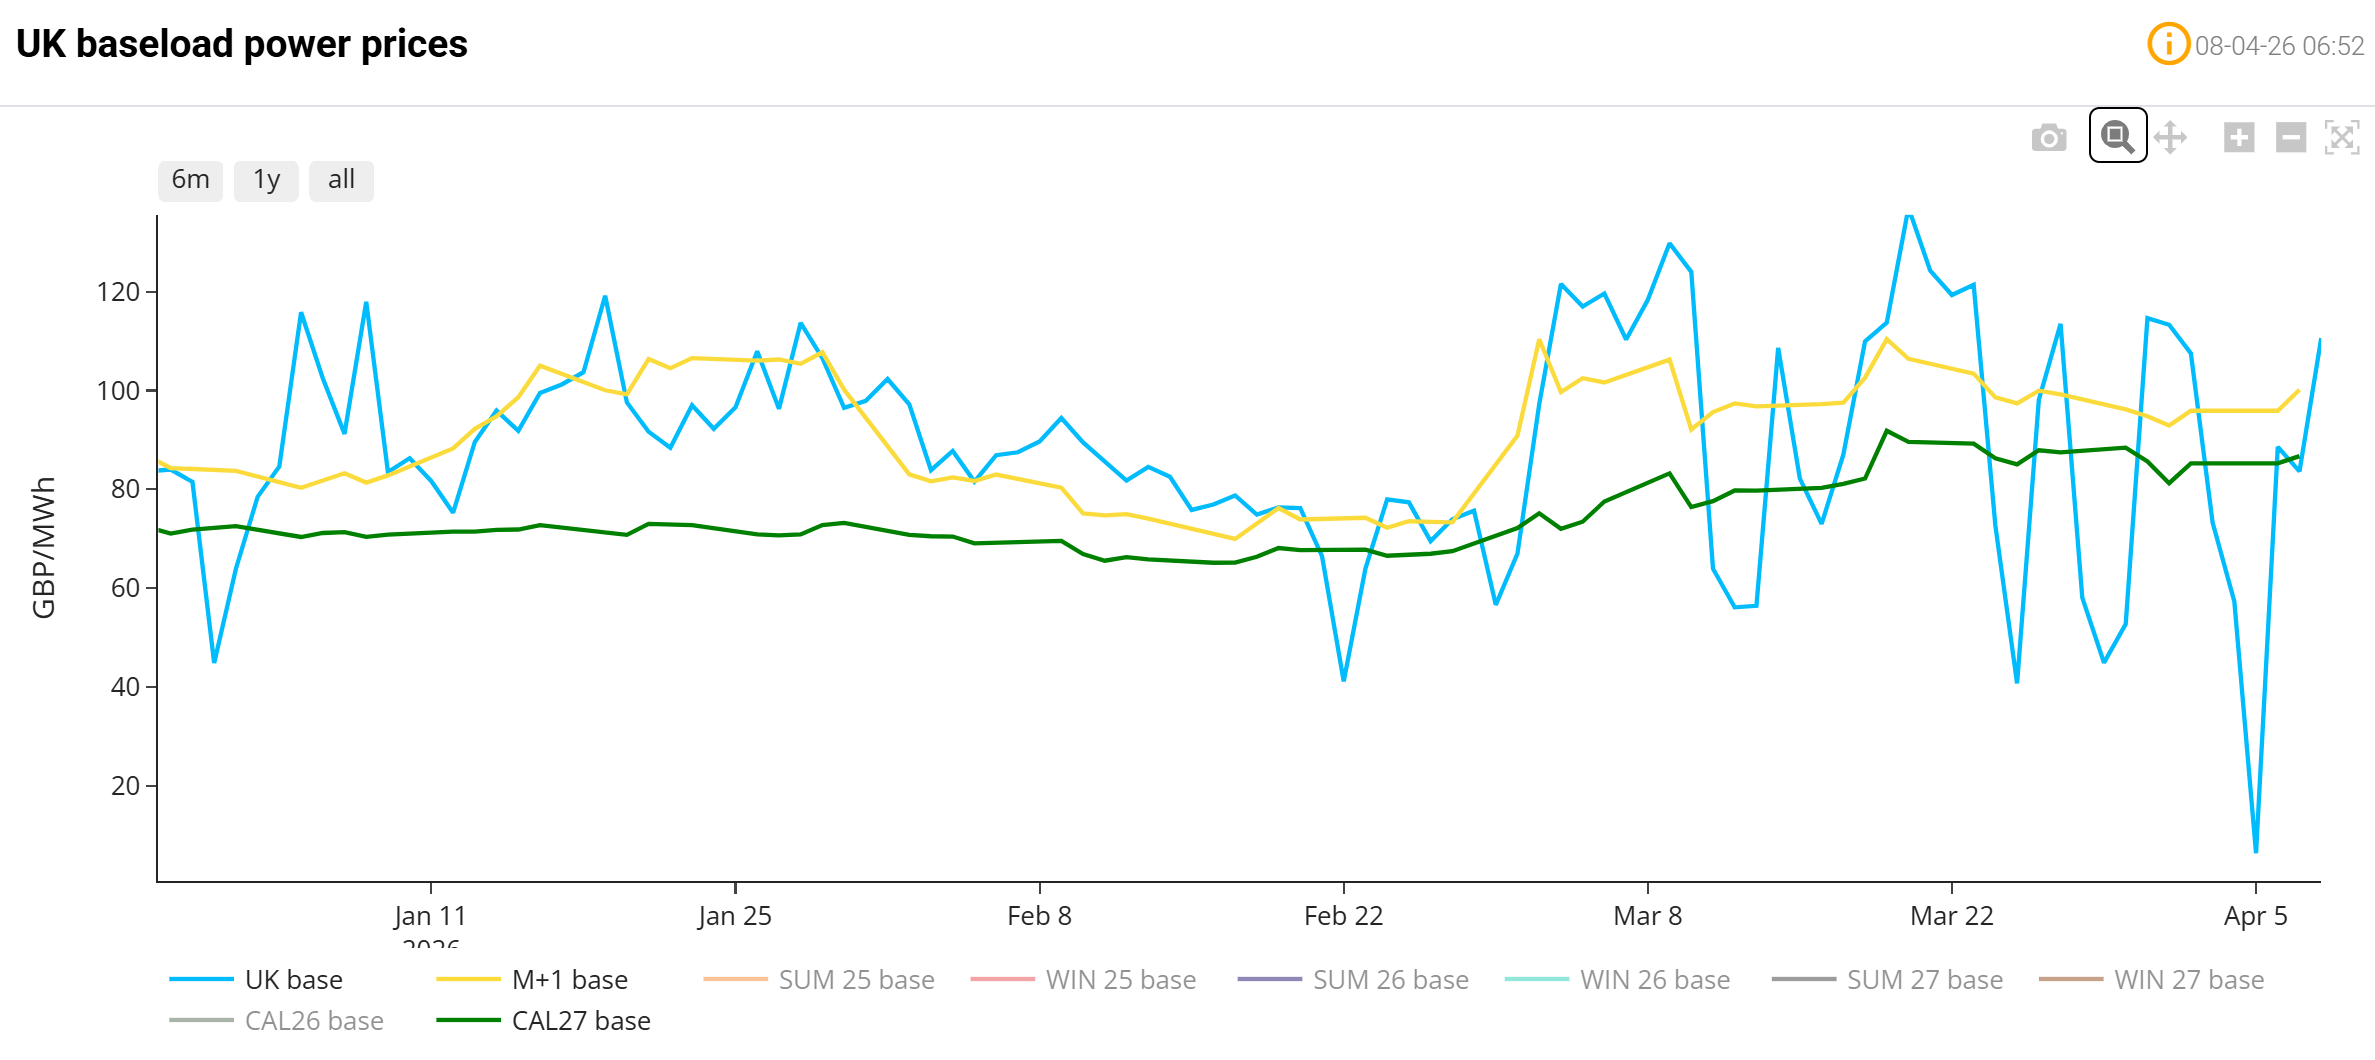
- The chart below details UK electricity Day-Ahead (blue)/Month-Ahead (yellow)/CAL-27 (green).
- It shows nicely the heightened volatility of near-term delivery since 28th Feb versus only very small changes in delivery prices further out.
- This discrepancy, of course, reflects an underlying sentiment amongst market participants that the prevailing geopolitical chaos is not expected to last.
- UK electricity prices remain at a significant discount versus gas prices (given summer conditions/improved renewables outputs/falling gas-for-power burn).
- On the Carbon side of things, Dec-26 UKA delivery remains uncoupled from gas volatility with prices touching levels that are 33% below those printed in mid-Jan amid fears that Trump’s war on Iran is slowing global economies (and, in so doing, Industrial outputs).
- At the time of writing, UKA mid-price Dec ’26 delivery is at £42/tn (and the spot is at mid-40s).
- Since the US/Israeli offensive began, gas price falls are met with rising UKAs – and vice versa.
- Monthly Day-Ahead Averages for UK electricity for the month so far remain at £86/mwh.