



Wed, 23rd Apr ’25
GAS
- Delivery prices for the front 3-Seasons (Winter-25; Summer-26; Winter-26) are down versus 1-week/1-month/3-months/6-months ago.
- In addition, Day/Month/Quarter/Year-Ahead are at a significant discount to Season-Ahead – so no matter how you look at it, noise aside, comfortable fundamentals abound, and comparative summer value is increasingly on offer.
- Prices dropped off yesterday again against a backdrop of improving weather forecasts and falling demand.
- Some Norwegian pipeline flows have been redirected from Europe to the UK – nonetheless, our system opened short this morning (demand forecast outstripping supply) – so Day-Ahead might see a little upward pressure today but not enough to have any meaningful impact on prices further down the curve.
- European gas prices remain at a premium to the UK’s, reflecting marginally less risk in our supply/demand dynamics.
- Storage levels across Europe are at 37% versus the 5-year average of 50%, so whilst the trajectory of stock replenishment is shallow, at least it’s climbing (and injections are steady).
- Market participants remain pretty much entirely focussed on whether Europe will be able to adequately re-fill storage inventories in time for the withdrawals season (Winter-25).
- Europe is seemingly preparing to shoot itself in the foot, with a sanction on spot purchases of Russian LNG still looking likely – limiting much needed supply over the coming months.
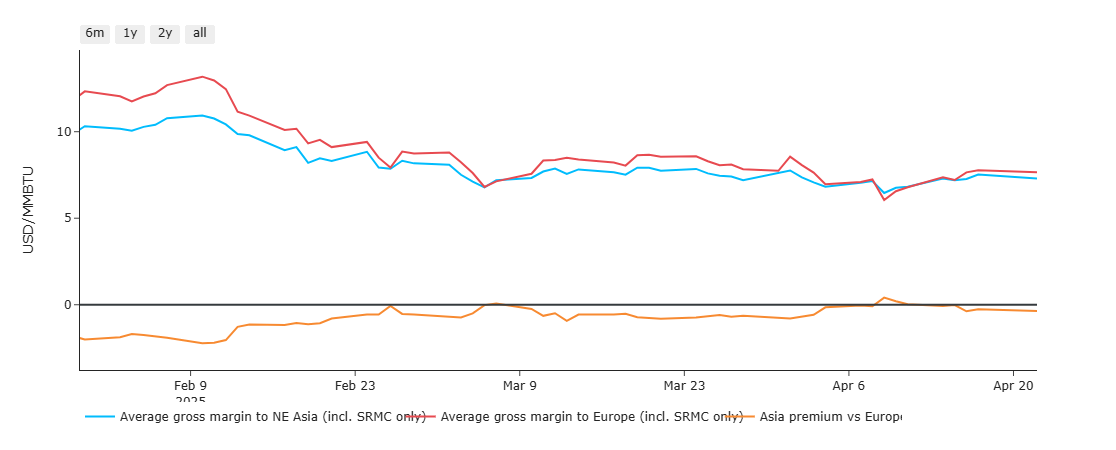
- Asia JKM prices are down again, and LNG netbacks remain in Europe’s favour (i.e., LNG cargoes are making more profits heading to Europe than Asia) – please see chart below.
- Buyers should be mindful that the bottom of this market may only come about if/when it becomes clear that we’ll successfully replenish gas stocks in time for Winter-25, and/or Putin and Trump engineer a means of getting more Russian gas flows into the European system – neither of which may happen any time soon.
- As such, taking a nibble out of current prices (or ‘scaling-in’) would seem increasingly prudent – hedging increments of Forward volumes regularly (and gradually) as summer progresses.
- This month’s UK gas Day-Ahead averages are holding very steady at 87p/therm (or approx. 2.9p/kwh excluding non-gas).
ELECTRICITY & CARBON
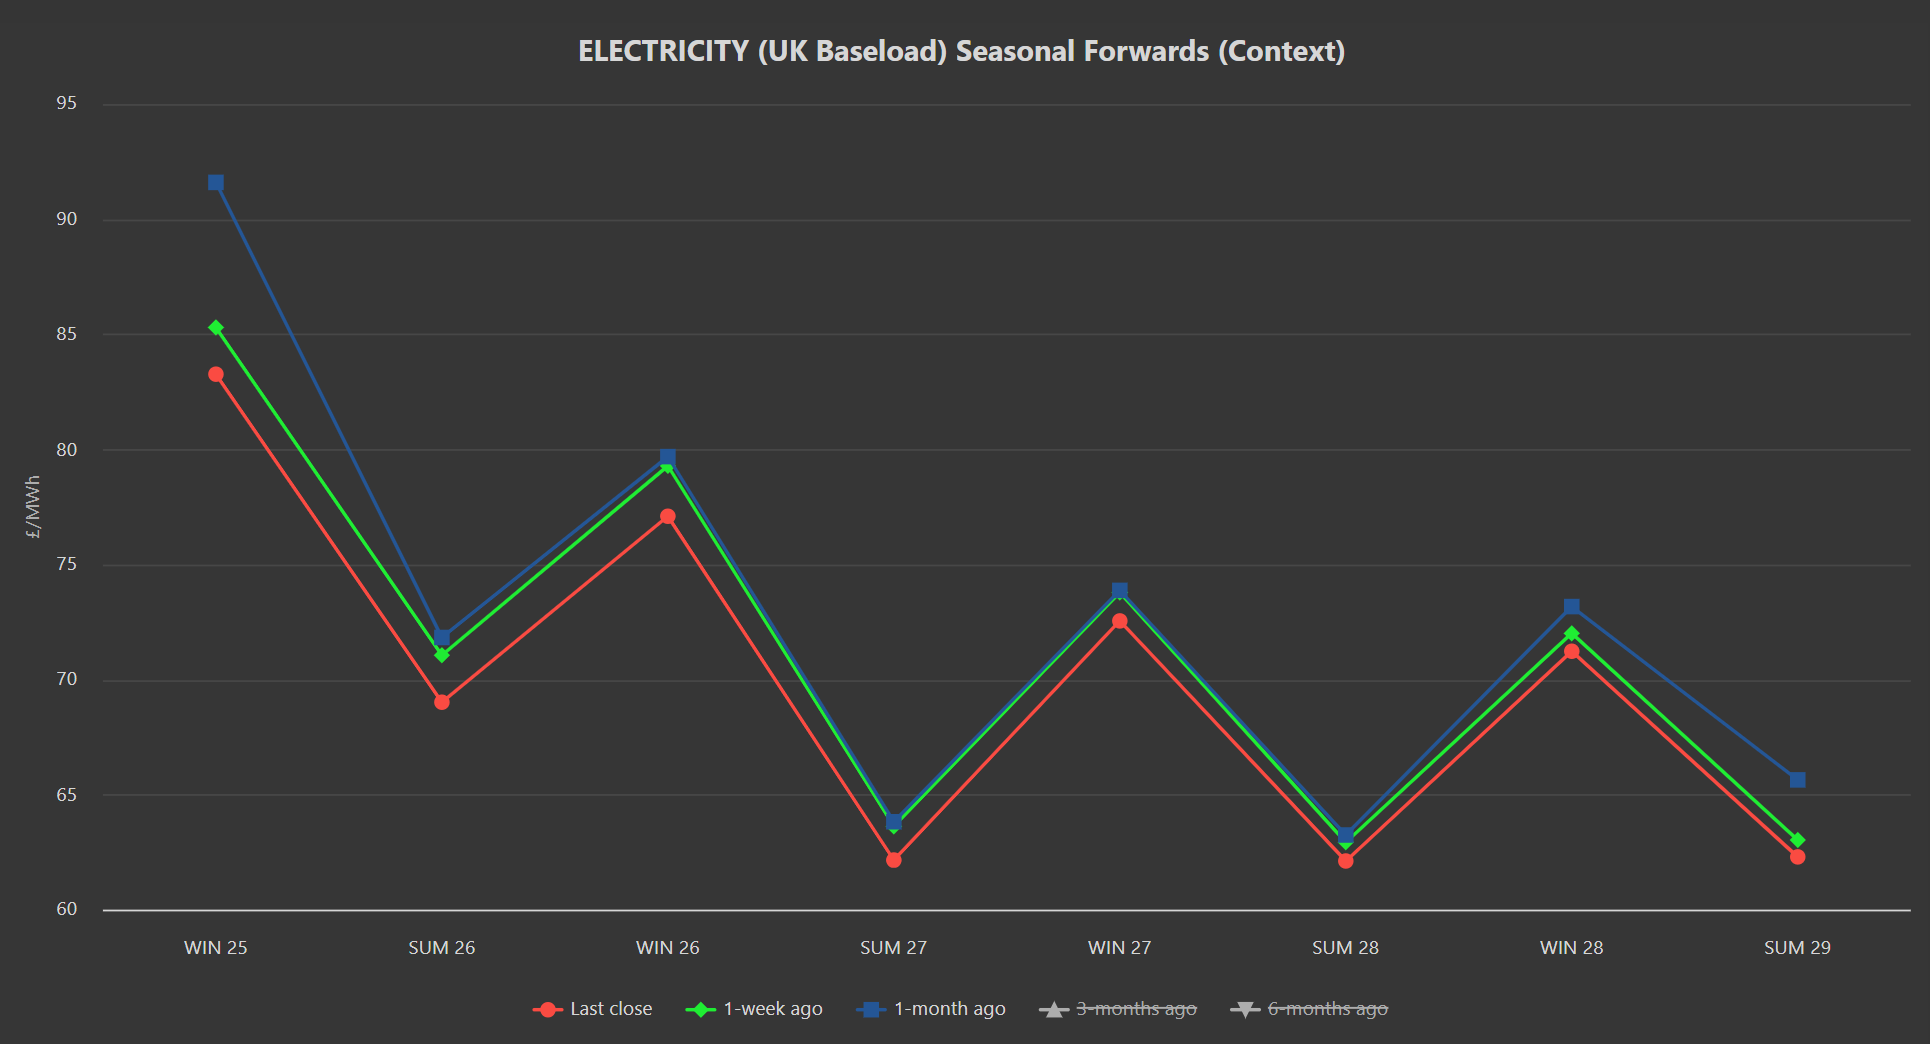
- Seasonal Forwards all the way down the curve are down versus 1-week/1-month/3-months ago (please see chart below).
- On the Carbon markets, UKAs reacted bullishly to Trump’s climb-down on reciprocal tariffs (with investment speculators still net long and emissions increasingly developing a correlation with equities).
- Right now, Dec-24 UKAs are back up at £47.90/tn having broken above the upper extremity of a long term bearish trend channel – though confirmed resistance can still be found around £48.80/tn.
- Today’s UK electricity generation mix is a little bullish in nature, with renewables contributing 24%, thermal at 41% (gas and coal) and low carbon at 22% (nuclear and imports).
- So far this month, electricity Day-Ahead averages are on target to achieve £79/mwh (or approx. 7.9p/kwh excluding non-energy).