



Wed, 22nd Apr ’26
GAS
- Markets are balanced this morning, with prices treading water in a tight range above 100p/therm.
- Trump’s latest gambit to extend the ceasefire, pending an agreement being reached, means a resolution is starting to look a bit open-ended.
- Meanwhile, US destroyers continue to arrive in the Middle East loaded with elite combat forces – would Trump risk ordering a ground offensive?
- Traders are left wondering if Trump has an end-game in mind that is informing his behaviour, or if his actions are all off the cuff.
- Is it in Trump’s interests to keep the Strait of Hormuz shut?
- Well, as we’ve mentioned in previous bulletins, the US was the world’s largest exporter of LNG in 2025.
- With the Strait closed, China is bearing the brunt of LNG demand destruction with imports significantly down y-o-y.
- And so, China’s access to LNG is greatly reduced by Trump’s actions – as is their access to oil (45% of China’s imports transit via the Strait)
- Notably, China’s independent “teapot” oil refineries are heavily reliant on discounted Iranian oil, which is also being held-up by Trump’s blockade.
- For the time being then, China is relying almost entirely on strategic reserves to cushion economic shock, though a prolonged closure of the Strait will inevitably threaten mid-to-long term economic stability.
- Does this play into Trump’s hands in advance of the US/China summit next month?
- Interestingly, just a few hours ago, Trump has suggested that the US has apprehended a Chinese ship (sic): “We caught a ship yesterday that had some things on it, which wasn’t very nice — a gift from China, perhaps, I don’t know, I thought I had an understanding with President Xi, but that’s alright.”
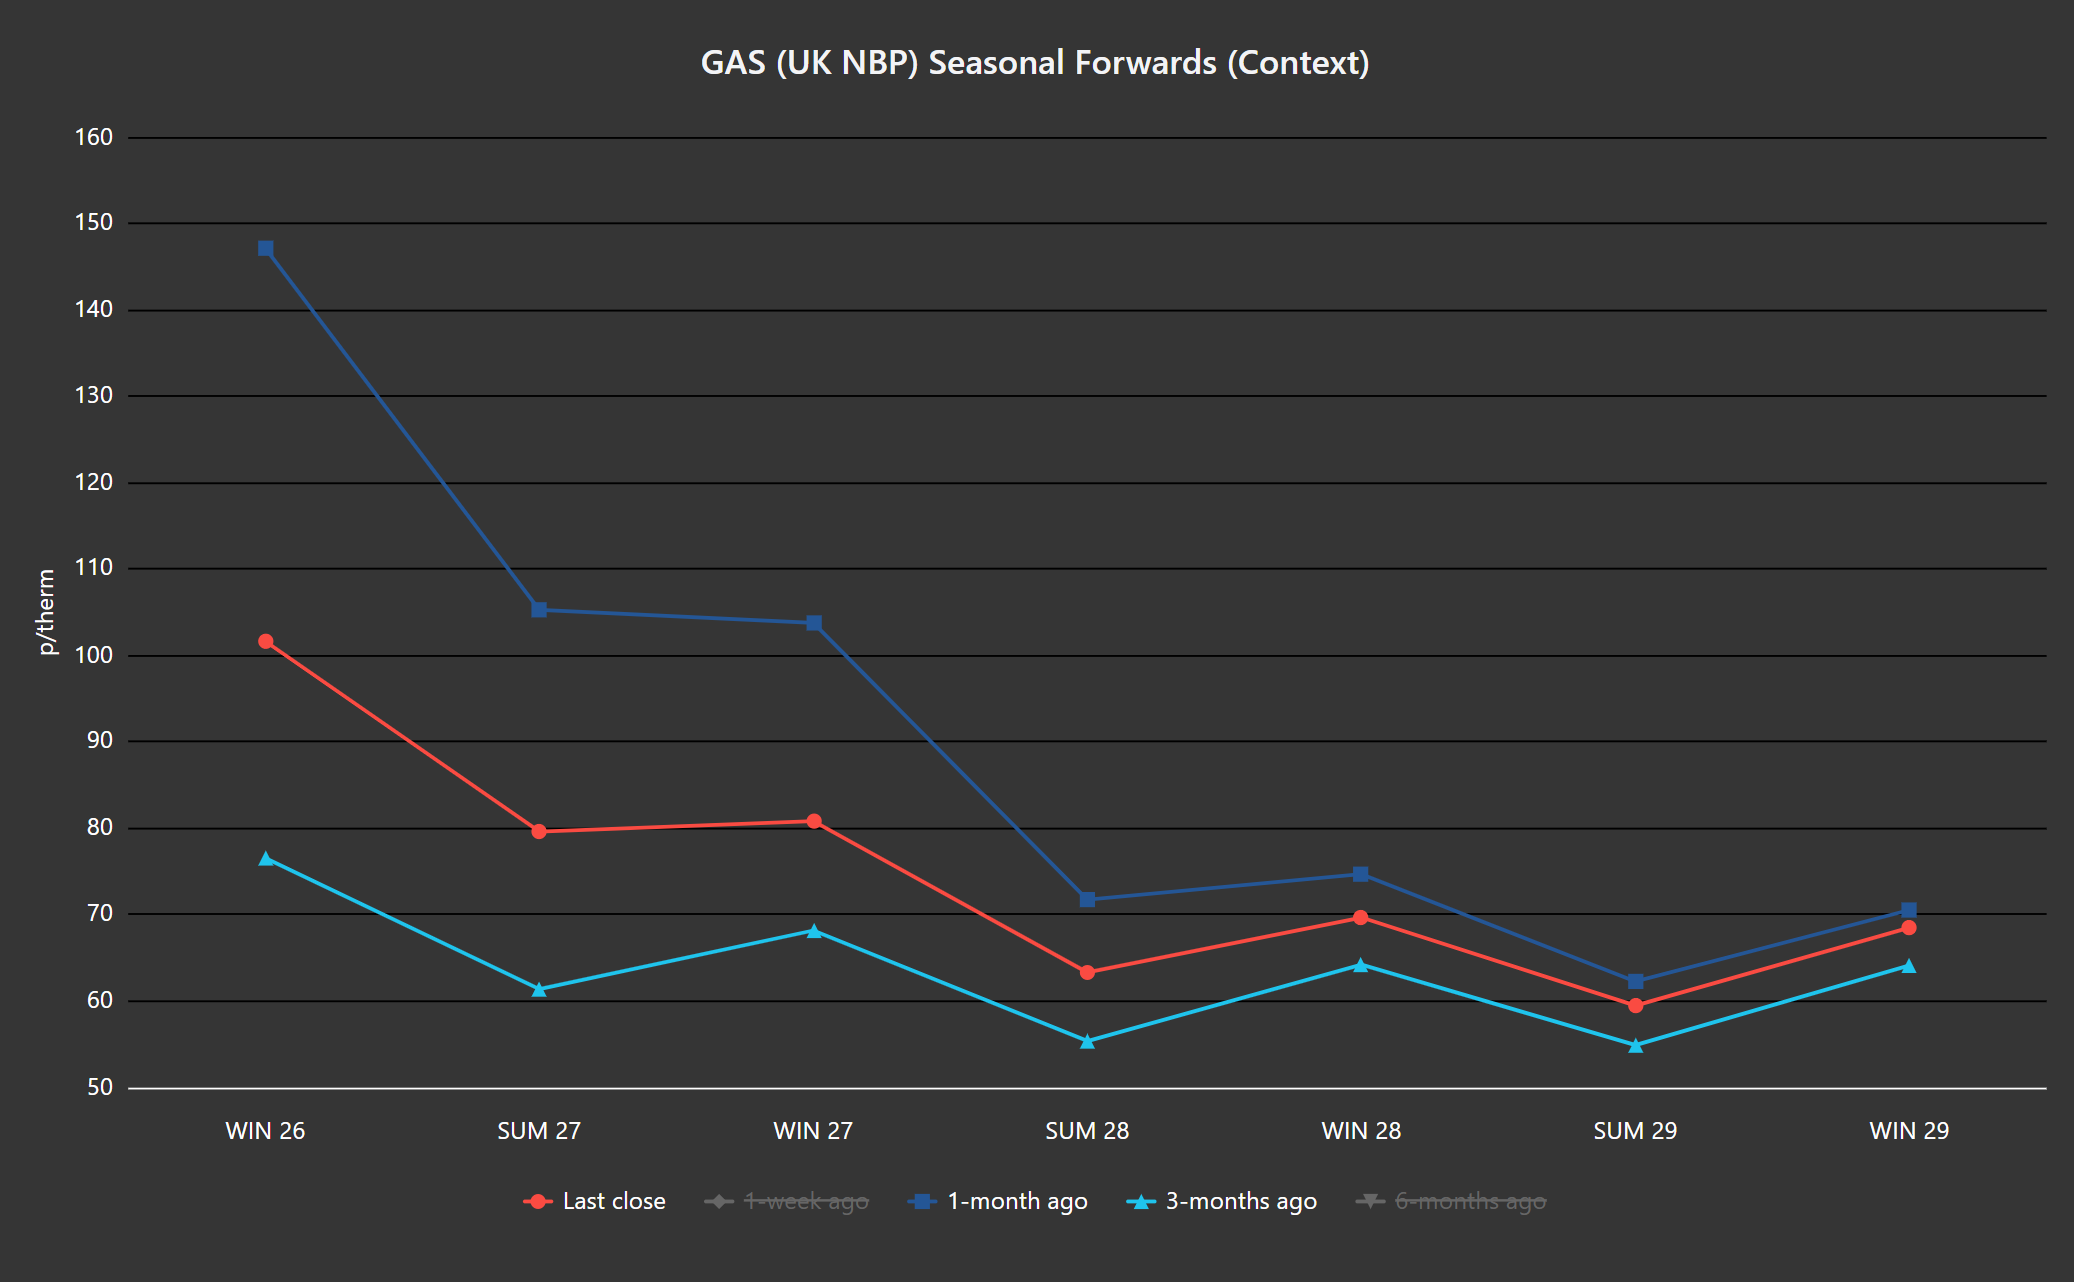
- All noise aside, whilst markets remain elevated versus pre-war levels, they remain down on the month but up versus 3-months ago (please see chart below).
- European storage has turned a corner with the heating season now in the rear-view mirror – so net injections have replaced net withdrawals.
- Storage fullness is at 31% versus the 5-year average of 39% – so not too far off the pace.
- On the trading side, FLEX clients are all but closed-out for May in the hopes that, come June, the Strait will re-open and essential LNG transit will have been restored – thereafter, low summer Day-Ahead prices will resume.
- For now, however, the jury is out pending whether the prevailing impasse can be overcome.
- Monthly Day-Ahead Averages for the month are headed in the right direction – now at 113 p/therm (or 3.9 p/kwh exc. non-gas).
ELECTRICITY & CARBON
- UK electricity prices have been significantly less volatile than gas prices since the US/Israeli offensive began back on 28th Feb.
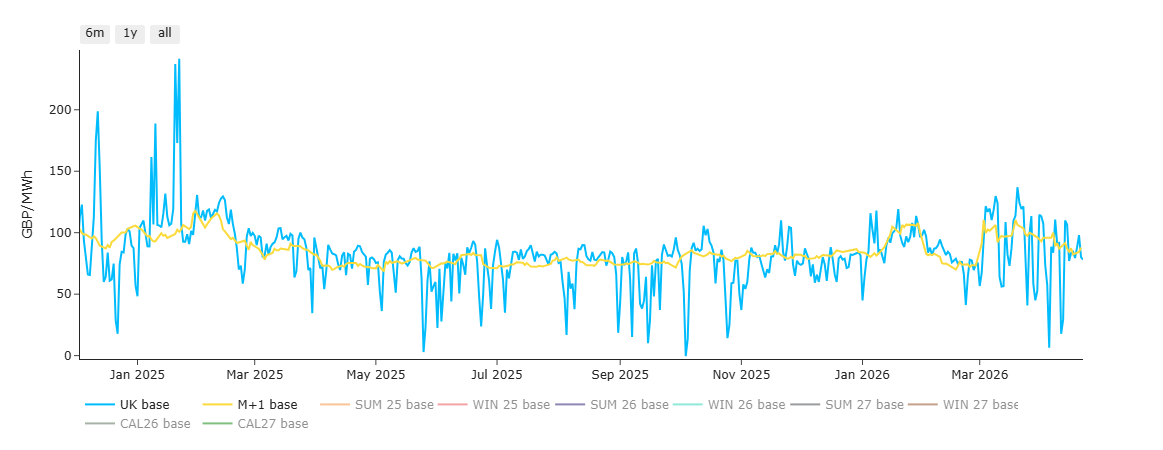
- Nonetheless, as illustrated in the chart below, the percentage variance of Day-Ahead prices (blue line) since the beginning of 2025 to date has been 158% (a low of £28/mwh, a high of £241/mwh) – where as the percentage variance of Month-Ahead (yellow line) for the same period has been only 47% (a low of £71/mwh, a high of £115/mwh) – of course, percentage change numbers would be much higher.
- Suffice as to say, given summer conditions (improved renewables/lower gas for power burn), UK electricity prices remain comfortably below the psychological level of £100/mwh.
- On the trading side, FLEX clients are all but closed-out for May in the hopes that, come June, the Strait will re-open and essential LNG transit will have been restored – thereafter, low summer Day-Ahead prices will resume.
- For now, however, the jury is out pending whether the prevailing impasse can be overcome.
- On the Carbon side of things, Dec-26 UKA delivery began the conflict heavily correlated to gas markets – so when gas prices fell, UKAs rose (and vice versa).
- However, given this week’s volatility in UKAs, having fallen £3/tn since yesterday, we increasingly see a correlation with equities/stock-indices.
- At the time of writing, UKA mid-price Dec ’26 delivery is at £47.78/tn (and the spot is at mid-46s).
- Monthly Day-Ahead Averages for UK electricity for the month have fallen again to £88/mwh (or 8.8 p/kwh exc. non-energy).