



Wed, 20th Aug ’25
GAS
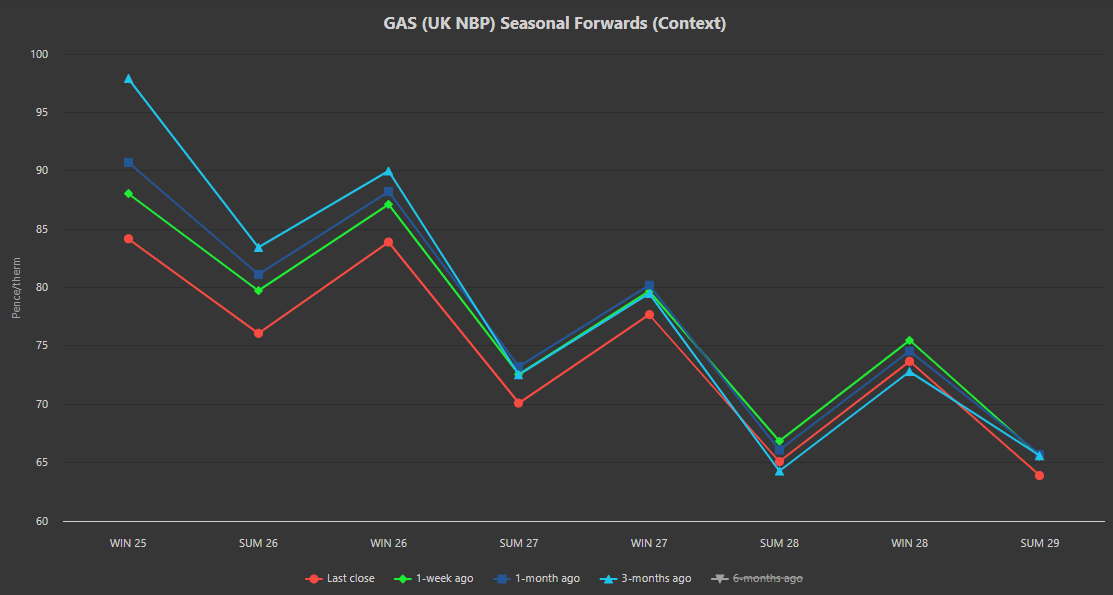
- With many businesses on partial shutdown for the holidays, and trading floors/liquidity enjoying a summer lull, markets have meandered lower still amid benign fundamentals, an increasing likelihood that European storage fullness will hit mandated requirements in time for the heating season (Winter-25), and an underlying optimism amongst market participants that Russian flows may still find their way back into Europe.
- The front 5 Seasons are down on the week/month/3-months – please see chart below.
- Norwegian outages are likely to pick up next month, so this late summer dip has another couple of weeks to develop before focus will shift to Winter-25 storage, and the potential impacts of mid-to-long range weather forecasts.
- Any late buyers of Winter-25 delivery are still advised to get in before the 2nd week of September at the very latest.
- Further to the Russia-US summit (at which Trump seemed to concede advantage to Putin), the subsequent meeting between the US, Ukraine and various other European leaders has ‘security guarantees’ at the core of negotiations.
- Ukraine is looking to ensure its security from Russia going forward (presumably in exchange for accepting Russia’s permanent annexation of certain territories), whilst Europe strains to remain relevant.
- It remains to be seen if Ukraine will get some land back as part of a wider deal.
- Monthly Day-Ahead averages for the month so far are at 78p/therm or 2.65p/kwh (all but unchanged from the start of the month, reflecting very low-short term risk).
ELECTRICITY & CARBON
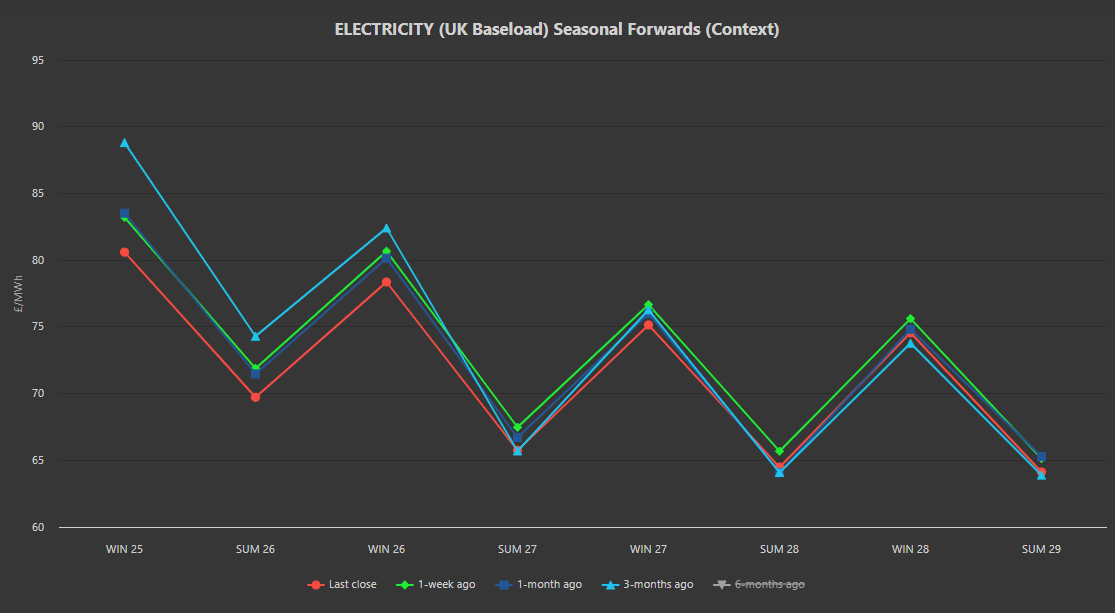
- The front 5 Seasons are down on the week/month/3-months – please see chart below.
- On the Carbon side of things, UKAs are increasingly correlated to EUAs (following the “common understanding” reached between the UK/Europe to link emissions markets at the UK-EU summit in London on 19th May).
- Dec ’25 UKA benchmark prices are at £50.32/tn on the mid-price, and are threatening to fall further having broken below well-established support levels.
- Today’s UK electricity generation mix is neutral in nature – specifically, renewables are contributing 35%, thermal at 29% (gas and coal) and low carbon at 18% (nuclear and imports).
- Monthly Day-Ahead averages for the month so far are at £70/mwh (or 7p/kwh exc non-energy).