



Wed, 17th Jan ’24
GAS
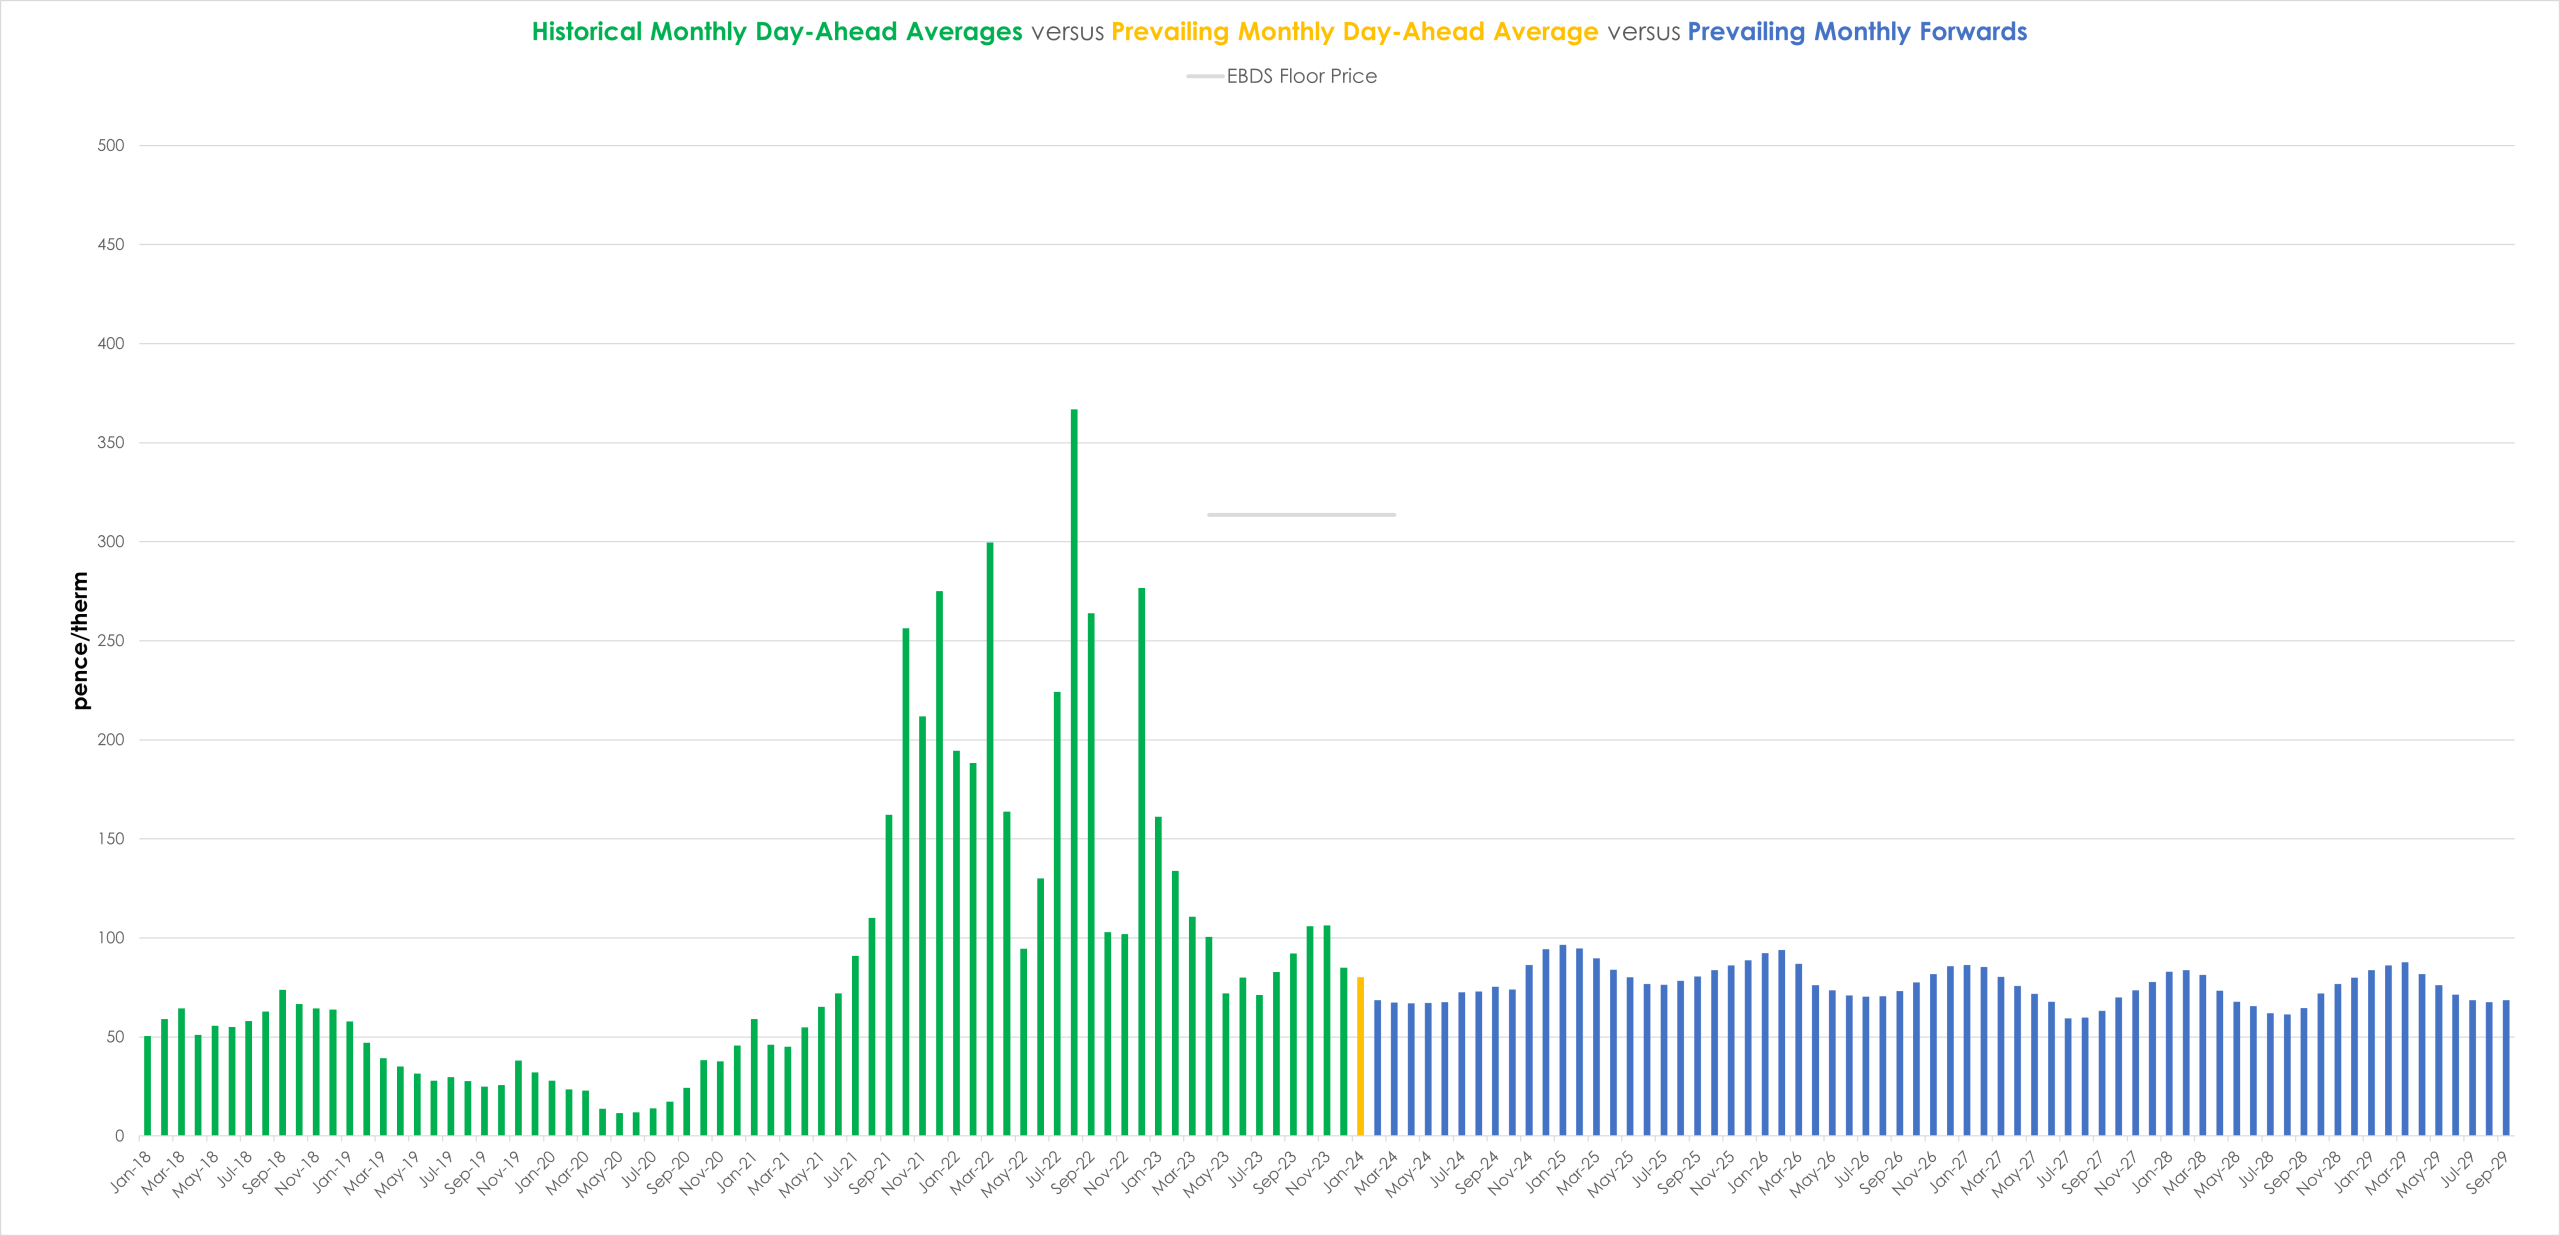
- Notably, near-term delivery prices are now below those being offered for Summer-24 – despite the fact that we’re still in the thick of winter conditioning… (see chart)
- In short, prices are on the slide – both near- and far-term delivery.
- Prices opened down verus yesterday’s close – notwithstanding soaring demand caused by the cold spell.
- UK consumption is circa. 25% above seasonal average but the UK system was still long (supply outstripping demand).
- Norwegian flows remain at capacity and LNG arrivals are in rude health – offsetting any inevitable storage withdrawals.
- Whilst it’s freezing right now, conditions are expected to warm up by the weekend.
- Consensus is building that Europe will reach the end of Winter-23 with still over 50% of storage left in the tank.
- Monthly Day-Ahead averages are on target this month to achieve 80p/therm (or 2.7p/kwh).
ELECTRICITY
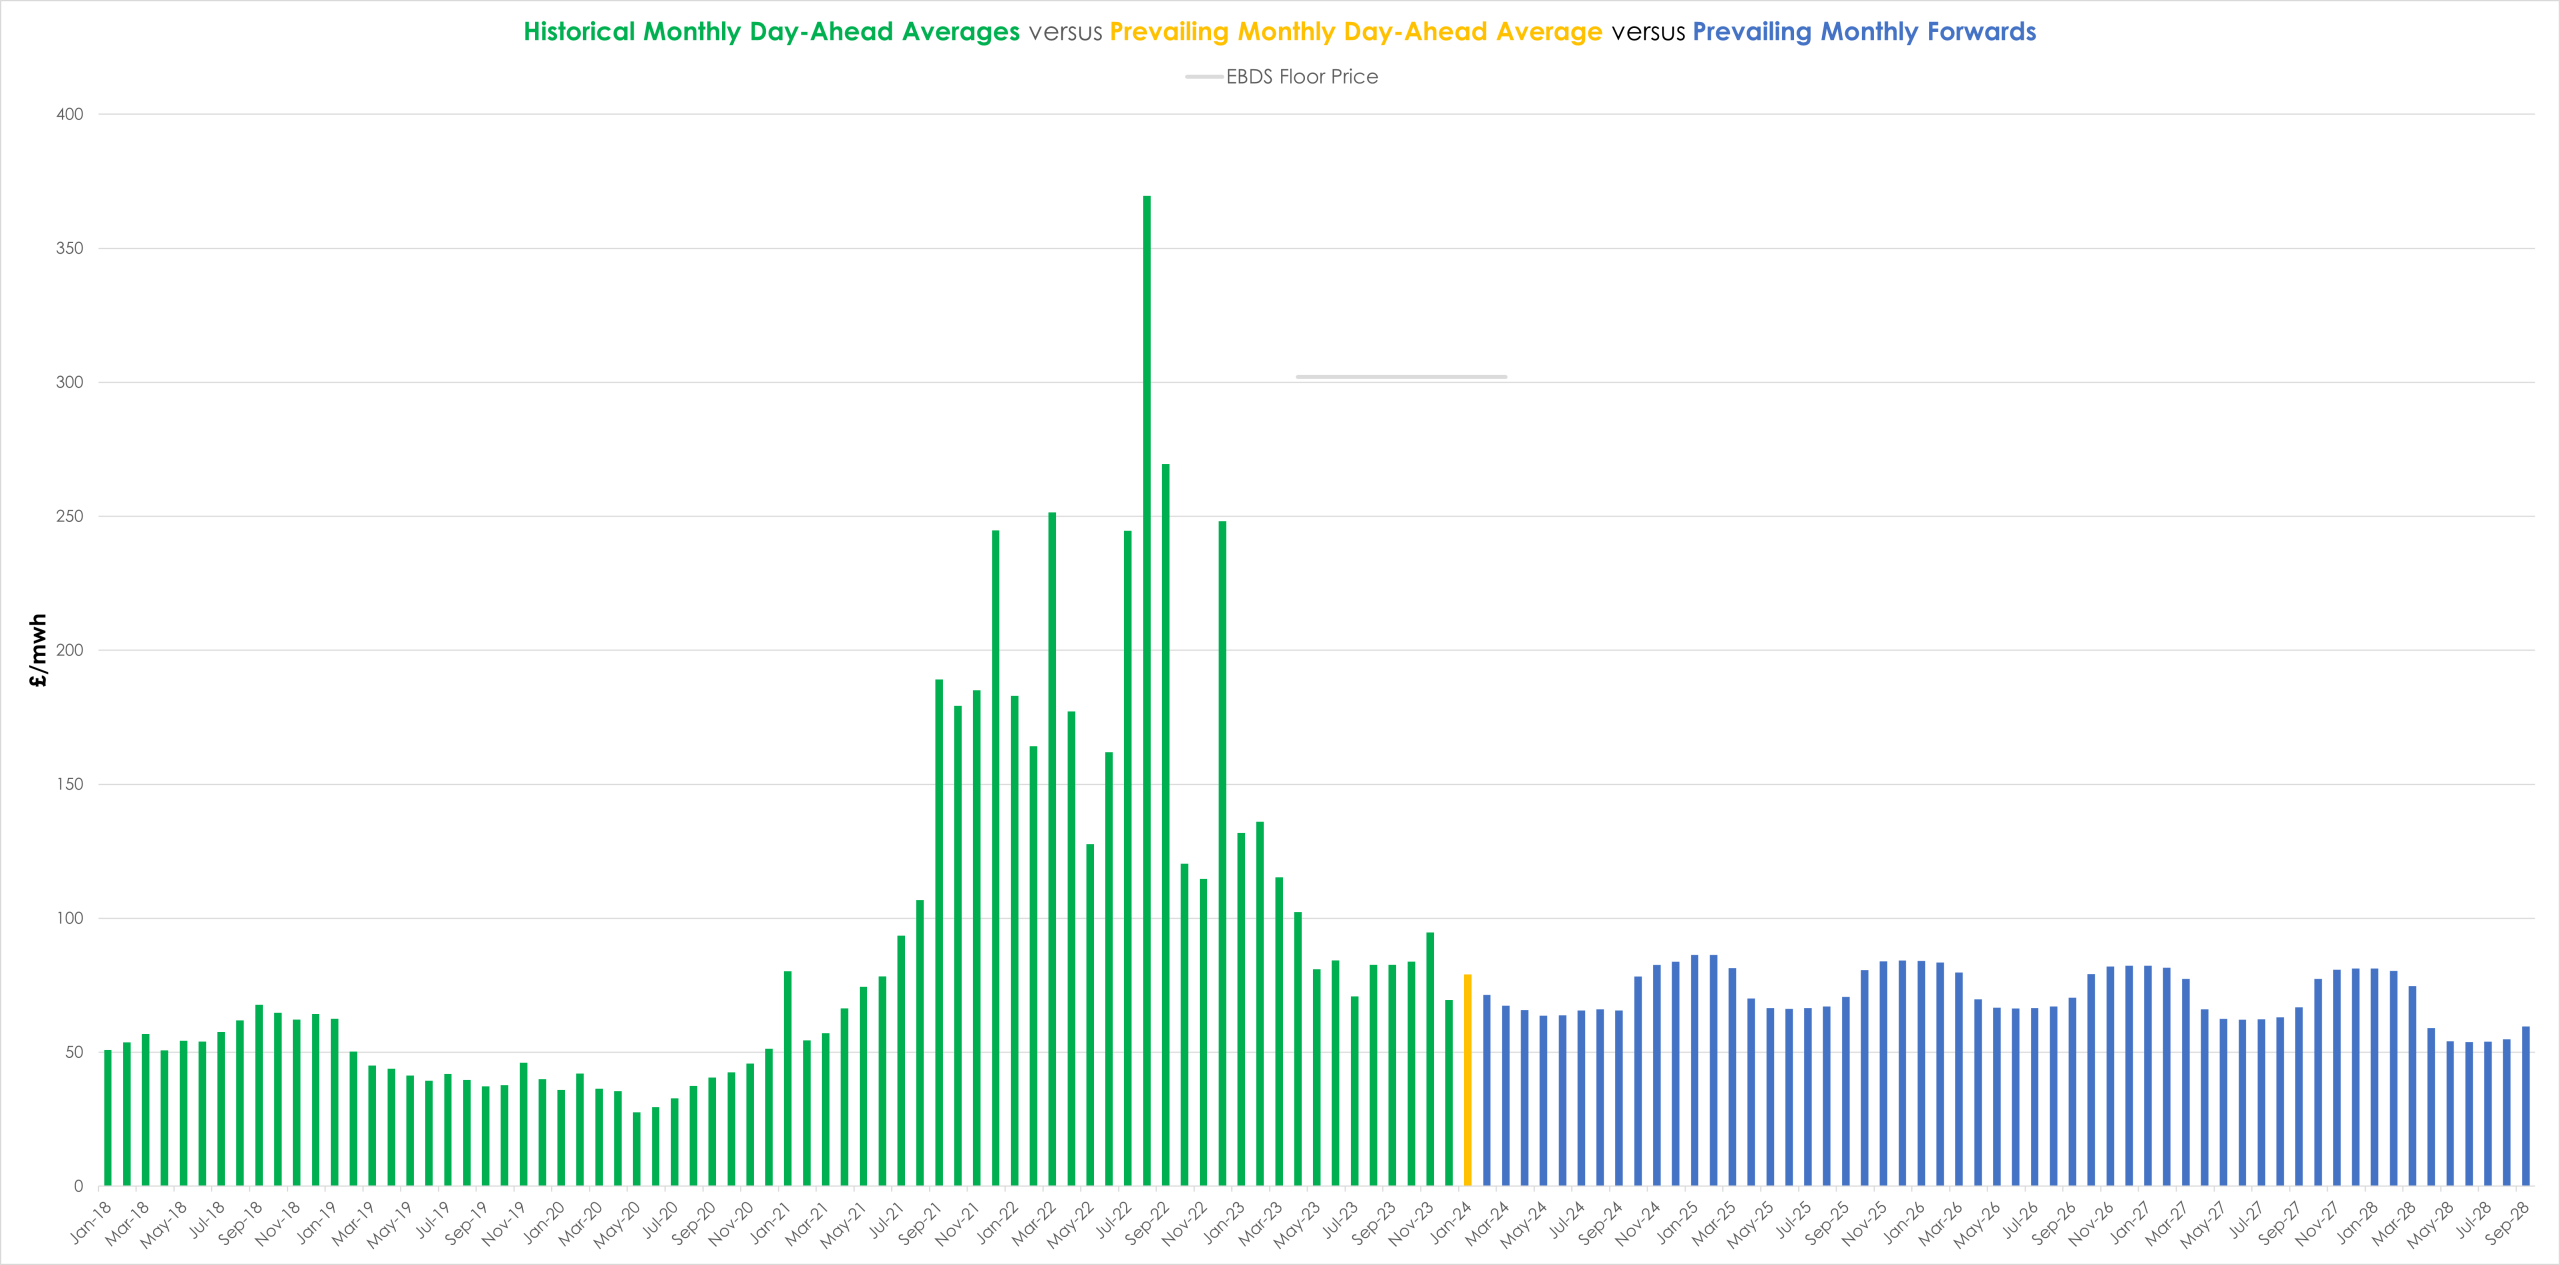
- Electricity is following the gas market down with ALL periods of delivery well-under £100/mwh (see chart).
- Looking to the continent, far-term delivery prices failed to sustain any meaninful rebound as participants eye the looming bearish fundamentals of strong renewables output and temperatures rising above seasonal norms.
- Meanwhile, structural demand remains very low and French nuclear availability is consistently strong (& outages nowhere to be seen).
- Back in the UK, our generation mix is actually bullish at 57% fossil fuels (inc. 3% coal).
- Monthly Day-Ahead averages are on target this month to achieve £79/mwh (or 7.9p/kwh).