



Wed, 13th May ’26
GAS
- All eyes are the Trump/Xi summit in China this week.
- Hopes persist that China will, in some way, help the US to bring the impasse with Iran to an end.
- Despite the ongoing closure of the Strait of Hormuz, natural gas is still way cheaper versus the 2022 Russia crisis.
- This is primarily due to a significantly reduced EU reliance on Gulf exports, as well as Asia’s willingness to pivot to renewables & coal in the face of shortages.
- But as spring temperatures make way for deeper summer conditions, demand across Asia for HVAC will likely increase, and panic stations could set in.
- Benchmark Brent Crude is at $109 – so around 10% down versus this week’s highs.
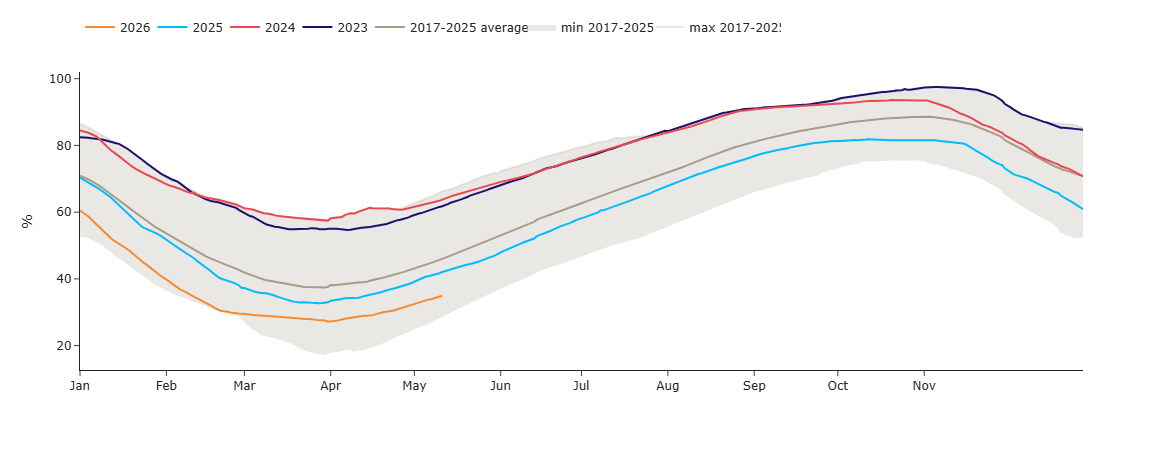
- European storage is at 36% versus the 5-year average of 44% – so inventories are rising slowly but surely, amid thankfully low demand and solid renewables outputs (please see Europe Gas Stock Fullness Rates below).
- On the trading side, the immediate challenge facing some FLEX clients is June delivery – traders will be looking to buy dips as the month progresses (please watch this space).
- Monthly Day-Ahead Averages for the month so far are holding steady at 112p/therm (or 3.82 p/kwh exc. non-gas).
ELECTRICITY & CARBON
- UK electricity prices have been significantly less volatile than gas prices since the US/Israeli offensive began back on 28th Feb.
- Suffice as to say, given summer conditions (improved renewables/lower gas for power burn), UK electricity prices remain below the psychological level of £100/mwh (in the main).
- Today’s UK electricity generation mix is bearish in nature – specifically, renewables are contributing 51%, thermal at 13% (gas and coal) and low carbon at 21% (nuclear and imports).
- On the trading side, the immediate challenge facing some FLEX clients is June delivery – traders will be looking to buy dips as the month progresses (please watch this space).
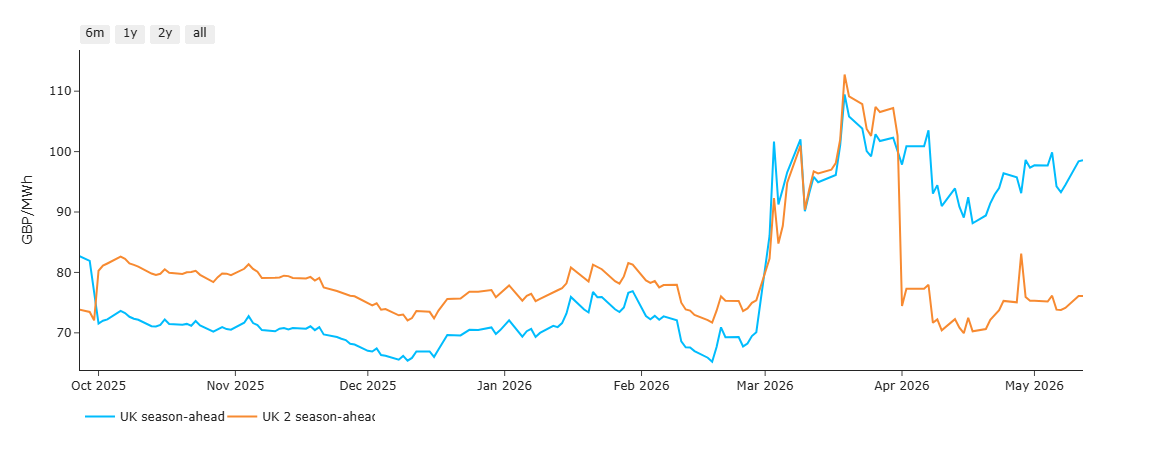
- The chart below details UK electricity Season-Ahead prices (blue line) versus 2-Seasons-Ahead prices (orange line).
- By way of explanation, at the outset of any respective summer (beginning 1st April) or winter (beginning 1st October), one would expect for the lines to re-cross to reflect higher priced winters than summers (as is the traditional shape).
- Notably (and anomalously), on 28th Feb when the US/Israeli offensive began, the two lines diverged and spiked northwards – reflecting short-term panic that closure of the Strait of Hormuz would mean high prices indefinitely.
- Thereafter, beginning 1st April, normal price-action resumed and, as you’d expect during the summer months, the orange line is back comfortably below the blue line – reflecting an underlying belief amongst market participants that prevailing geopolitical impacts will not affect Summer-27 (but Winter-26 is looking shaky).
- On the Carbon side of things, Dec-26 UKA delivery began the conflict heavily correlated to gas markets.
- However, correlation has now seemingly shifted to equities, which continue to enjoy a strong, tech-led rally.
- At the time of writing, UKA mid-price Dec ’26 delivery is at £51.59/tn (and the spot is at early-50s).
- Monthly Day-Ahead Averages for UK electricity for May so far are holding steady at £102/mwh (or 10.2 p/kwh exc. non-energy).