



Wed, 10th Apr ’24
GAS
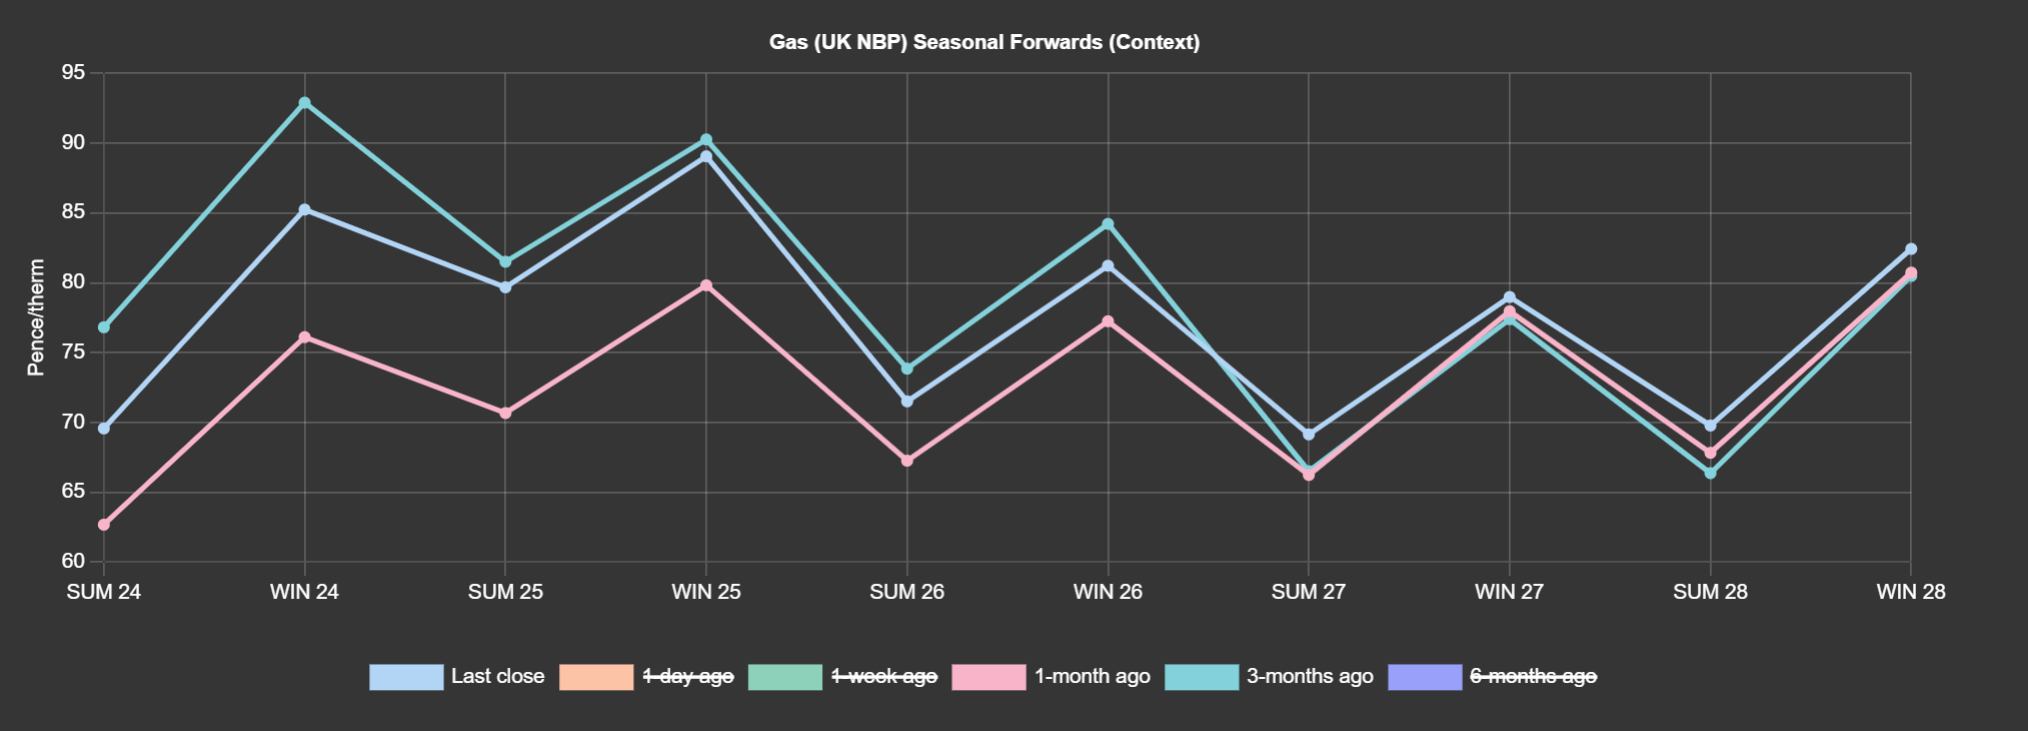
- Liquidity is thin and spreads between Bids & Offers are wider than usual – which reflects quiet, spiky markets.
- In these conditions, it’s easy for low volume trades to move the markets more than they ordinarily would.
- As such, we’ve seen an uptick to start the week, though finding reasons to support increased contract values is tricky.
- Seasonal Forwards are up on the month, but down versus 3-months (see chart).
- Technically speaking, lower demand is forecast into the weekend limiting heating demand as temperatures rise.
- Wind outputs are also increasing, and the warm windy conditions suggest the system balance should be nice and loose – with injections and exports required to facilitate system balance (i.e., a surplus of supply that can be stored or exported).
- Supply from Norway has increased with Asgard fields due back online today, with flows expected to be at capacity over the coming days.
- In short, the remainder of the week should be soft to rangebound (notwithstanding unexpected geopolitical shocks) – though prices shouldn’t fall too far considering the temperature drop below seasonal norms expected next week.
- Noise aside, and in the absence of further geopolitical turmoil, it’s likely we’ll see improved value for Winter-24 delivery as the summer progresses.
- Monthly Day-Ahead averages are on target this month to achieve 64p/therm (or 2.2p/kwh).
ELECTRICITY & CARBON
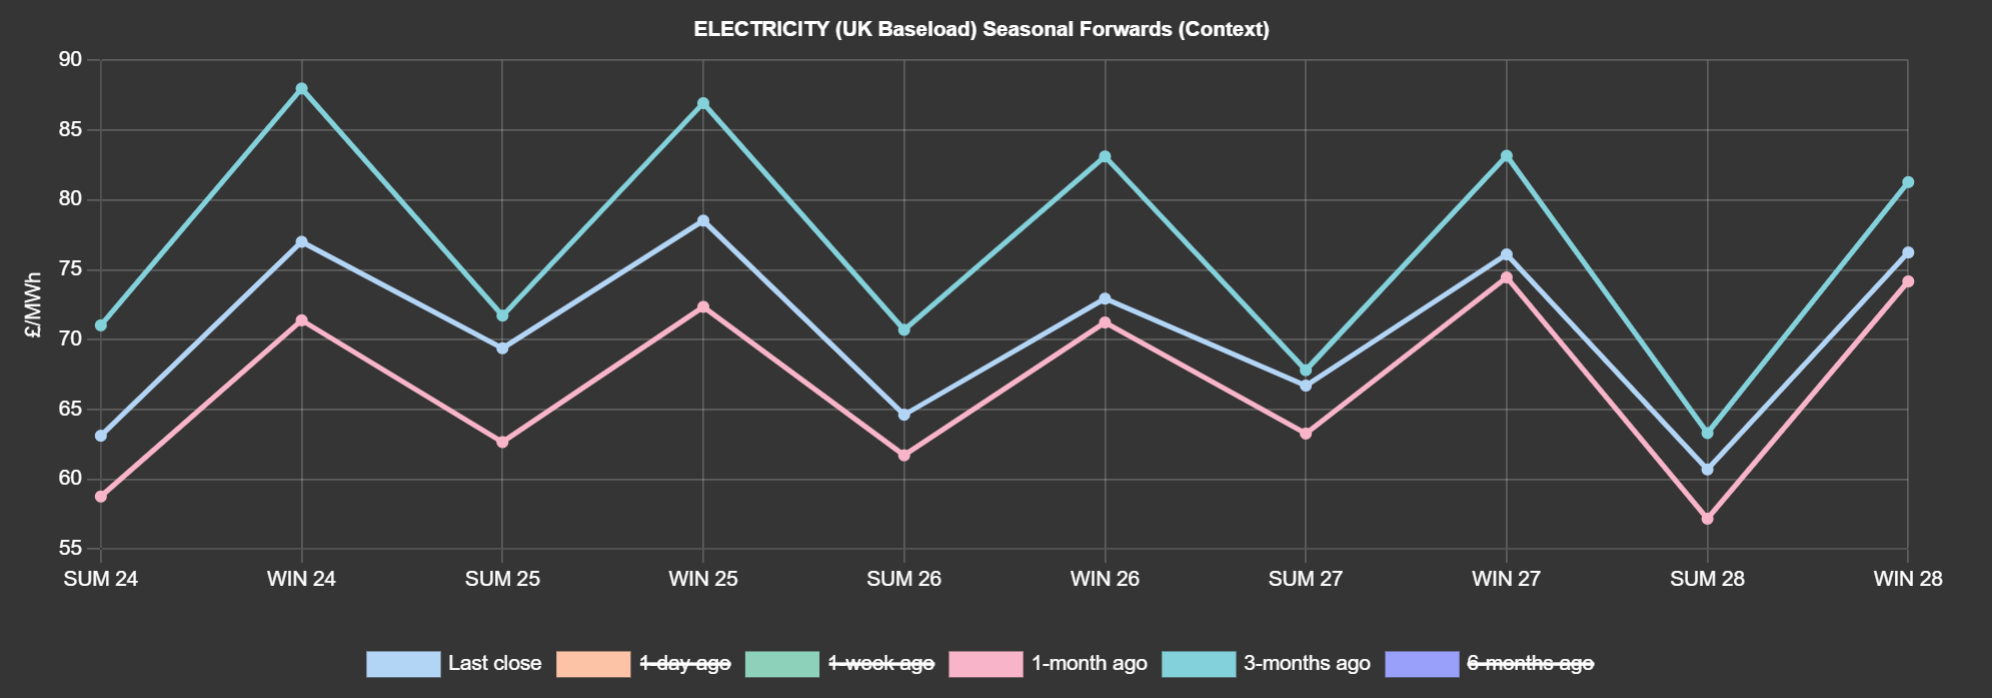
- Looking to the continent, bearish pressure may strengthen again for the second part of the week as temperatures and solar outputs rise.
- Fundamentals remain comfortable with high gas stocks, weak demand and solid renewables generation, limiting any upside scope.
- On the carbon markets, prices tracked the energy complex for most of yesterday but ignored the late recovery of gas prices to instead rise before the session’s close.
- The move came as a surprise to market participants – was the the sudden strength caused by speculators abandoning their bearish bet on the market or simply covering their positions ahead of the COT Commitment of Traders report)?
- It’s difficult to believe that the upward move marked the beginning of a meaningful bullish rally given the still very weak industrial activity and high renewables activity/outputs.
- Dec-24 contracts for UKAs are circa. £35/tn – so relatively unchanged.
- Our electricity generation mix is very bearish in nature today with renewables contributing 58%, thermal at 5% (gas and coal) and low carbon at 23% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £51/mwh (or 5.1p/kwh).