



Tues, 6th Aug ’24
GAS
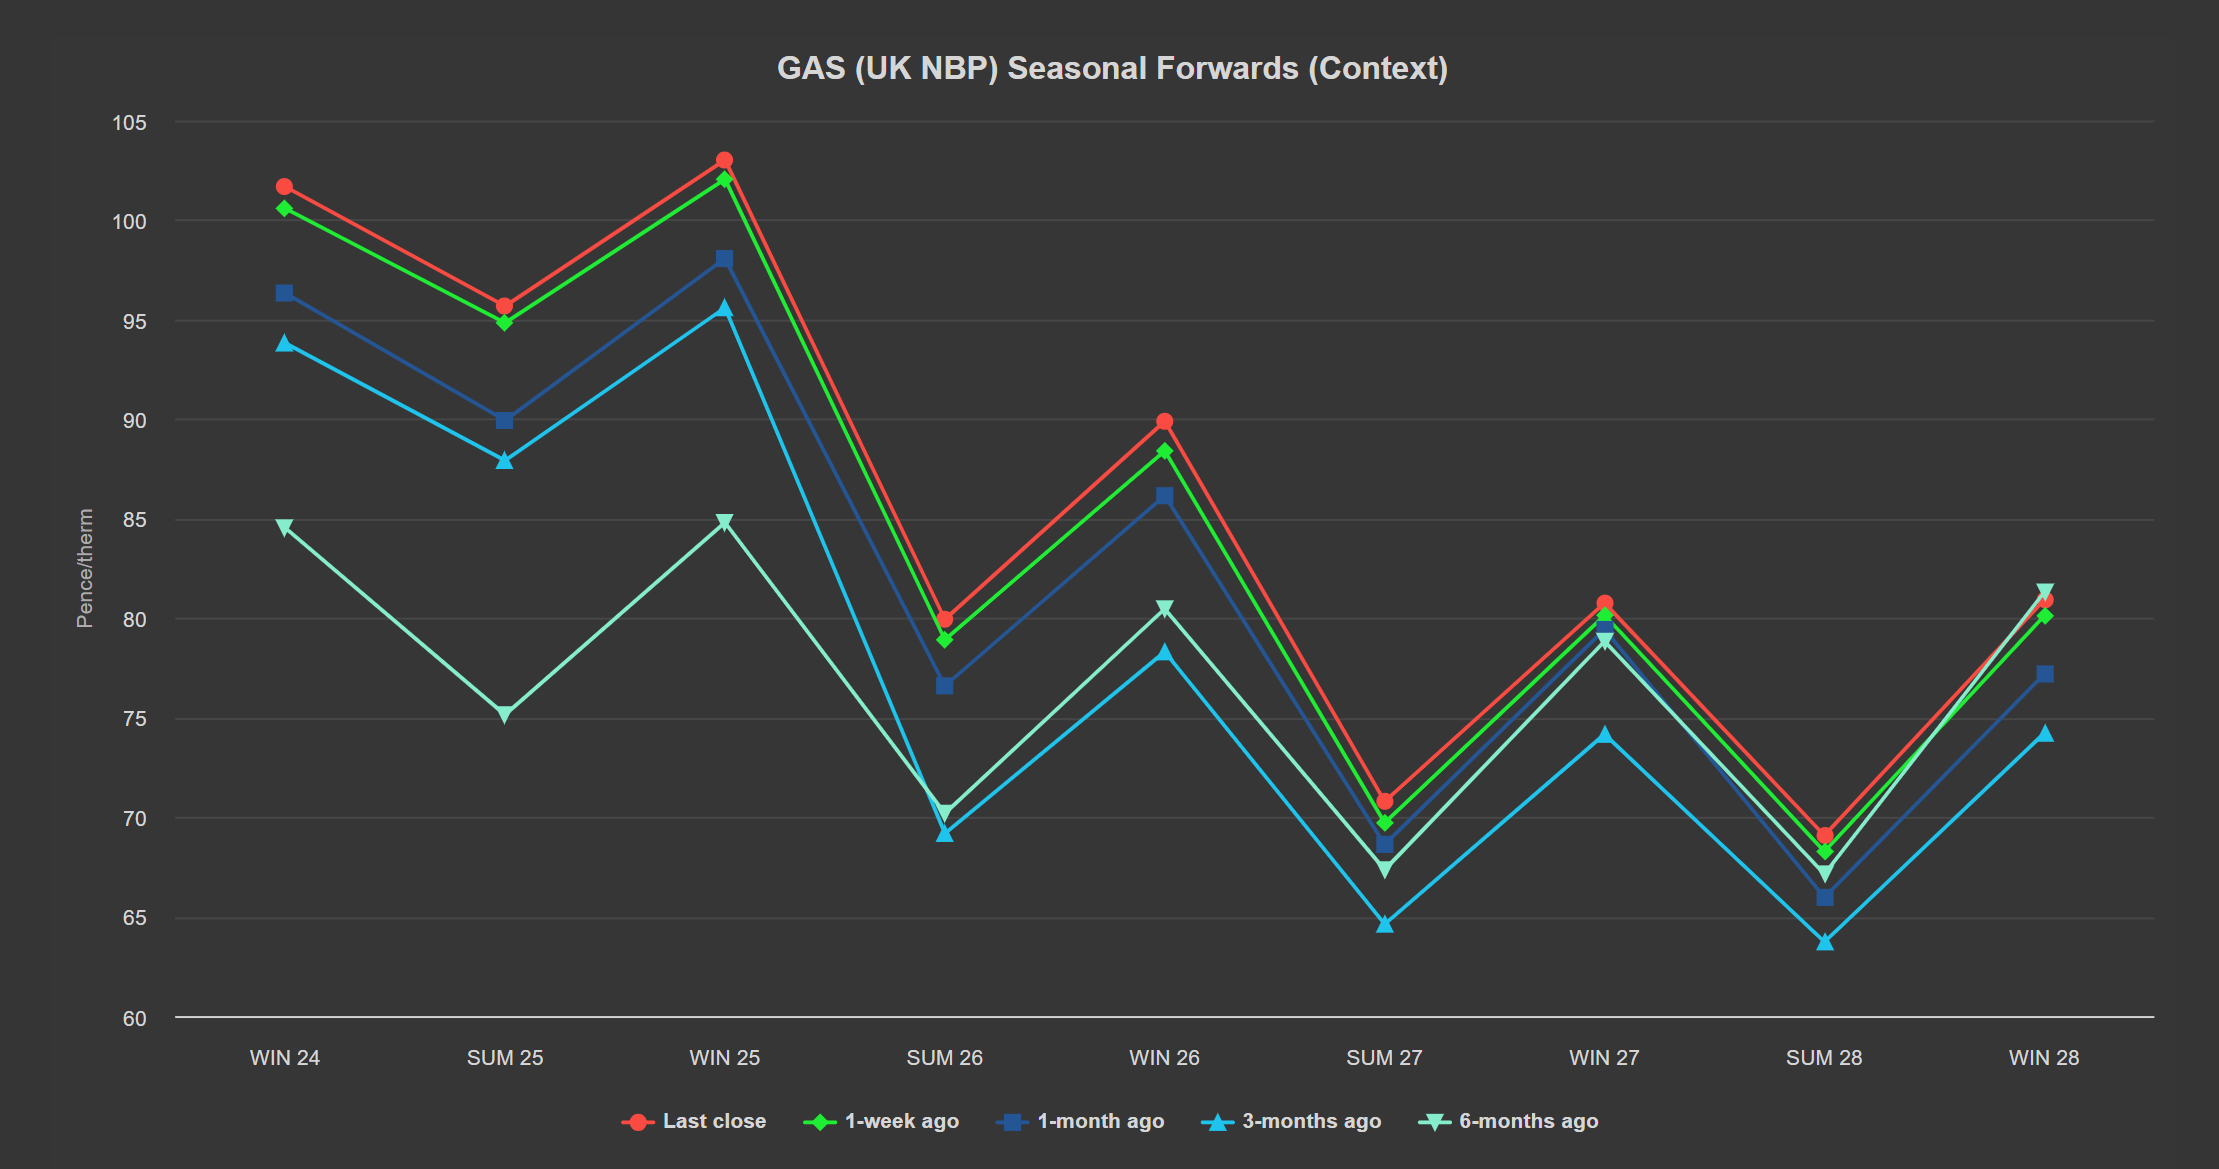
- The see-sawing Summer-24 market is back at the top of its trading range – closing yesterday up versus 1-week ago/1-month ago/3-months ago/6-months ago(see chart below).
- Whilst we witnessed a little bit of sell-off yesterday to mirror a global equity sell-off (in reaction to US jobless claims numbers indicating the world’s largest economy might be headed for a slow-down), markets have found their feet again today.
- Both near- and far-term delivery prices were up at this morning’s open notwithstanding a long UK system (supply outstripping demand forecast).
- Watchful eyes are trained on the Middle East as traders wait for a retaliatory strike by Iran on Israel.
- Higher temperatures around the globe (notably Europe and Asia) have increased cooling demand propping up risk-premiums.
- As a direct consequence of the European heatwave, the projected volume of LNG on European waters waiting for available terminals at which to degasify increased around 8% week-on-week.
- Nonetheless, there are currently no LNG vessels set to land in the UK in the next couple of weeks.
- Over the course of Summer-24 so far, demand has remained low against a backdrop of comfortable supply/storage – as such, replenishing gas stocks has not posed any problems.
- Europe remains on track to achieve 100% storage levels by Winter-24 (early Oct ’24).
- European storage is at 86% fullness versus the 5-year average of 76%.
- On the hedging side, we’re now on the other side of Summer-24 – with 128 days having elapsed, and 56 remaining.
- Clients with open volumes for Winter-24 are now in the minority – with most having opted to close-out Positions given the ongoing geopolitical uncertainties and winter conditions now on the horizon.
- Monthly Day-Ahead averages so far this month are on target to achieve 82p/therm (or circa. 2.8p/kwh excluding non-gas).
ELECTRICITY & CARBON
- On the Carbon markets, EUA continue their bullish rally (correlating with recent gas price rises).
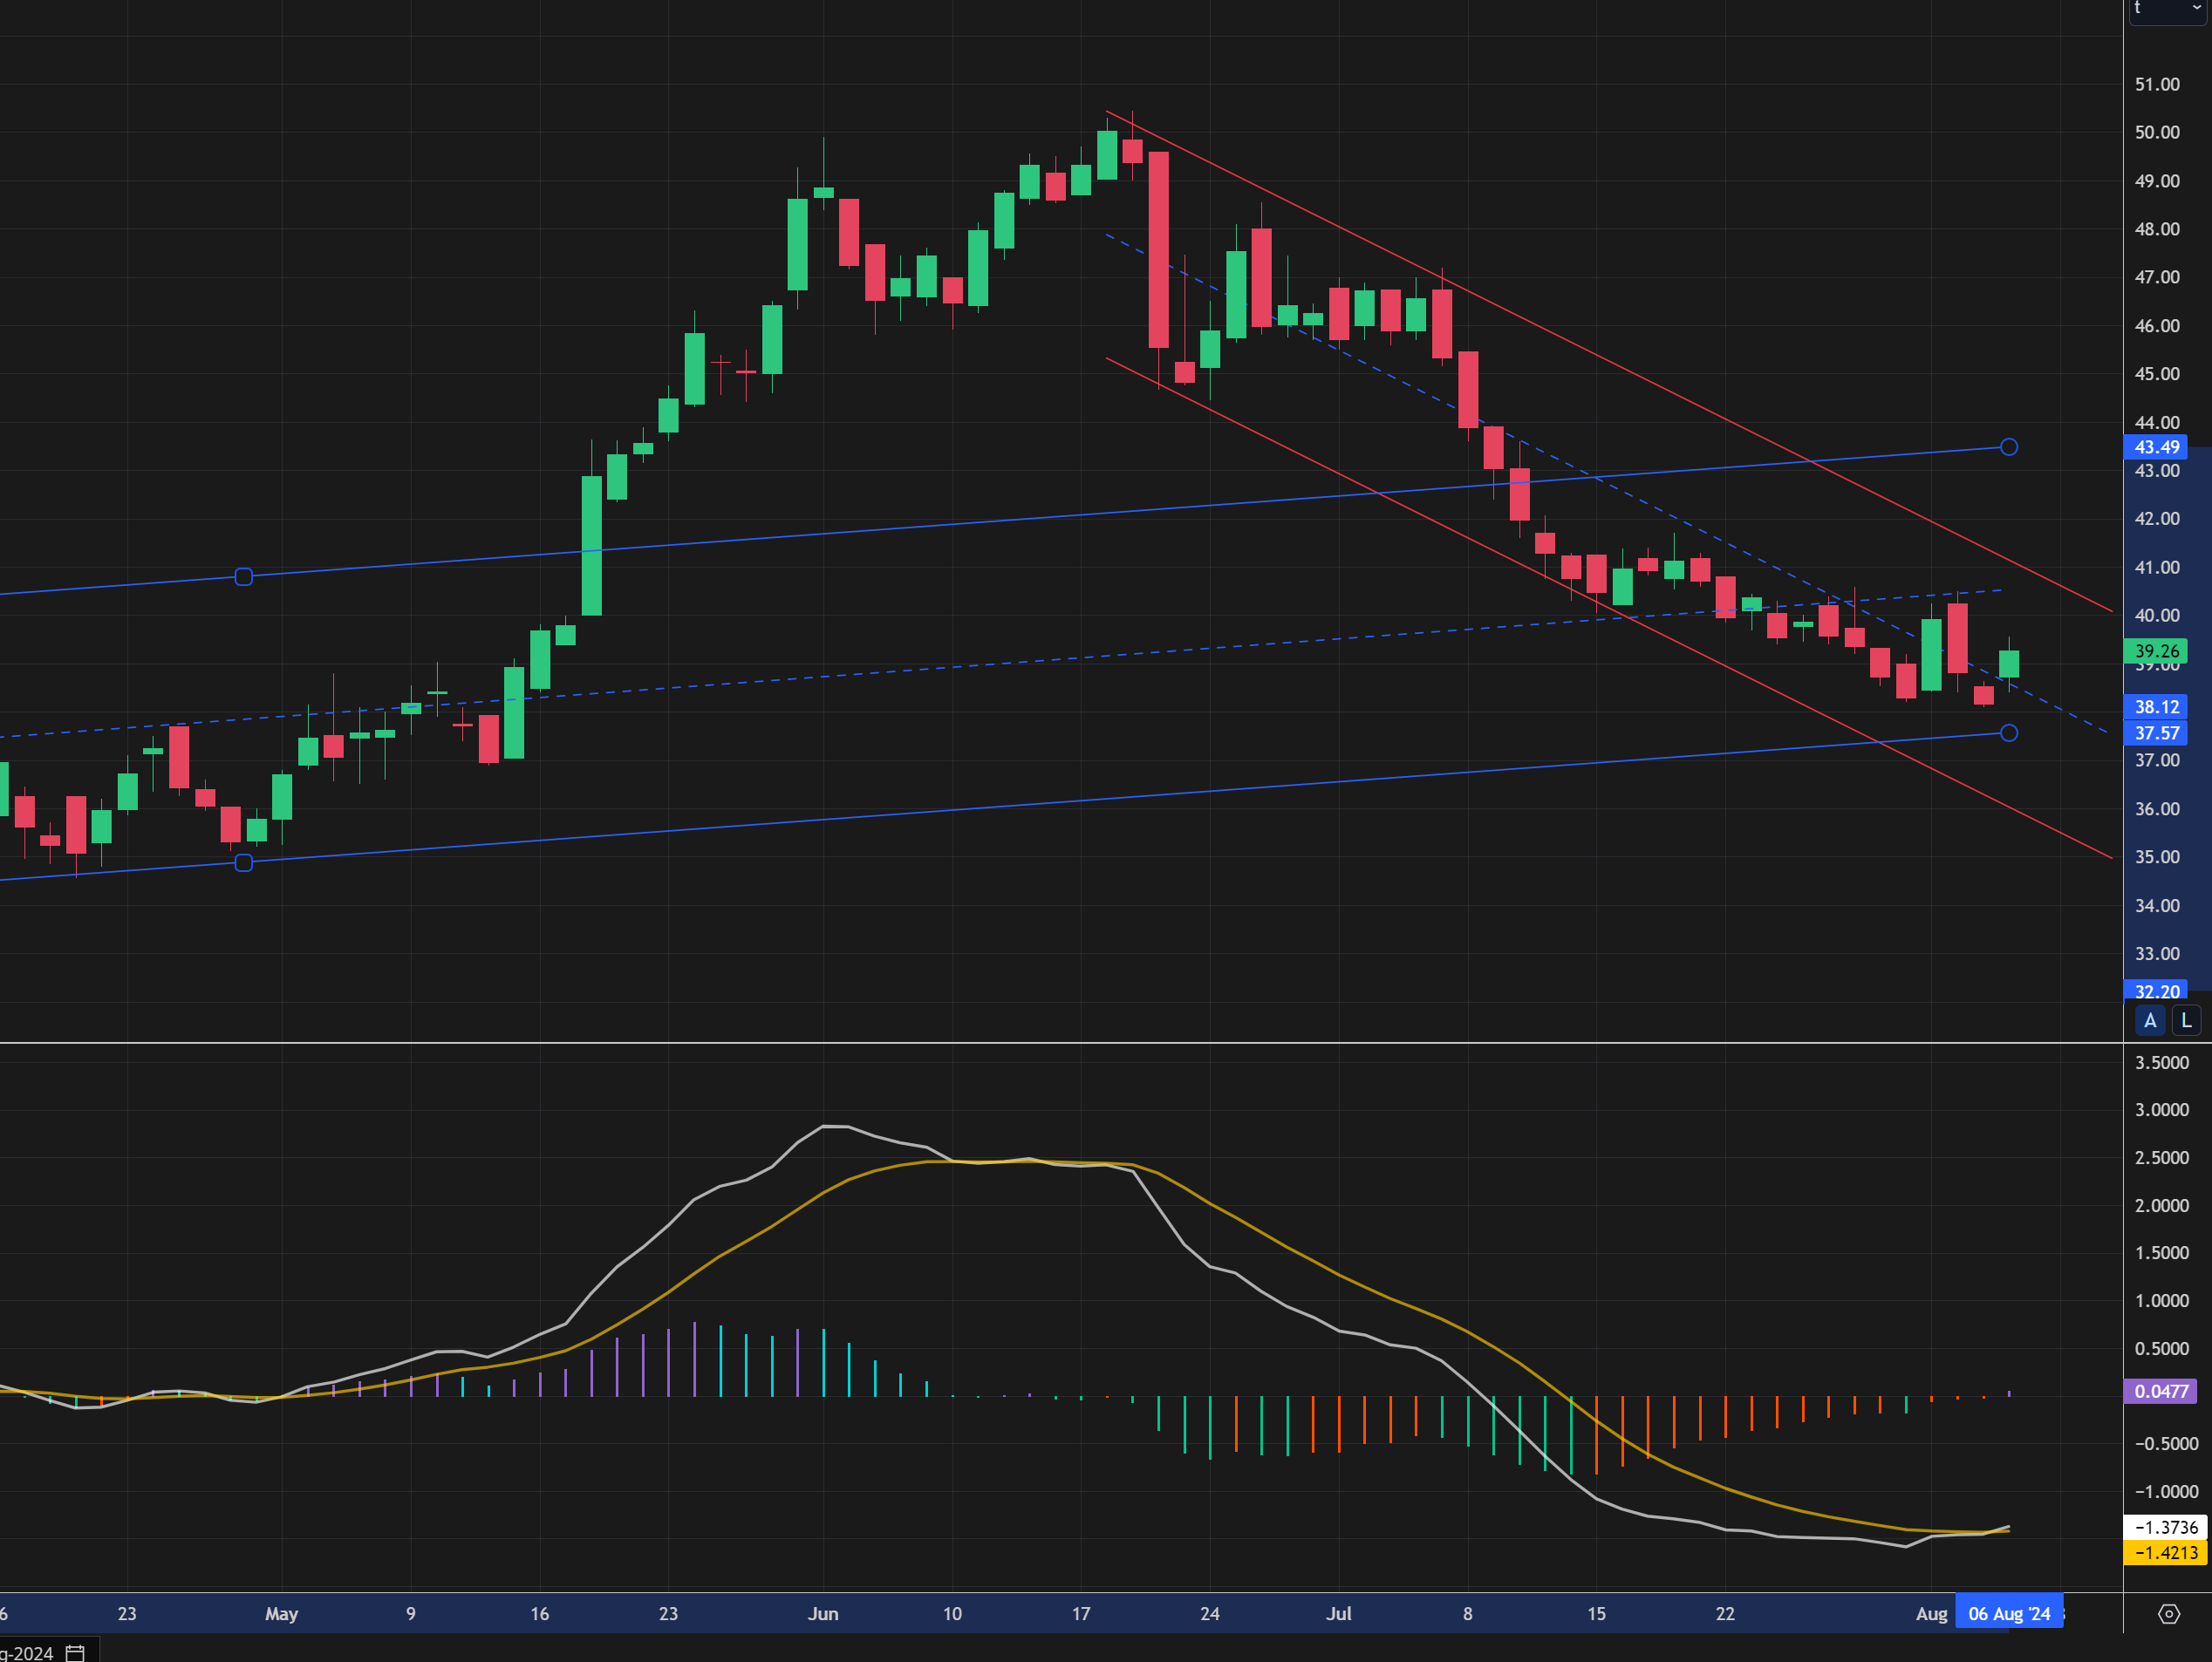
- Back in the UK (and despite EUA’s bullish tone), UKAs (UK Carbon Allowances) have been slow to react – instead almost retesting £38/tn to the downside before being dragged back up by EUAs’ bullish fervour – now trading at circa. £39/tn.
- At the time of writing, UKAs are trading within the confines of a confirmed strong bearish trend channel, and a confirmed weaker bullish trend channel – though £38/tn remains a viable target to the downside (see chart below).
- Our electricity generation mix today is bearish in nature with renewables contributing 46%, thermal at 14% (gas and coal) and low carbon at 29% (nuclear and imports).
- Electricity monthly Day-Ahead averages so far this month are on target to achieve £70/mwh (or approx. 7.0p/kwh excluding non-energy).