



Tues, 30th Jan ’24
GAS
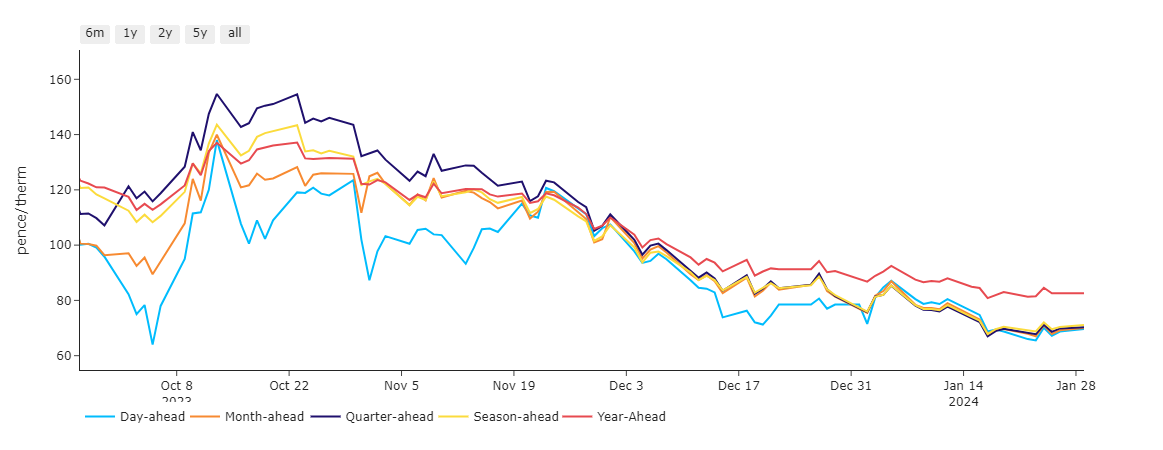
- Day/Month/Quarter/Season-Ahead are at parity, and at circa. 15% discount versus Year-Ahead (see chart) – reflecting low short-term risk (favourable supply/demand dynamics) and higher risk in the mid-term (potential conflict/escalations/insecurity across the Middle East, Ukraine and Taiwan).
- At this morning’s open, prices were marginally down versus yesterday’s close despite a short UK system (demand outstripping supply).
- Nonetheless, demand is still running below seasonal norms with above average seasonal temperatures limiting heating demand, and wind outputs forecast to improve over the coming days (limiting gas-for-power burn).
- Confidence in storage levels pervades underlying sentiment with consensus building that European storage will end Winter-23 with more than 50% still left in the tank.
- The Freeport LNG terminal in Texas expects Train 3 to be out of service for about a month due to an electrical fault.
- Train 3 has the capacity to produce about 0.7 billion cubic feet of LNG daily (equivalent to supplying around 5 million homes).
- China’s property sector is starting to show signs of strain with Evergrande Group’s liquidation having been announced (raising further questions about China’s wider economy and associated demand).
- Favourable weather conditions into early February are expected to keep a lid on any meaningful upside caused by geo-political risk across the Middle East.
- Monthly Day-Ahead averages are on target this month to achieve 75p/therm (or 2.5p/kwh).
ELECTRICITY & CARBON ALLOWANCES
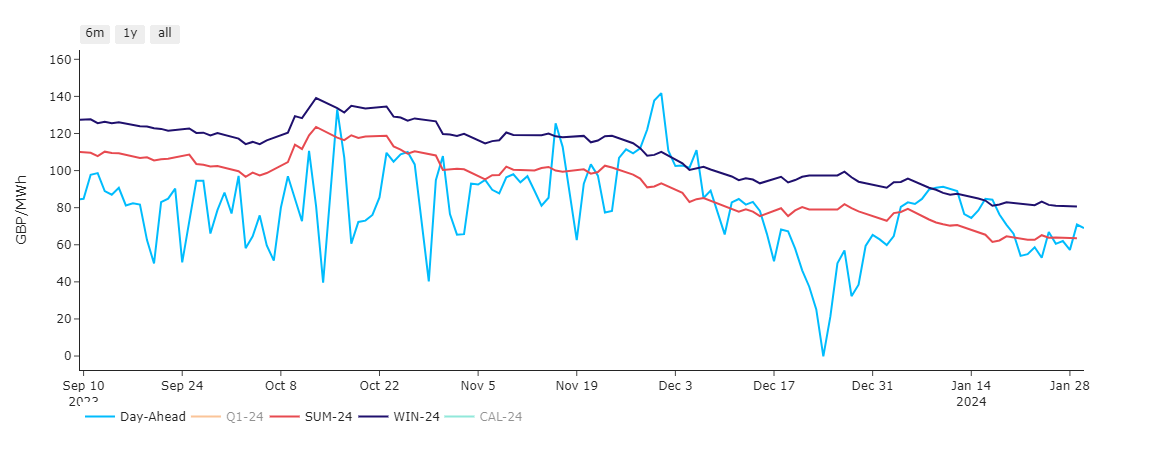
- Day-Ahead is couched between Season/Ahead and 2-Seasons-Ahead (see chart) – reflecting a tight trading range, and prices at a steady equilibrium with Summer-24 now on the horizon.
- Looking to the continent, near-term delivery prices are trading sideways with renewable generation forecast to gradually increase throughout the week.
- A strong pressure gradient over Europe will bring south-westerly flows, enabling wind generation to get close to record levels at the beginning of next week.
- French nuclear generation has been much higher than this time last year, allowing an easing of supply tensions – though due to outages, availability is forecast to drop over the coming weeks.
- On the carbon market, market participants seem confident that a retest of €61/tonne is on the cards.
- UKAs (UK mandatory carbon allowances) last year traded at an average discount of more than 40% to their European forerunner and counterpart (EUAs) – as such, market participants are asking for structural change to close the gap…
- Back in the UK, our generation mix at the time of writing is increasingly neutral with 43% gas-for-power burn and 23% renewables.
- UK electricity monthly Day-Ahead averages are on target this month to achieve £72/mwh (or 7.2p/kwh).