



Tues, 27th Feb ’24
GAS
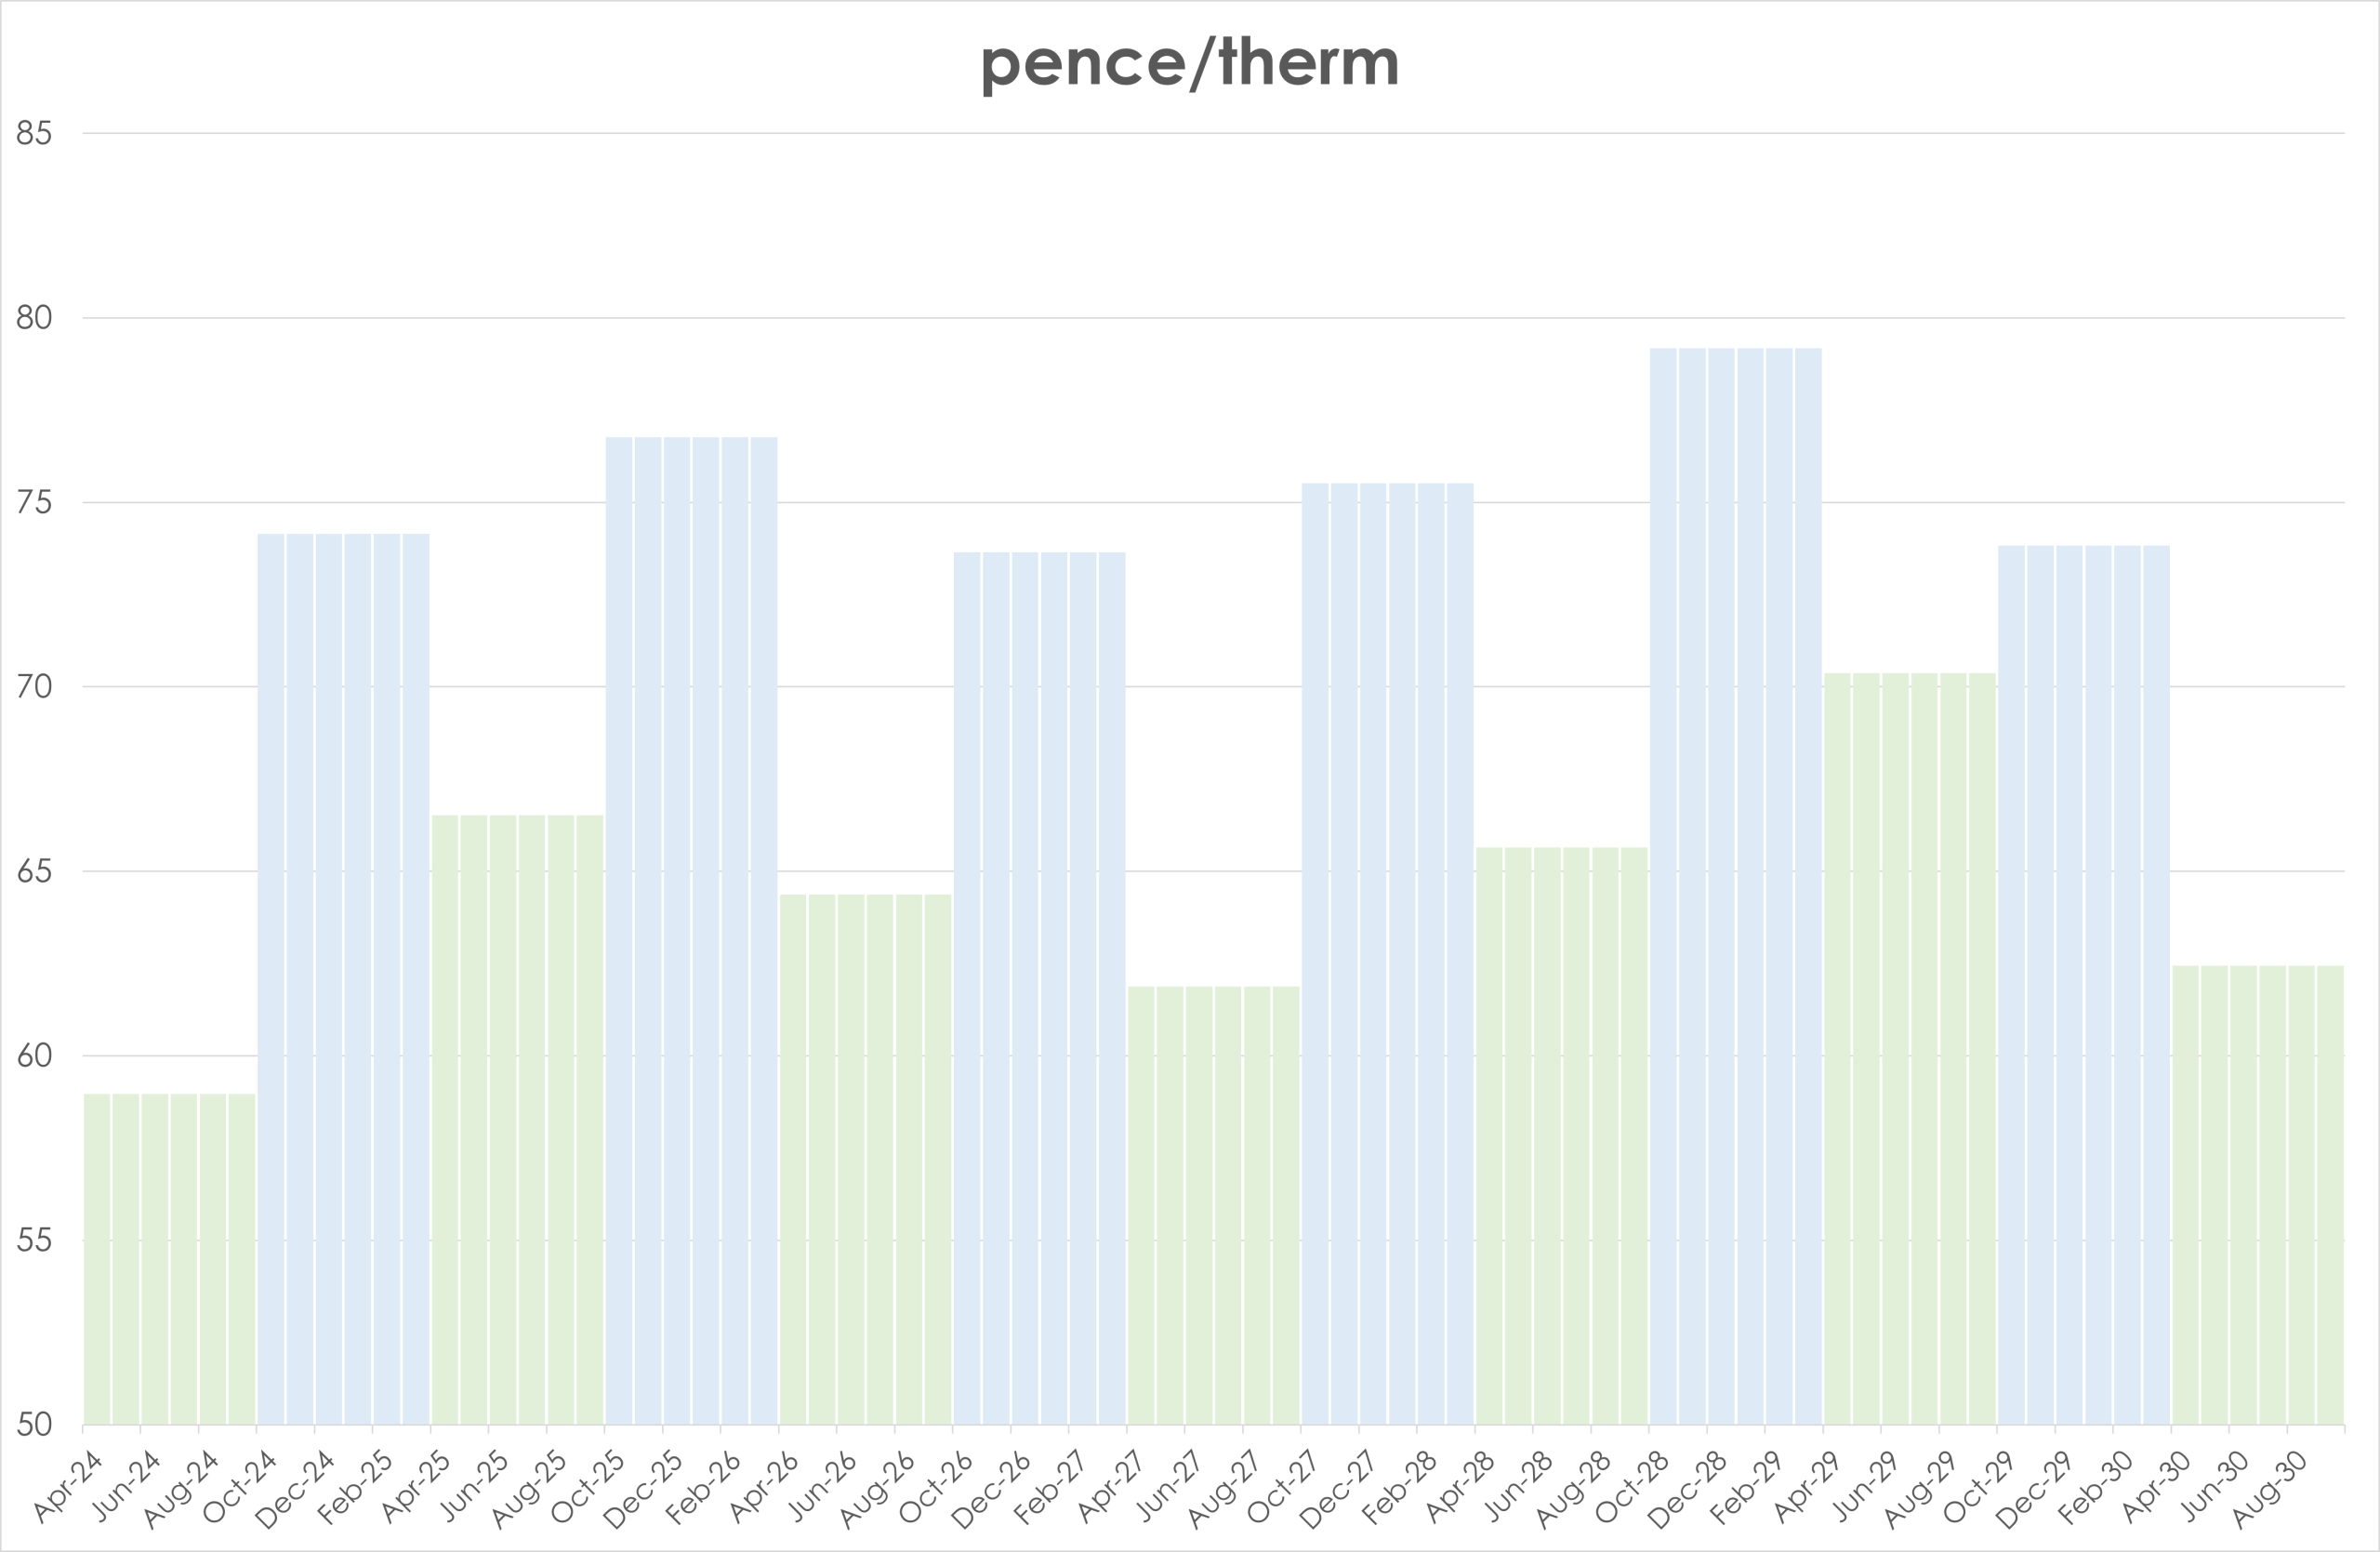
- The UK gas curve is starting to resemble a Mongolian camel! (see chart)
- Summer-24 delivery prices are at a 30% discount to Winter-24 delivery.
- Clients are increasingly hedging the low seasons with a view to seeing how Summer-24 conditioning impacts on the high seasons.
- Whilst markets have been backwardated for the last few years, the front seasons are now contango, then a mixed bag thereafter!
- Market context remains overwhelmingly bearish.
- Europe is still expected to end the winter with significant surplus still left in the tank (currently at 64% versus the 5-year average of 54%).
- Across Europe, temperatures look set to warm-up and demand is likely to drop-off throughout the week.
- In the UK, prices opened lower this morning despite a short system (demand outstripping supply).
- At the time of writing, however, prices are marginally up off the back of lower temperatures, the associated higher heating demand and technical momentum indicators very much in oversold territory (meaning a retracement/correction may be in the offing whilst market participants take a breath).
- In addition, increased storage withdrawals and forecasts of lower temperatures for early March are also lending support/limiting any further downside – at least in the short-term.
- On the supply side, Qatar has announced plans to increase LNG production by 16 million tonnes per year (meaning a total annual capacity of 142 million tonnes).
- The announcement came hot off the back of Biden’s decision to pause approvals for new US LNG export terminals citing environmental conerns (with the election looming).
- With Summer-24 now 33 days away, surely only geo-political unrest poses any risk to a continuation of the prevailing long-term bear trend.
- Monthly Day-Ahead averages are on target this month (so far) to achieve 64p/therm (or circa. 2.2p/kwh).
ELECTRICITY & CARBON ALLOWANCES
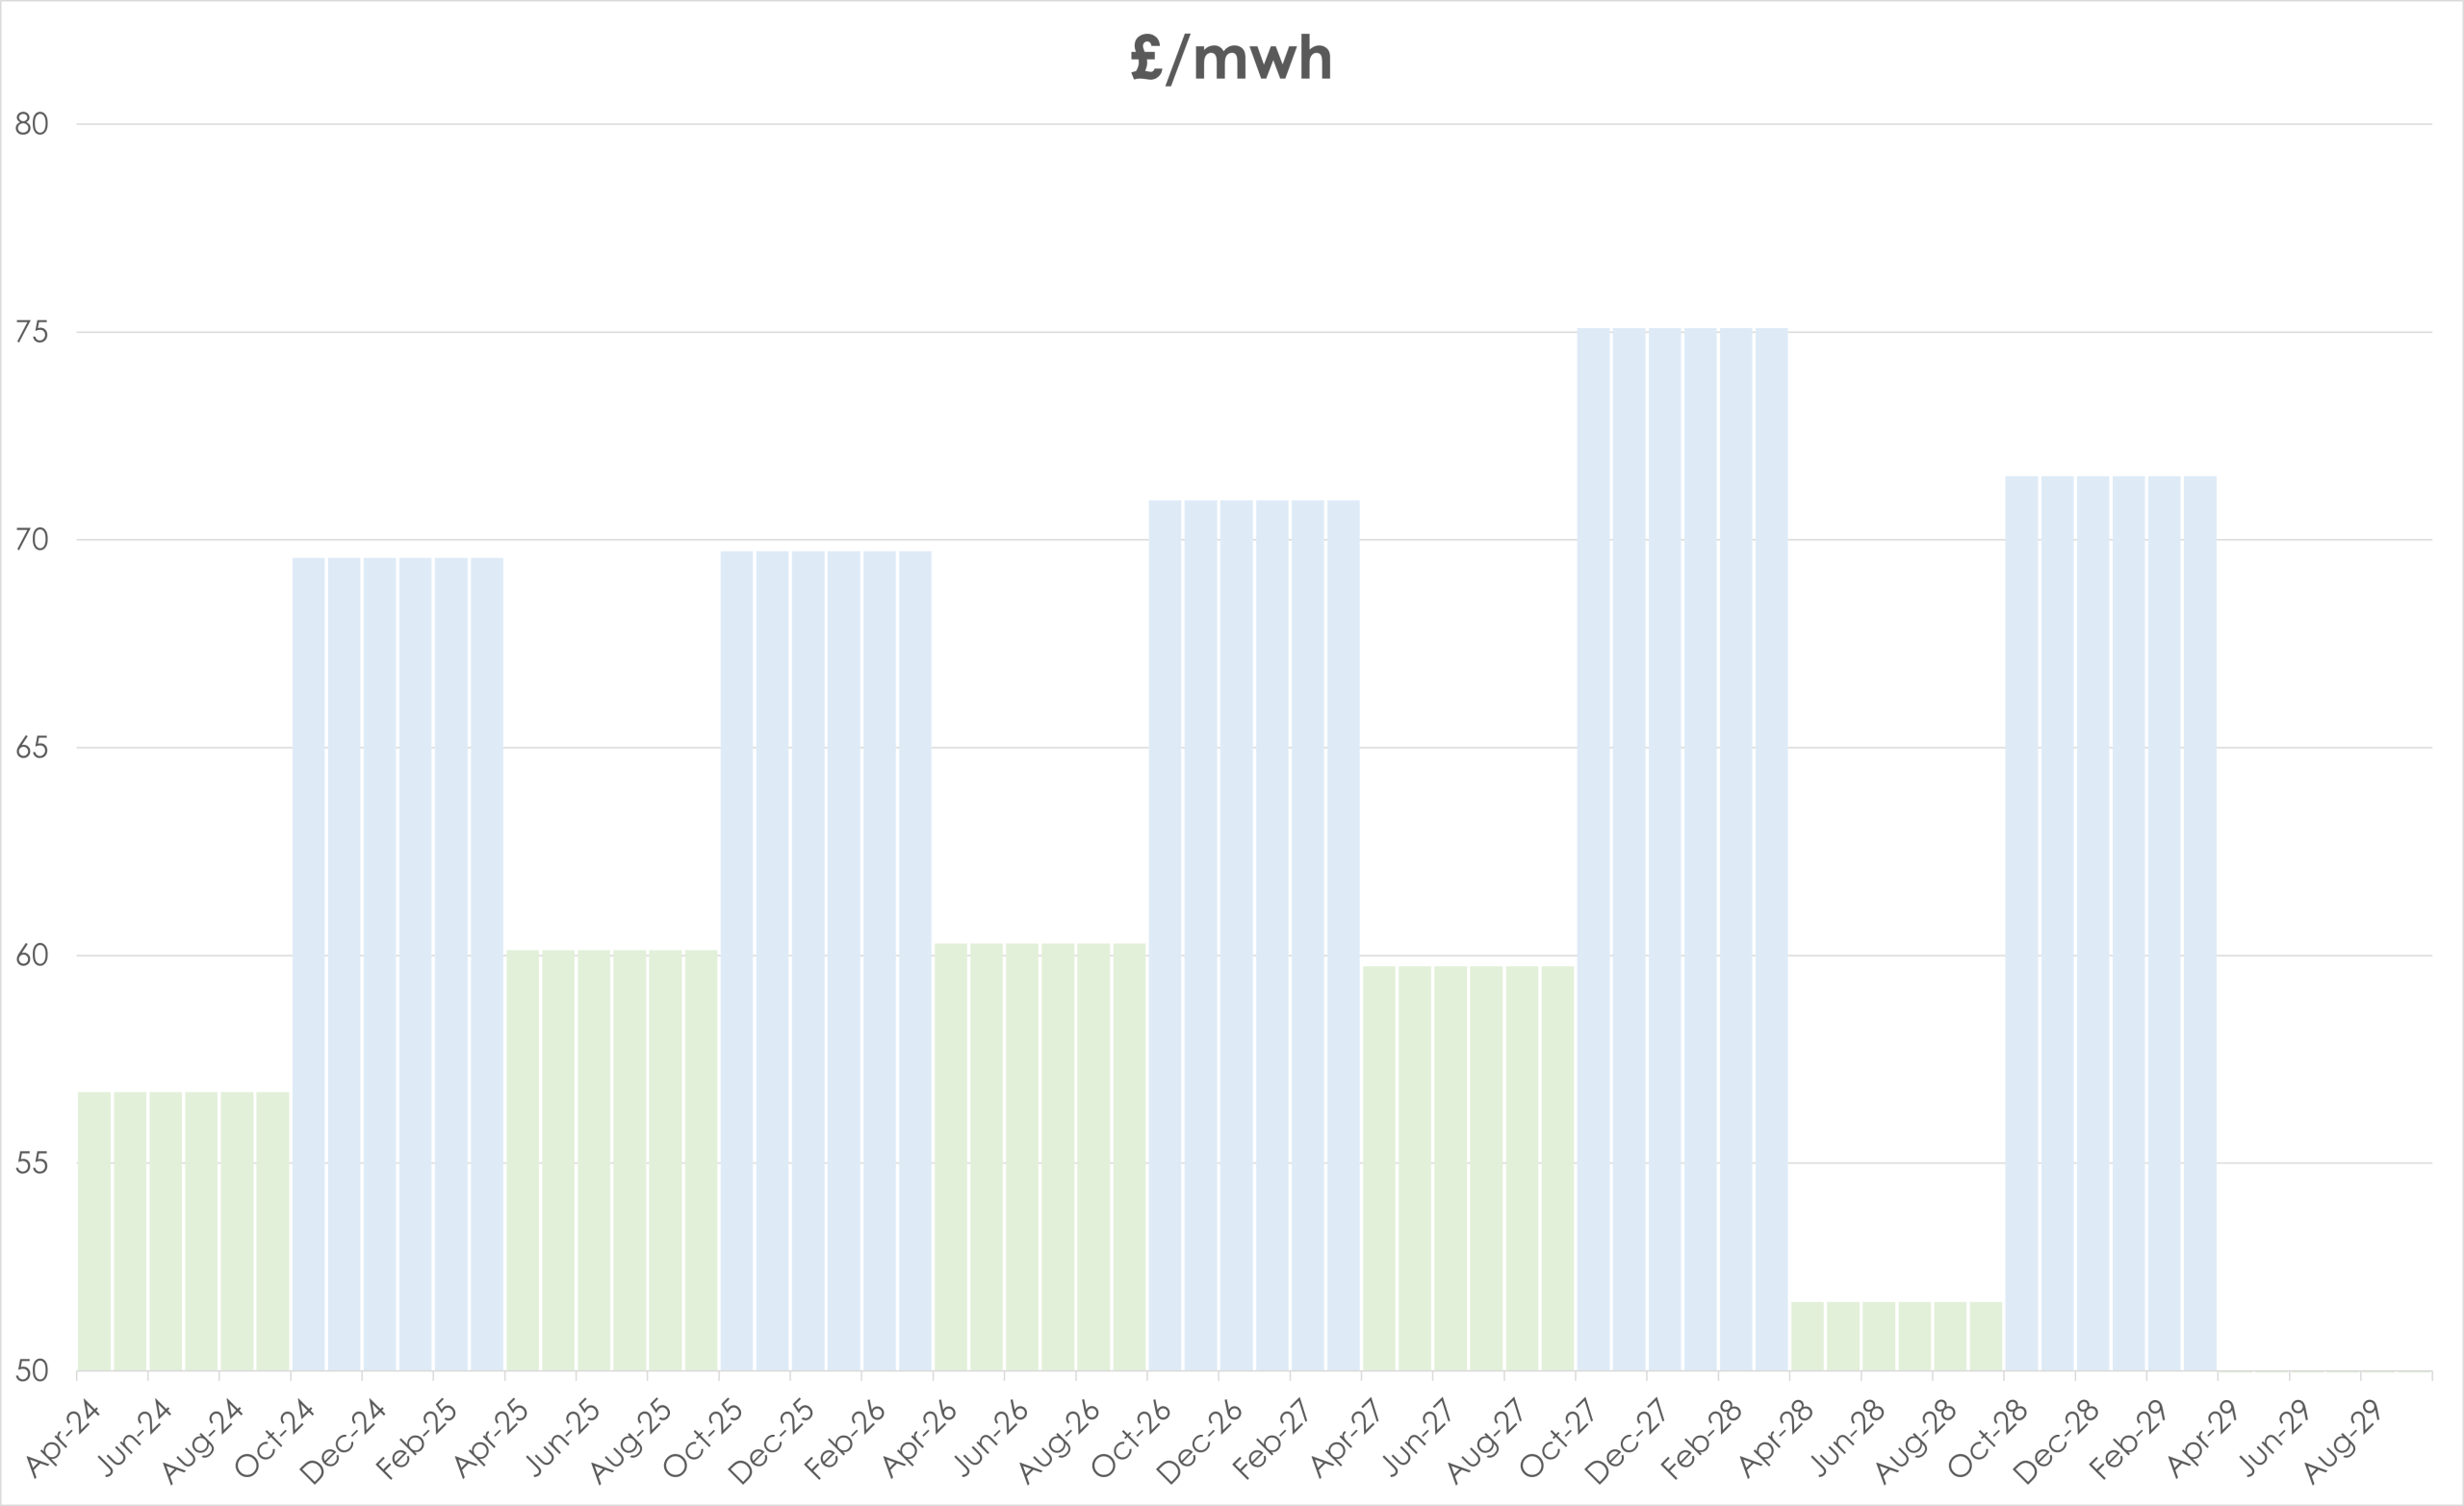
- Compared to UK gas, UK electricity Seasonal Forwards are more orderly, with winters at least now very much in a contango state (future delivery prices higher than near term delivery prices) – see chart.
- Summer-24 is at a 20% discount to Winter-24 prices.
- Assessment prices for Summer-29 have dropped off the chart, printing at £49/mwh! (4.9p/kwh).
- Looking to the continent, near-term delivery prices rose yesterday, buoyed by a drop in wind, lower temperatures and weak French nuclear availability against a backdrop of firmer fuels and emissions prices.
- Down the curve, markets retraced from oversold conditions, with selling interest drying-up temporarily.
- Forecasts of slightly lower wind output and temperatures for early-March supported the technical correction, but the fundamental picture remains overwhelmingly soft with a bleak demand outlook amid comfortable supply/demand dynamics.
- On carbon markets, EUAs started the week with a noticeable 3.3% jump, likely triggered by some short-covering after 52 €/t proved strong support.
- As allowances grow cheaper and more attractive for compliance (Industrial) players, it’s likely we’ll see some good buying interest at these low levels.
- Most analysts have significantly revised downward their projections for carbon prices for 2024 over the past weeks, expecting a recovery at some point but seeing little reason for a renewed uptrend just yet due to the higher supply and lower demand anticipated in 2024.
- UKAs finished the day at £35/tn for Dec-24 delivery.
- Back in the UK, our generation mix bearish in nature with renewables contributing 44% and gas-for-power burn at 34%.
- Monthly Day-Ahead averages for UK electricity are on target this month (so far) to achieve £59/mwh (or 5.9p/kwh).