



Tues, 26th May ’26
GAS
- As has become standard process, the US made its moves at the weekend whilst markets were closed.
- Whilst soundbites coming out of the White House indicated we were “hours away” from a resolution, the US then launched “defensive” strikes on missile plaements across southern Iran.
- The latest from Marco Rubio (US Secretary of State) is that finalising a deal could “take a few days”.
- Interestingly, a more defined narrative is permeating the airwaves that it was in fact Israel that convinced the US as to the merits of starting the war – this amid Israeli right-wing ministers continuing to press Netanyahu to resume Beirut strikes to counter Hezbollah drone attacks.
- Which begs the question, is the tail wagging the dog after all?
- Certainly, any lasting accord that will mean the re-opening of the Strait will require that Israel steps off its permanent war-footing.
- But can Netanyahu survive politically if Israel is forced to lay down its arms?
- So, whilst volatility remains elevated, actual trading liquidity is slowly but surely on the up.
- Without question, if the Strait re-opens, prices will drop to pre-war levels very quickly as replenishing storage should be fairly straightforward if supply routes can function unrestricted – European storge fullness is now at 38% versus the 5-year average of 48%, so totally salvageable if we can get the Strait opened in the coming couple of weeks.
- On the weather side of things, Europe’s first major heatwave of the season is expected to last all week, with temperatures significantly above seasonal norms (including the UK) 🙂
- This should release a little pressure from our system, with strong solar and supressed gas-for-power generation, offsetting the ongoing geopolitical uncertainties.
- On the FLEX side, most clients are now heavily hedged for Jun-26 delivery so as to mitigate against the Trump Administration’s unpredictability.
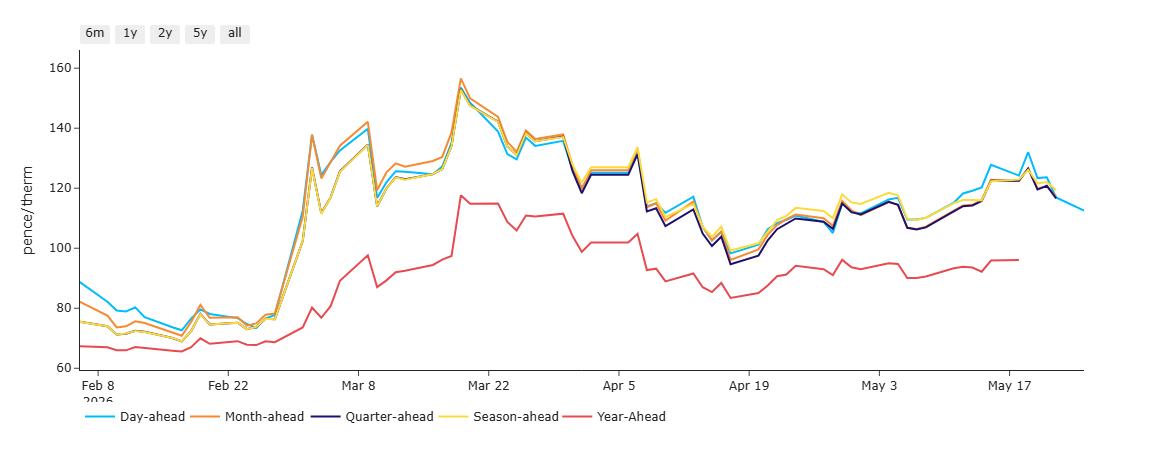
- Monthly Day-Ahead Averages for the month are holding steady at 117p/therm (or 4 p/kwh exc. non-gas).
- The ‘Prompt’ chart below shows the daily evolution of Day-Ahead/Month-Ahead/Quarter-Ahead/Season-Ahead/Year-Ahead.
- As you can see, prices have failed to retest the highs of 19th Mar-26, and are reacting encouragingly to the latest rumours of a deal that will mean the re-opening of the Strait.
- We have all our fingers crossed for buyers, as the return of steady supply through the Strait will see a resumption of soft pricing all the way down the curve.
ELECTRICITY & CARBON
- Whilst UK electricity prices have been significantly less volatile than gas prices since the US/Israeli offensive began back on 28th Feb, nonetheless, the last week has seen front end prices back above the psychological leel of £100/mwh.
- Today’s UK electricity generation mix is neutral in nature, neither bullish nor bearish – specifically, renewables are contributing 33%, thermal at 26% (gas and coal) and low carbon at 23% (nuclear and imports).
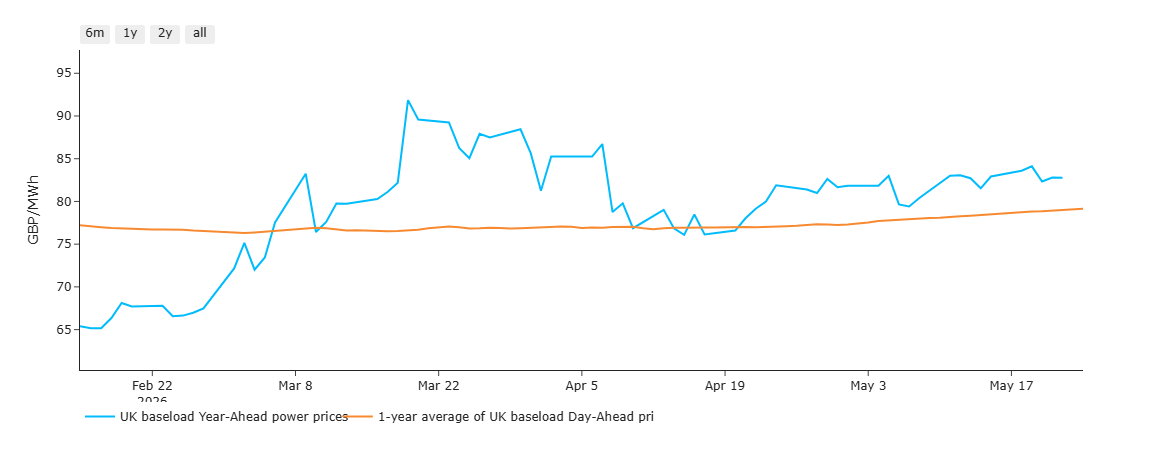
- The chart below details UK electricity Year-Ahead prices versus the 1-Year Average of Day-Ahead prices since the US/Israeli offensive began back on 28th Feb.
- By way of explanation, when the blue line is above the orange line, mid-term delivery prices are at a premium to an average of the last 12 months.
- We’ll be watching this dataset very closely in the event a deal is reached, as one would expect for the blue line to plunge beneth the orange line in short order thereafter – watch this space.
- On the Carbon side of things, Dec-26 UKA delivery began the conflict heavily correlated to gas markets.
- However, correlation shifted to equities throughout March (which continue to enjoy a strong, tech-led upwards momentum).
- At the time of writing, UKA mid-price Dec ’26 delivery has sky-rocketed to £56.02/tn (and the spot is at mid-55s) – we believe this is a reaction to some very heavy institutional investing of EUAs on Friday.
- We think the move strange amid high temperatures and suppressed thermal generation – and so we’d expect the move to be short-lived.
- Monthly Day-Ahead Averages for UK electricity for May so far are holding steady at £101/mwh (or 10.1 p/kwh exc. non-energy).