



Tues, 26th Aug ’25
GAS
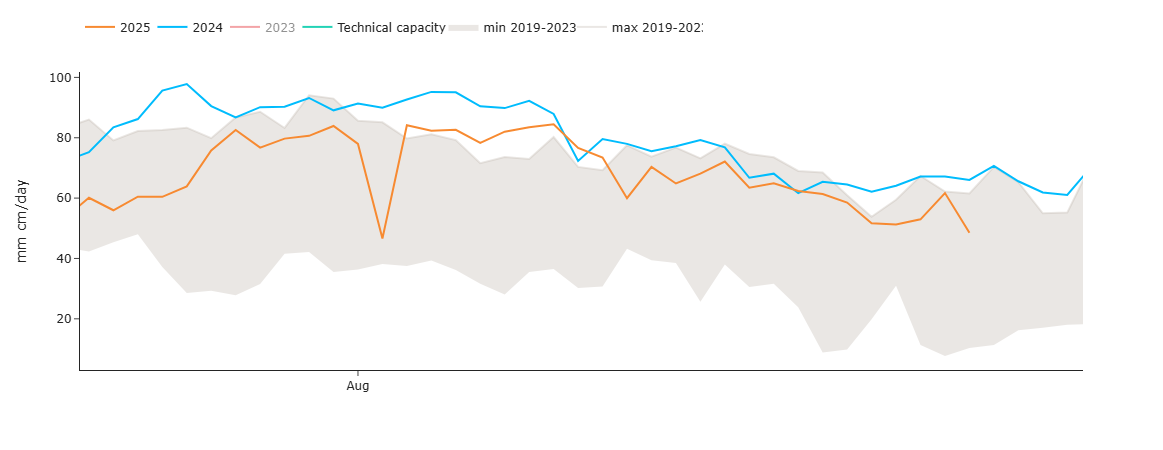
- A ceasefire agreement between Putin/Zelensky looks increasingly unlikely – as such, focus is starting to shift toward the coming heating season and European storage.
- European inventories are now at 76% versus the 5-year average of 81% – so we’re on track to reach dry land before injections stop and withdrawals begin (usually November).
- Norwegian outages are ramping up, with import in to the UK beginning to fall accordingly (please see chart below detailing declining Norwegian imports into the UK) – several facilities are now under maintenance, including the giant Troll field (though supply interruptions aren’t as bad as initially anticipated – yet).
- Any late buyers of Winter-25 delivery are still advised to get in BEFORE the 2nd week of September at the very latest.
- Warmer weather is forecast to spread across Europe over the coming fortnight – which should help to keep a lid on gas-for-power burn.
- Monthly Day-Ahead averages for the month so far are at 79p/therm (or 2.7p/kwh exc. non-gas) – all but unchanged throughout the month, reflecting very low-short term risk.
ELECTRICITY & CARBON
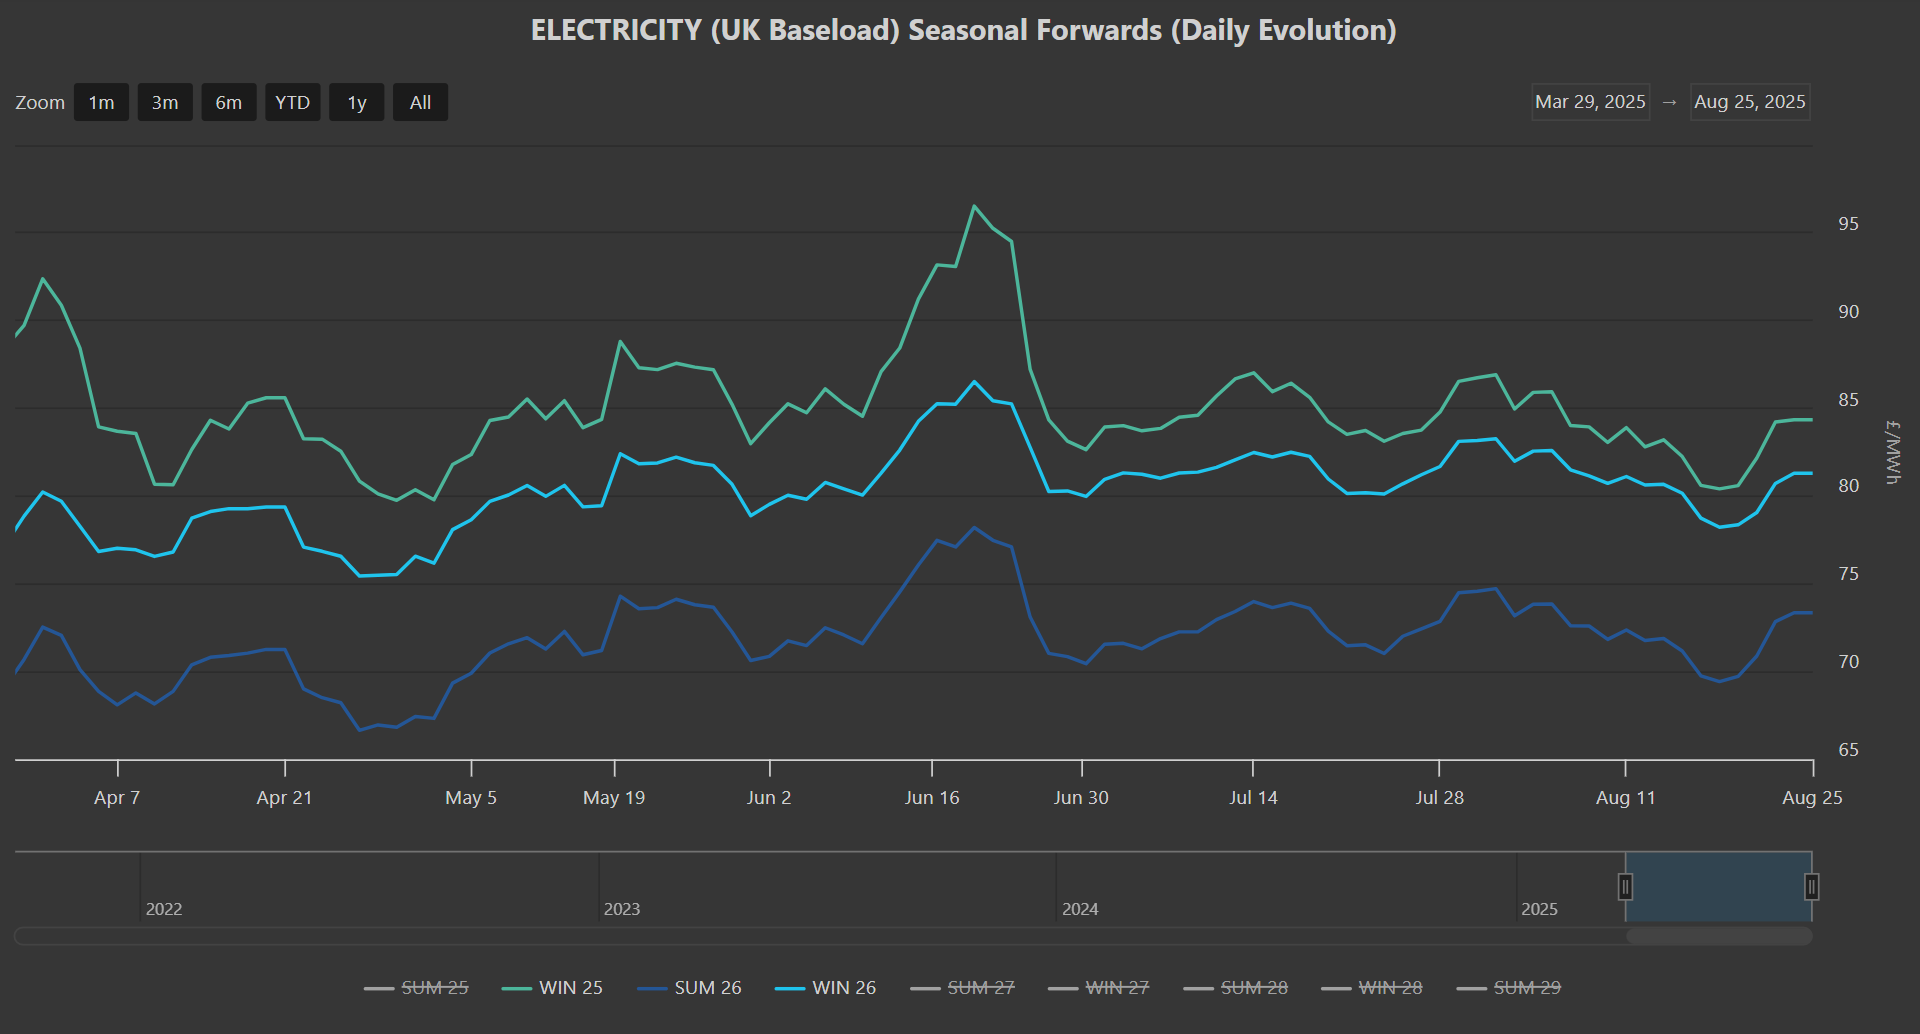
- The front 3-Seasons (Winter-25/Summer-26/Winter-26) remain toward the bottom of the rangebound price action we’ve seen this summer (please see chart below).
- On the Carbon side of things, UKAs are increasingly correlated to EUAs (following the “common understanding” reached between the UK/Europe to link emissions markets at the UK-EU summit in London on 19th May).
- Dec ’25 UKA benchmark prices are at £51.65/tn on the mid-price, having fallen below support to start the week but now retesting resistance – in short, it’s rangebound price action with prices having traded within a 15% bracket since the onset of Summer-25 (1st Apr).
- Today’s UK electricity generation mix is bearish in nature – specifically, renewables are contributing 54%, thermal at 10% (gas and coal) and low carbon at 20% (nuclear and imports).
- Any late buyers of Winter-25 delivery are still advised to get in BEFORE the 2nd week of September at the very latest.
- Monthly Day-Ahead averages for the month so far are at £73/mwh (or 7.3p/kwh exc. non-energy).