



Tues, 10th Dec ’24
GAS
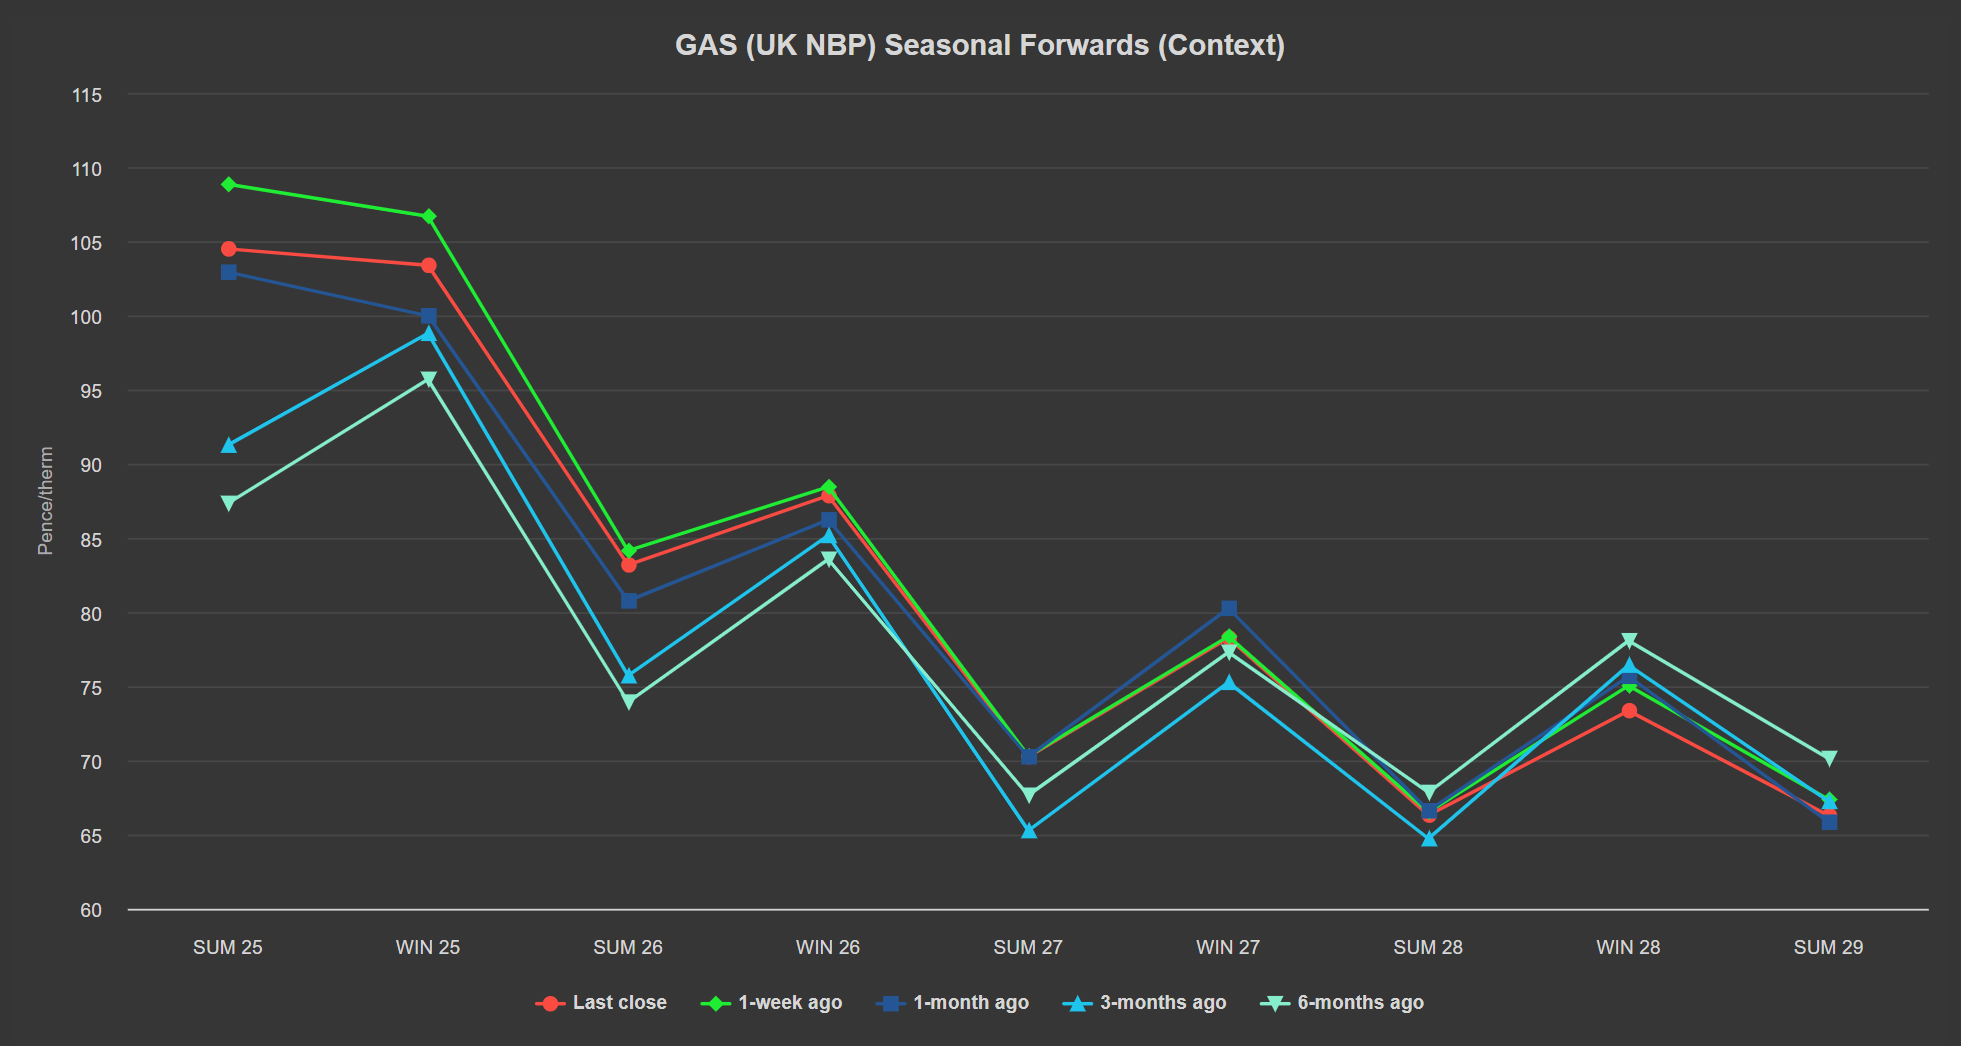
- Despite last week’s (arguably overcooked) fears that replenishing European gas storage during Summer-25 (in time for Winter-25) might prove problematic, Summer-25 prices have nonetheless dropped off nicely so far this week.
- Whilst Summer-25 remains at a marginal premium to Winter-25 (as it has been for over a month now), the difference has narrowed to 1p/therm (equivalent to 0.03p/kwh) – see chart below.
- Notably, in a rare/significant concession last week, President Putin issued a decree dropping the requirement to use Gazprombank for European gas payments.
- This triggered a downward correction in gas prices, particularly Summer-25 – as seemingly conciliatory behaviour on the part of Russia can only be a good thing where supply is concerned.
- To start the week, bearish momentum continued off the back of milder weather forecasts (which seem to be flip-flopping on a daily basis).
- Geopolitical developments in Syria had little or no impact – instead market participants reacted to weaker demand expectations for heating in the second half of December.
- Selling interests for some spot LNG cargoes from Chinese importers probably played into bearish sentiment as well – reflecting lowering Chinese demand/preference for coal.
- In addition, US LNG netbacks (a measure of the export parity price that a gas supplier can expect to receive for exporting its gas) continue to favour Europe as a premium destination compared to Asia (although the spread is marginal).
- Down the curve (longer-term delivery), prices have slipped too – the weak booking at auction for Summer-25 European storage capacity is also likely weighing on market sentiment (as further evidence of low demand forecasts).
- In short, as we pointed out last week, it’s not panic stations yet – prevailing conditions, whilst wintry, are not too bad.
- European storage fullness is at 82% versus the 5-year average of 81% (so withdrawals have slowed).
- So far this month, Monthly Day-Ahead averages are on target to achieve 115.873p/therm (or approx. 3.954p/kwh excluding non-gas).
ELECTRICITY & CARBON
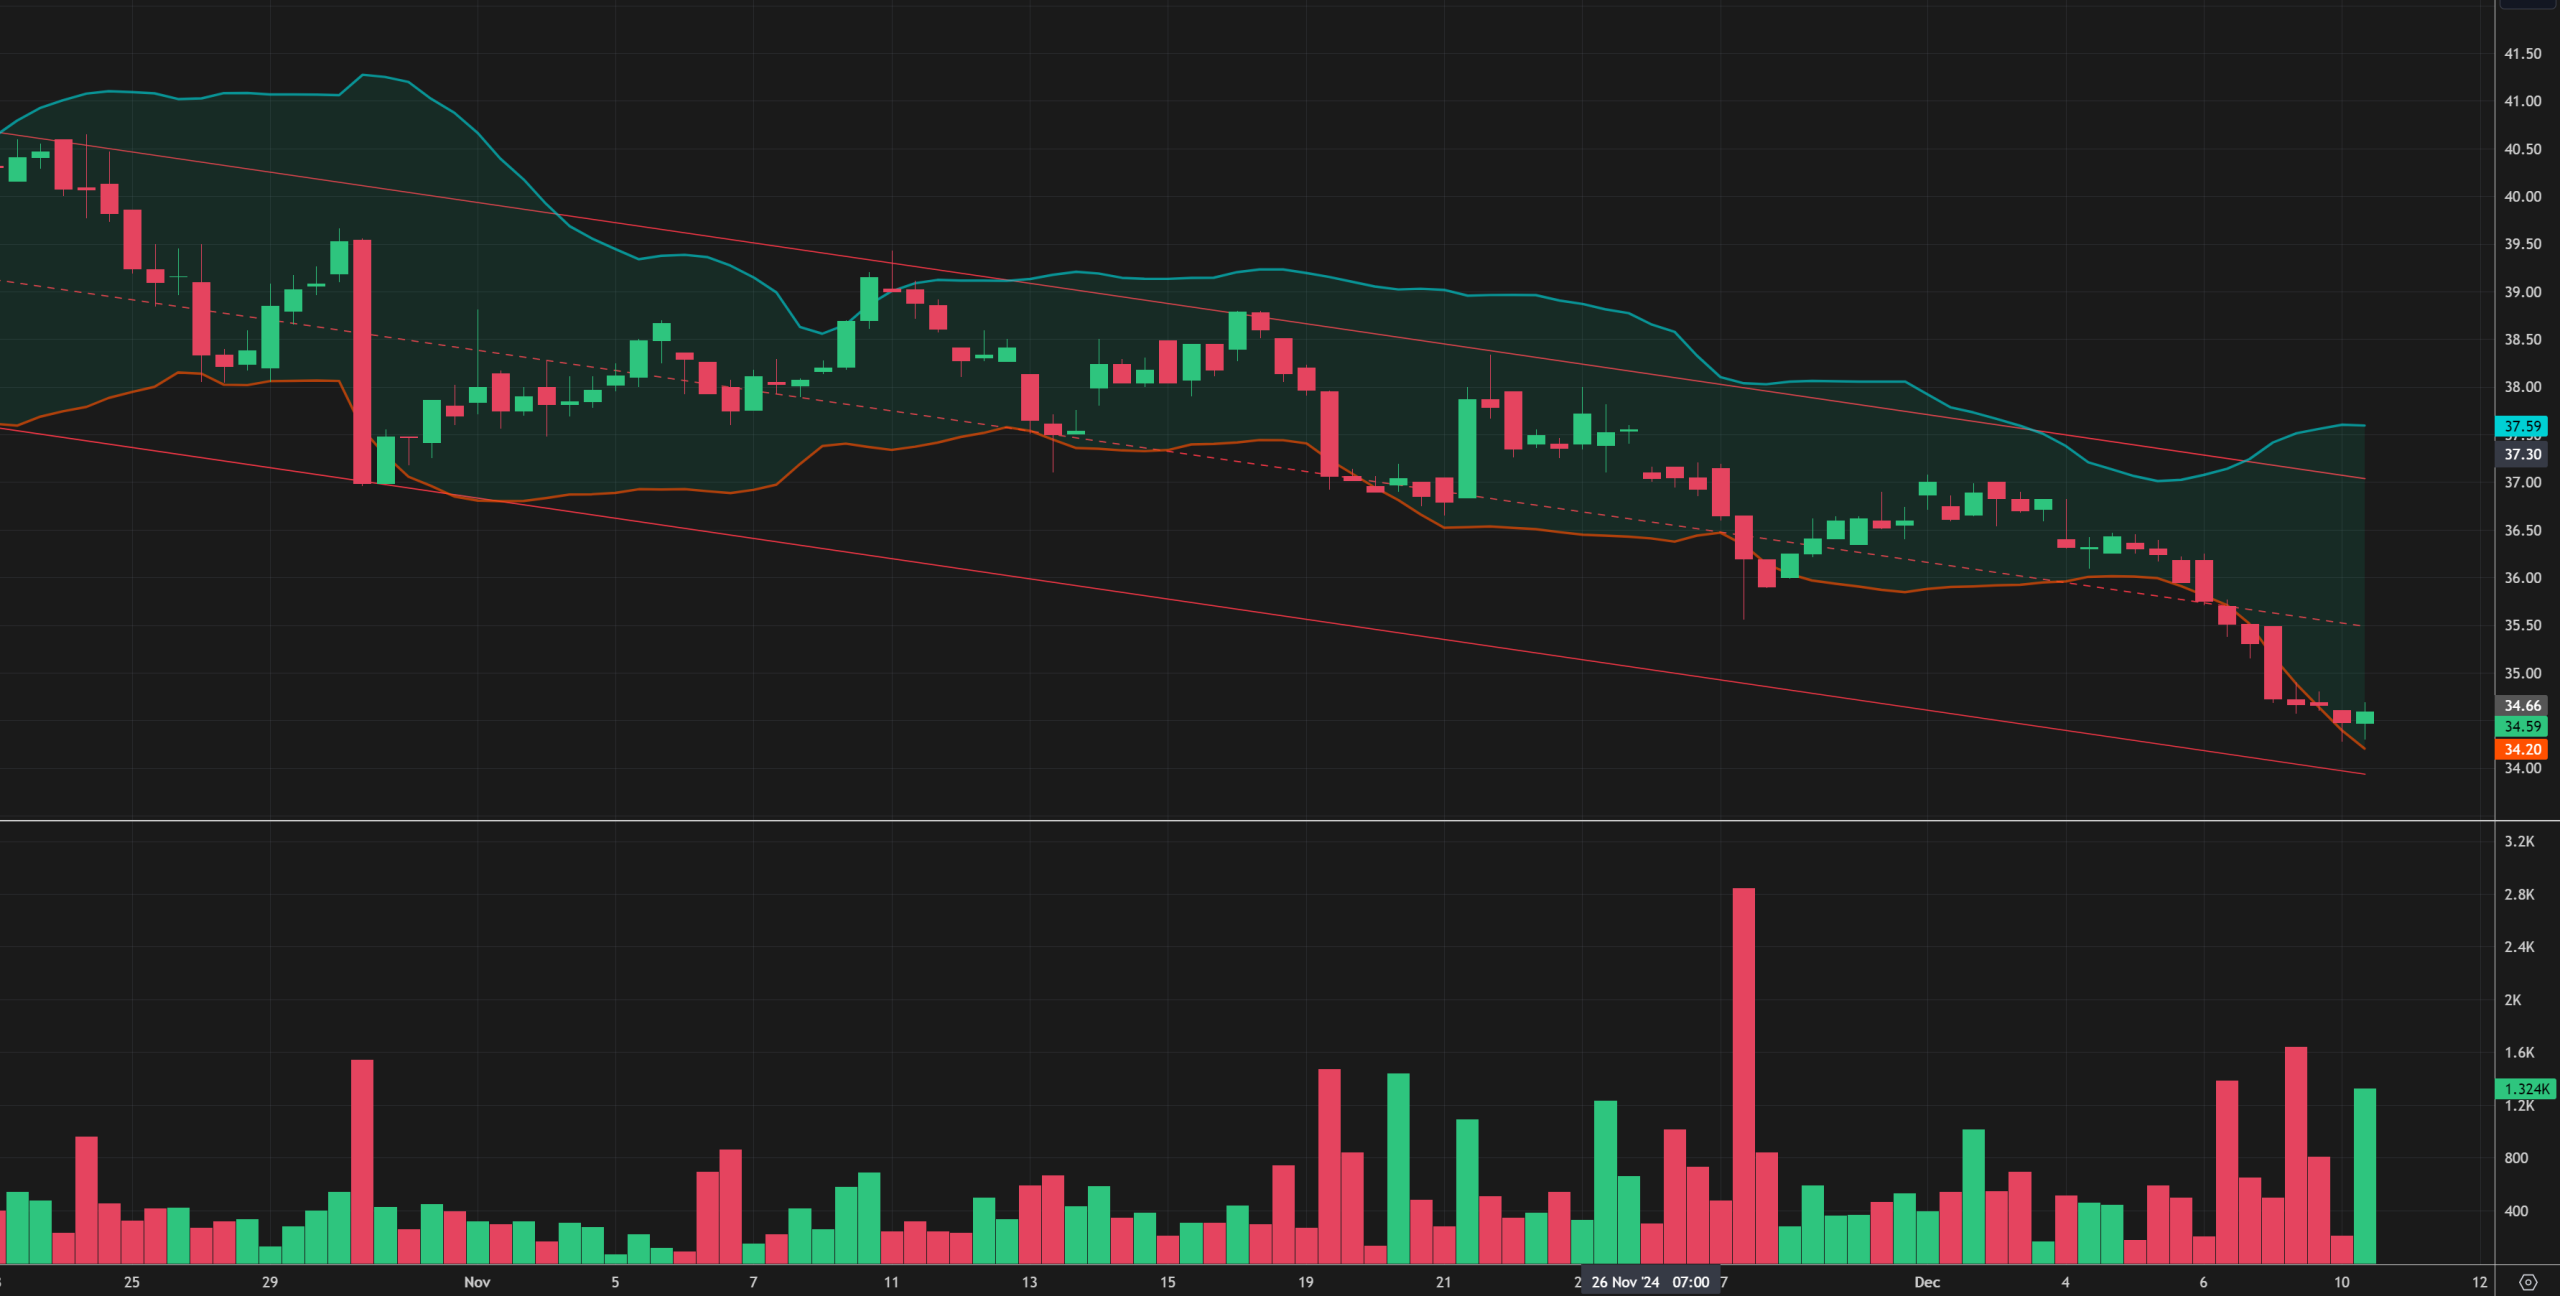
- Summer-25 electricity has enjoyed some decent drop off this week – at £81.20/mwh (or 8.12p/kwh), down on the week and the month.
- On the Carbon markets, UKAs (UK Allowances) are back on the slide on low volumes (see chart below) – having broken below the lows of 7th Oct-24, with a retest of the all-time lows of £31.30/tn printed on 29th Jan-24 now in the offing.
- At the time of writing, UKA mid-price is at £34.59 – so very welcome comparative value back on the table for Compliance buyers.
- The UK’s electricity generation mix is bullish in nature today with renewables contributing 23%, thermal at 51% (gas and coal) and low carbon at 18% (nuclear and imports).
- Monthly Day-Ahead averages for the month so far are on target to achieve £101.037/mwh (or 10.10p/kwh excluding non-energy).