



Thurs, 8th Feb ’24
GAS
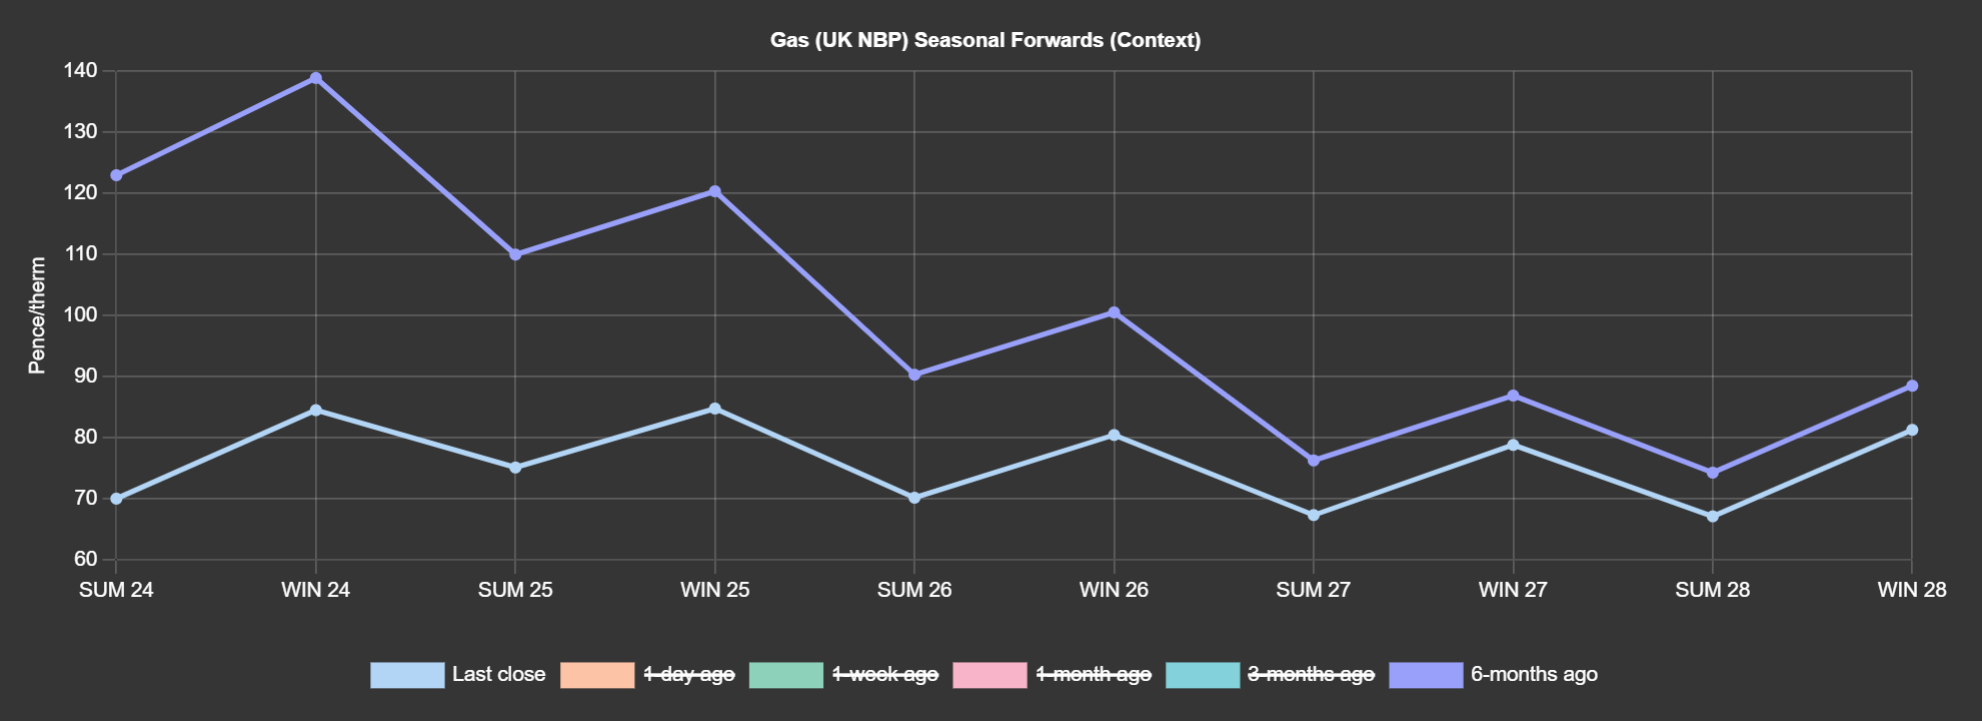
- With only 52 days remaining of Winter-23, Summer-24 delivery is now at a 43% reduction versus 6-months ago (see chart).
- Markets look poised to finish down on the day.
- Key drivers remain unchanged (and overwhelmingly bearish), with European storage at 68% fullness versus the 5-year average of 52%; steady LNG arrivals degasifying at European/UK ports; Norwegian flows back above the 5-day average.
- Demand is down d-o-d against a backdrop of improved wind outputs limiting gas-for-power burn.
- Near-term temperature forecasts lead us to expect benign conditions over the weekend – thereafter, the long touted February cold spell should hit, and prices will likely be supported accordingly.
- Despite ongoing withdrawal from UK reserves, our system opened short this morning – regardless, market participants have shrugged off any bullish momentum in favour of the draw/weight of the overwhelmingly bearish big picture.
- Whilst geopolitical risk is stopping the markets from falling off a cliff as summer approaches, the impact of Ukraine and the Red Sea problems on the supply/demand dynamic seem to be limited.
- That having been said, consensus anticipates global LNG exports to fall by circa. 10% this month (due to outages at Freeport, Texas and shipping delays caused by vessels avoiding the Red Sea area).
- Monthly Day-Ahead averages are on target this month (so far) to achieve 70p/therm (or circa. 2.4p/kwh).
ELECTRICITY & CARBON ALLOWANCES
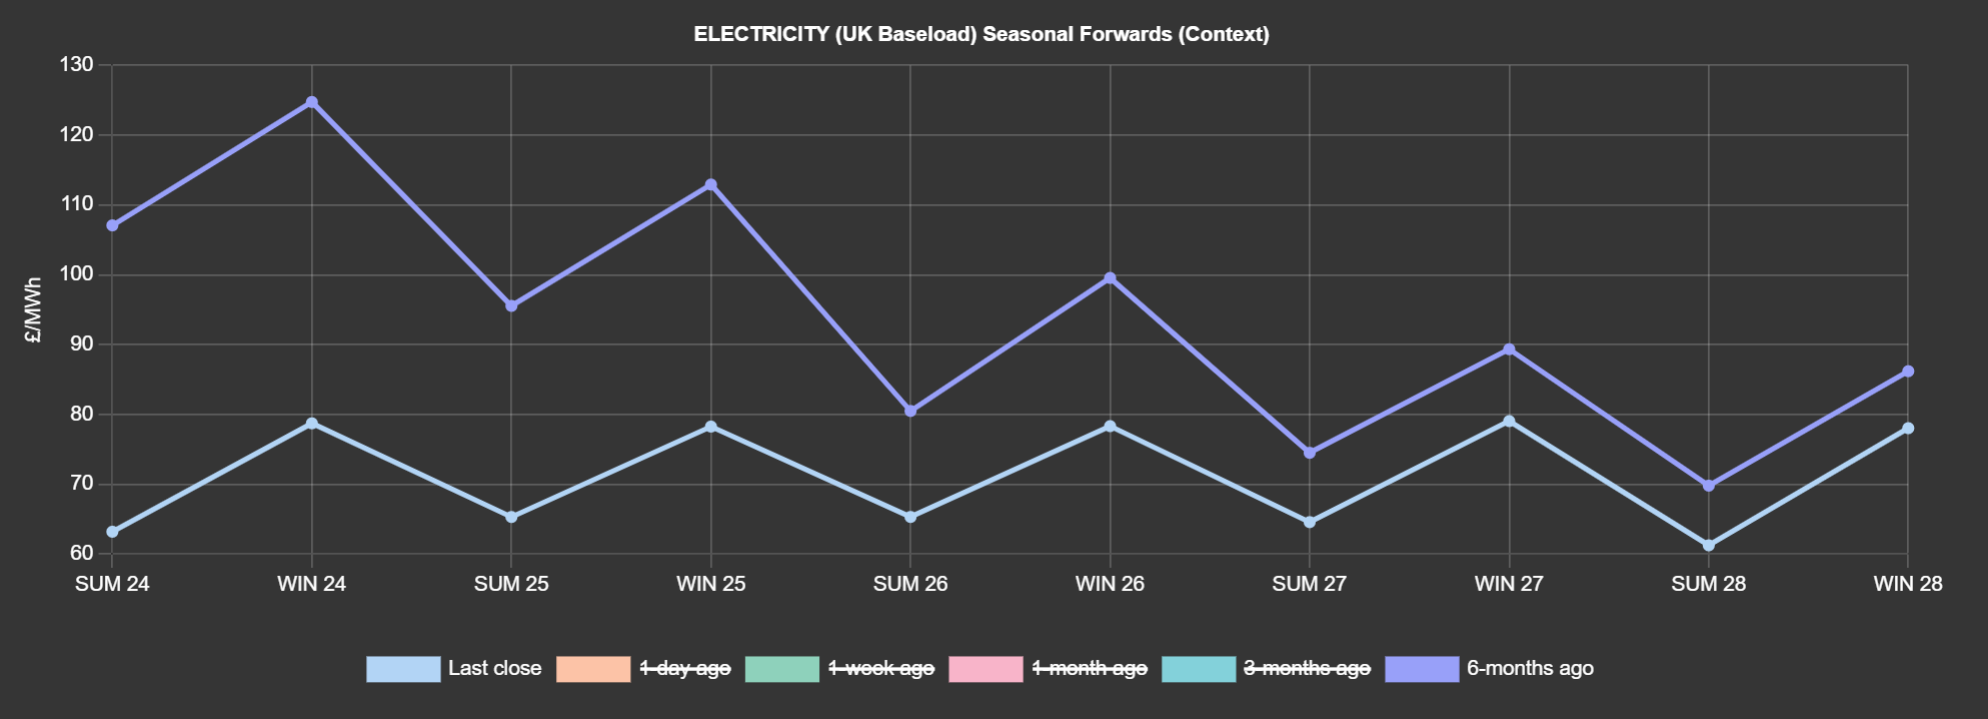
- With only 52 days remaining of Winter-23, Summer-24 delivery is now at a 41% reduction versus 6-months ago (see chart).
- Looking to the continent, near-term delivery prices were mixed/directionless/balanced yesterday.
- Further down the curve, prices were mostly down on the day – tracking the fading gas and carbon markets in an overall retracement of the previous day’s marginal rebound.
- The energy market has been trading within a tight range for the past fortnight, driven by daily shifts in weather forecasts.
- This morning was no exception, as temperatures for mid-February are once again revised upwards across NW Europe, resulting in a downturn in prices.
- The lack of volatility reflects the markets having entered a wait-and-see mode – or a state of equilibrium.
- On the carbon markets, the COT (Commitment of Traders Report) did little to move the markets yesterday showing negligible change in speculators’ positions from last week.
- Our generation mix today is neutral to bearish again – 40% renewables versus 35% gas-for-power burn.
- Monthly Day-Ahead averages for UK electricity are on target this month (so far) to achieve £56/mwh (or 5.6p/kwh).