



Thurs, 21st Nov ’24
GAS
- Markets have reacted bullishly to Russia firing an intercontinental ballistic missile (ICBM) at Ukraine – with tensions escalating after 33-months of relative stalemate.
- ICBMs are, of course, strategic weapons designed to deliver nuclear warheads – so this retaliatory response to Ukraine having fired US-made weapons at Russia this week is no doubt the Kremlin’s way of reminding European countries of Russia’s nuclear capabilities.
- Early reports suggest the missile was fired from the Russian region of Astrakhan, more than 700 km (435 miles) from Dnipro in Ukraine.
- Both near- and far-term delivery is up – with Month-Ahead at 121.46p/therm at the time of writing.
- All eyes are on the Sudzha transit point, and whether this latest incident will impact Russian flow currently transiting via Ukraine.
- Prices are also being supported by outages at the Karsto gas plant in Norway amid the recent wintry increase in demand.
- Subsequent to necessary withdrawals, European storage levels (now at 90%) are 1% lower than the 5-year average (91%).
- However, recent LNG flows away from Asia and into Europe are tempering fears over supply shortages.
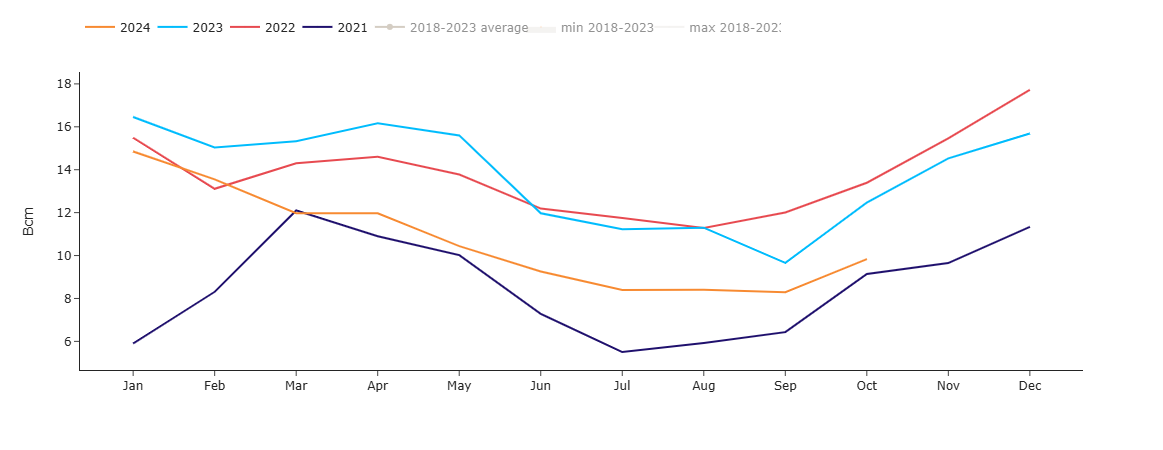
- Thankfully, LNG arrivals to European shores are forecast at a 25% increase w-o-w, and are expected to be at levels not seen since Feb-24 by month-end (see chart below).
- UK prices will likely remain at a premium versus Europe’s as the winter progresses – otherwise, we’ll be left high and dry where LNG arrivals are concerned.
- This premium is always exacerbated by structural problems in the UK’s gas system resulting in high transmission costs and, of course, a lack of storage compared to Europe – meaning the UK needs to offer a much higher price to secure supply.
- Monthly Day-Ahead averages so far this month are on target to achieve 108.633p/therm (or approx. 3.707p/kwh excluding non-gas).
ELECTRICITY & CARBON
- Looking to the continent, Carbon prices dropped off yesterday notwithstanding higher gas prices.
- The COT (Commitment of Traders report) published yesterday showed that speculators have further increased their long (buy) positions.
- Nonetheless, in the afternoon session, prices moved lower most likely off the back of profit taking pending the next bullish leg up.
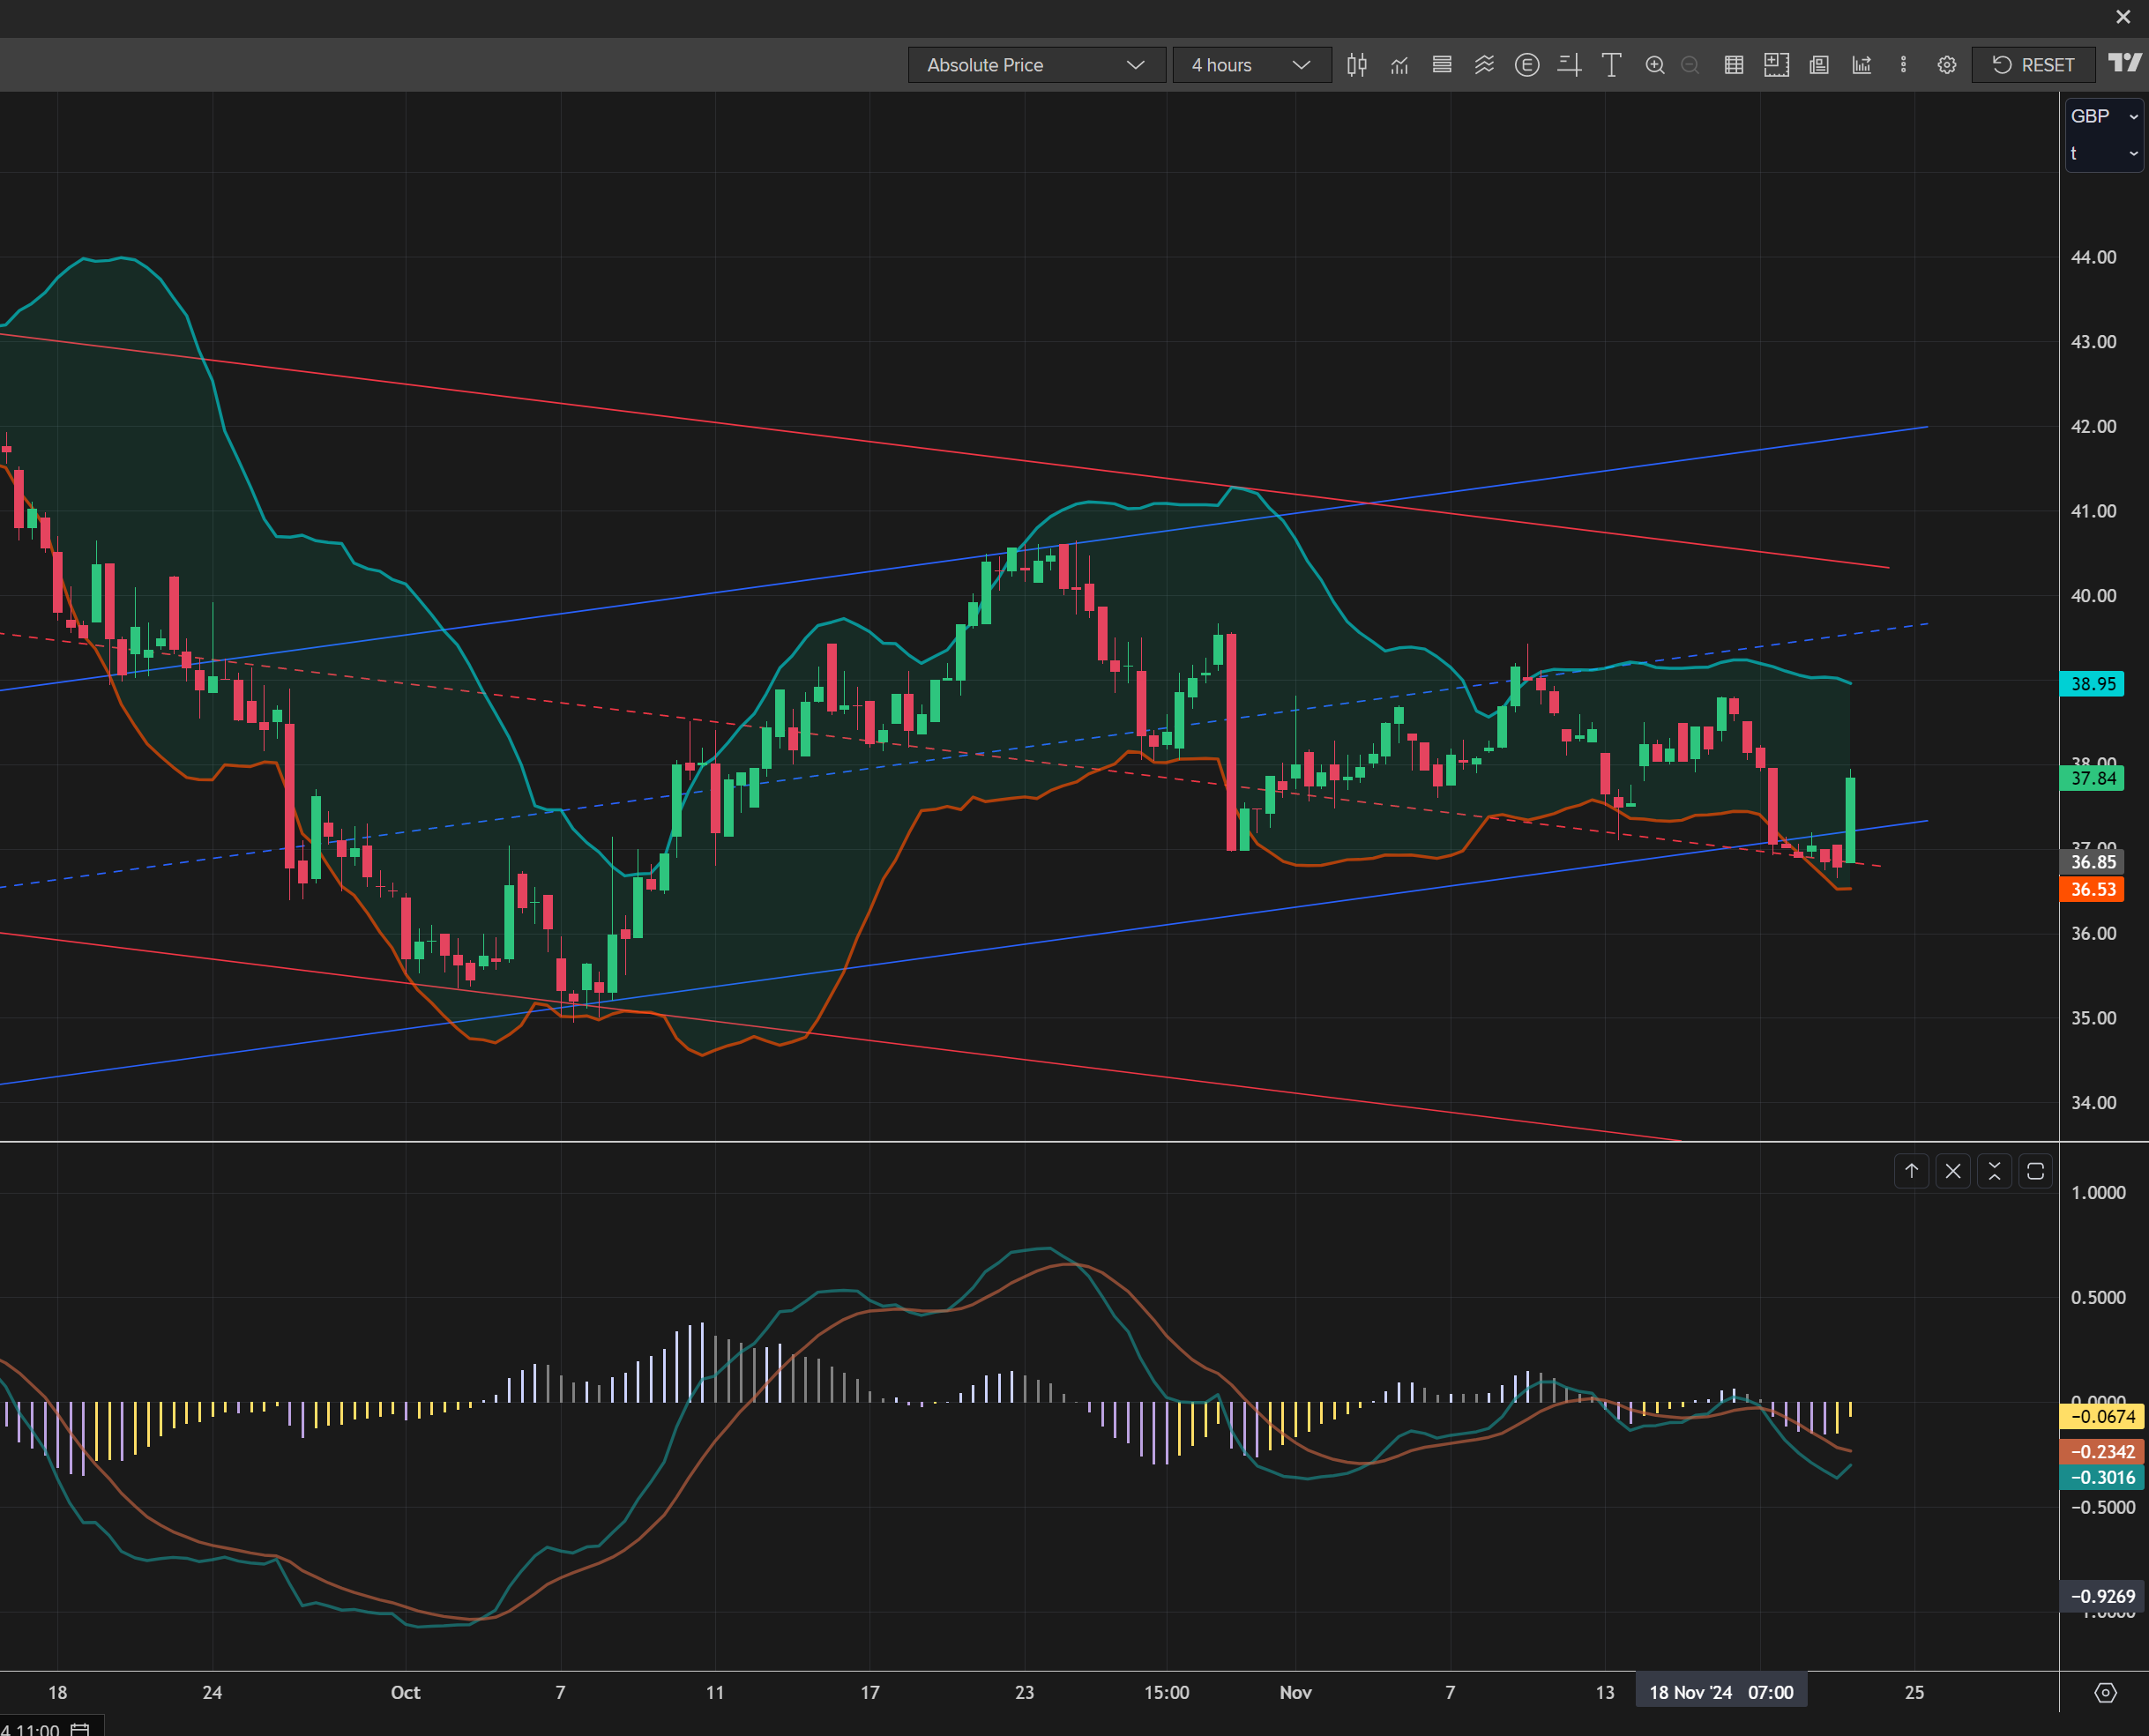
- UKAs have been enjoying further downside until this morning when, despite having broken below key trendlines, Russia’s ICBM attack instigated a significant bounce (see chart below).
- The UK’s electricity generation mix is bullish in nature today with renewables contributing 31%, thermal at 46% (gas and coal) and low carbon at 16% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £101.643/mwh (or 10.16p/kwh excluding non-energy).