



Thurs, 19th Jun ’25
GAS
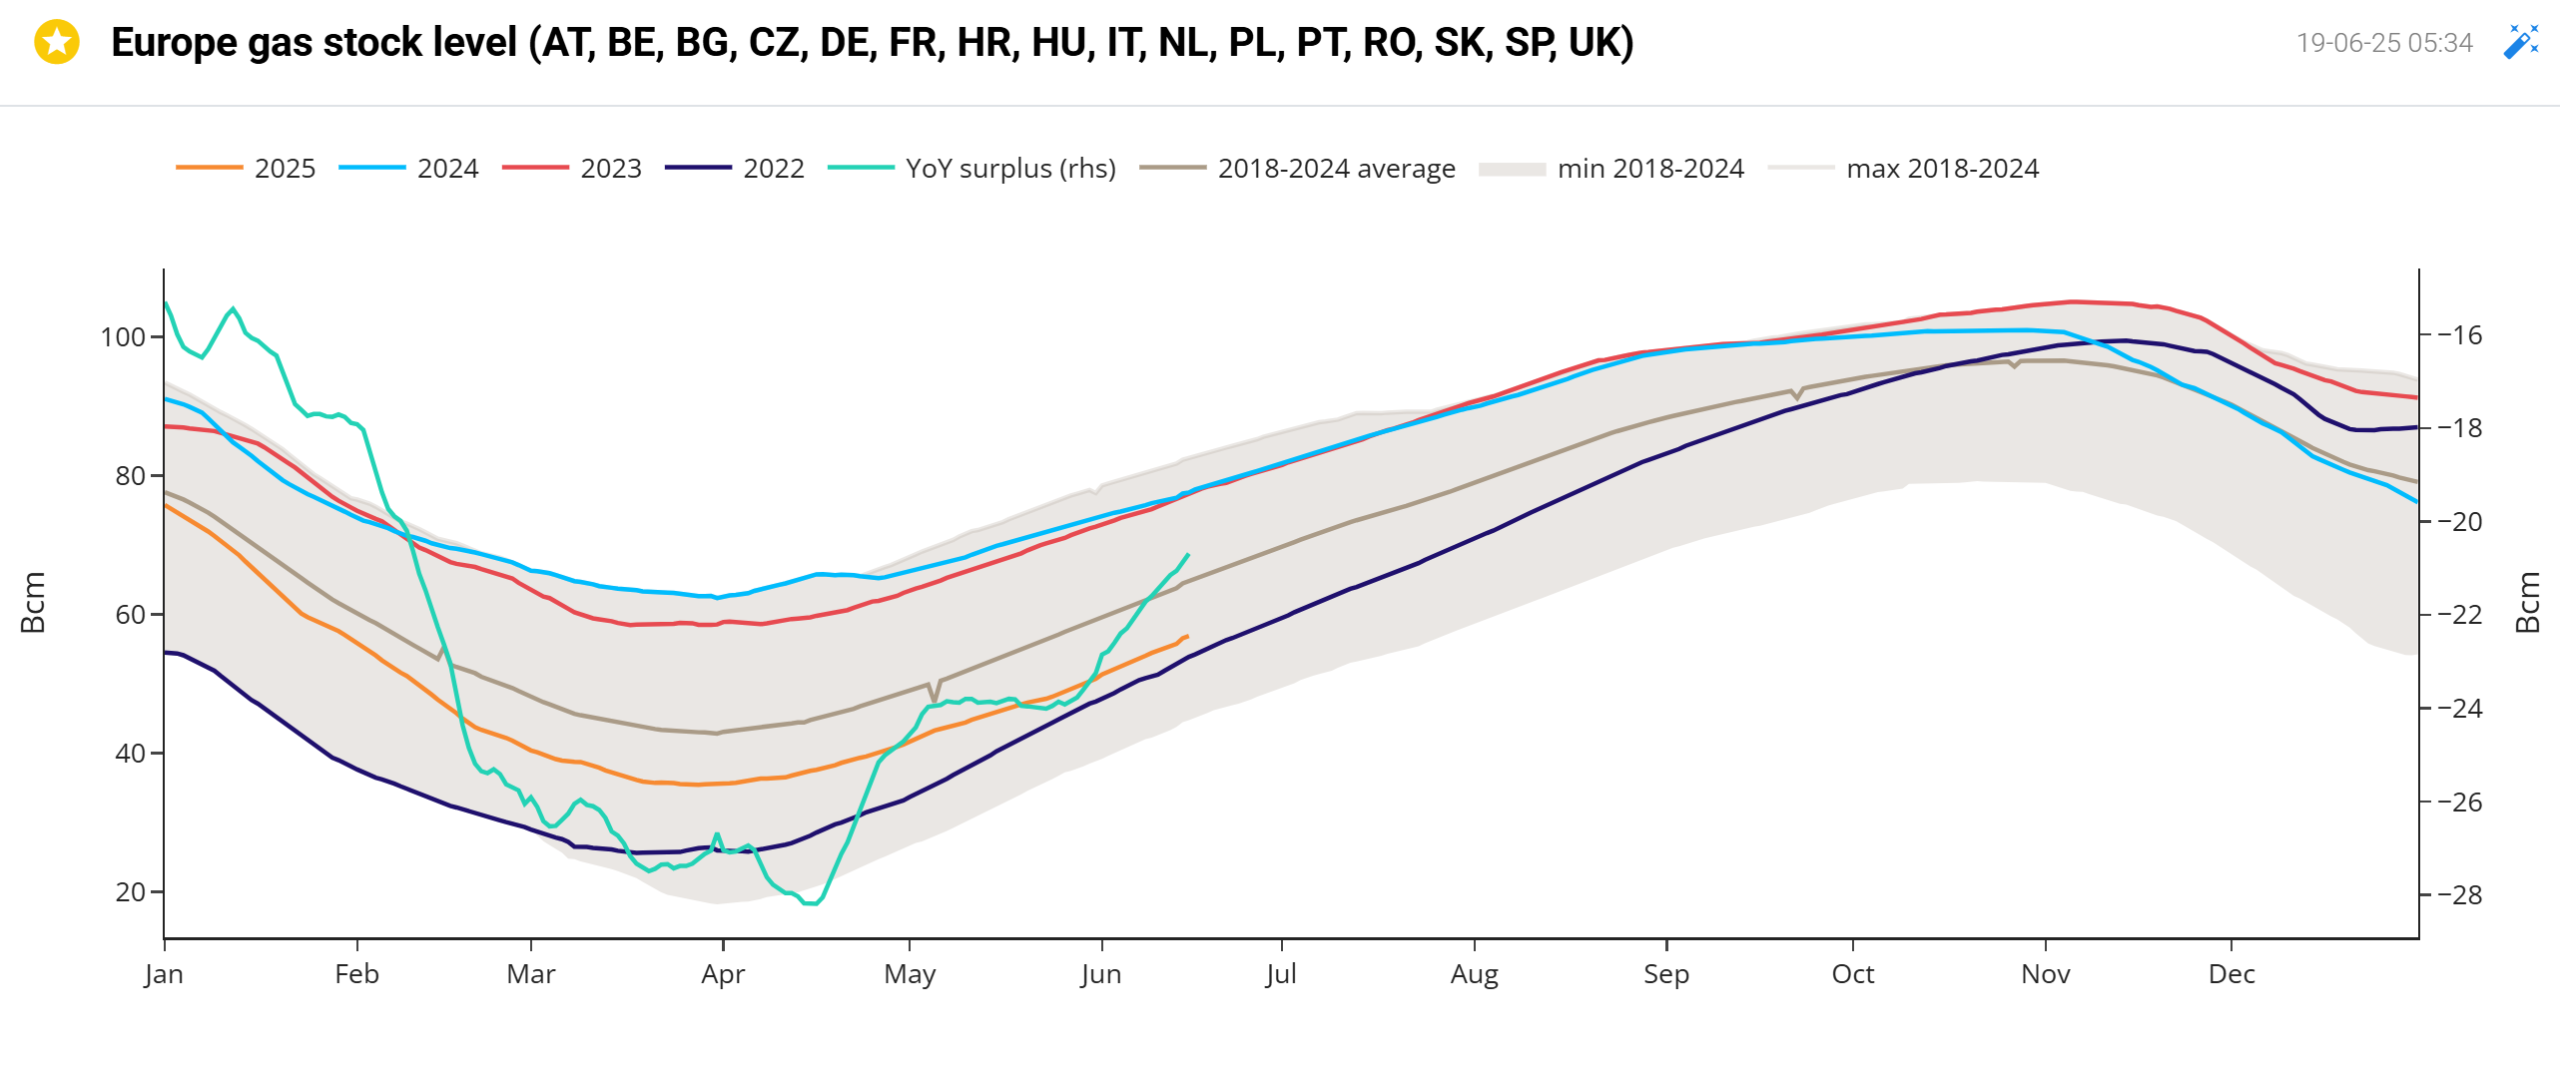
- European storage is on the right track, though the injection recovery is rising at a marginally shallower incline than previous years – please see chart below detailing European storage fullness 2018 to date.
- Nonetheless, consensus predicts we’ll just about make it to 83% in time for the heating season (1st Nov onwards).
- Near-term delivery prices remain well supported, with Winter-25 holding its ground above 100p/therm (108.2p/therm at the time of writing).
- Though prices further down the curve have been little altered by the Iran-Israel flare-up – reflecting (surely) market participant’s belief that future gas values will be lower subject to improved global LNG production in the coming months/years.
- Rumours abound that Canada could produce its first ever LNG this weekend, from the export facility in Kitimat, British Columbia.
- The facility represents just the first of a handful of Canadian LNG projects to begin production this year – significantly reducing sail time to Asian markets (reducing price support across the global LNG market).
- But for now, summer buyers are being forced to sit on the sidelines as the Middle East flare-up unwinds.
- The risk is very much front loaded, with traders most concerned about safe transit for LNG through the Strait of Hormuz (SoH).
- Were there to be a closure of the waterway, 20% of global LNG trade would be impacted, and the associated supply shortages would of course drive the market higher.
- European storage is at 54% versus the 5-year average of 64% – so not too far off the pace.
- On the trading side, clients running flexible capability are mostly watching from the sidelines as the Israel-Iran conflict develops – in the near term, talk of Iran regime change is pervading the airwaves.
- The USS Nimitz has also been redirected from the South China Sea to the Middle East (bringing the total number of US aircraft carriers in the region to two) – will the US engage directly…?
- This month’s UK gas Day-Ahead averages are at 87p/therm (or approx. 3p/kwh excluding non-gas) – so benchmark prices are creeping up as the month progresses.
ELECTRICITY & CARBON
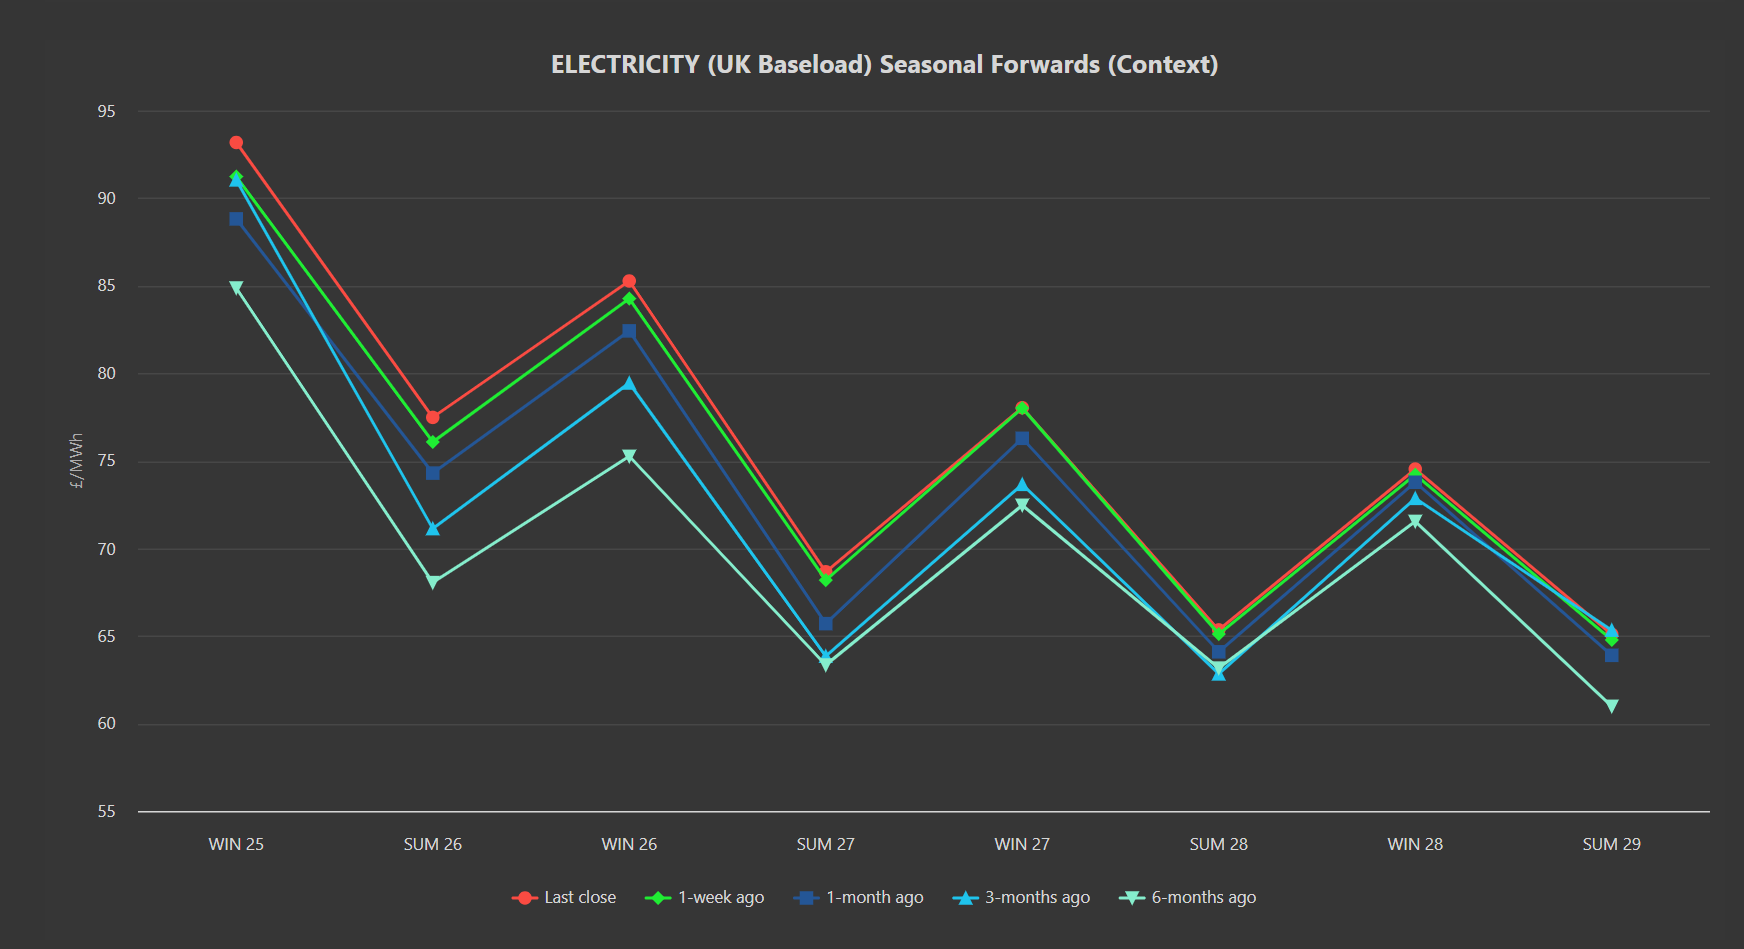
- Not surprisingly, near-term electricity prices (especially at the front-end) remain well-supported.
- Winter-25 is at £95/mwh (so an increase of 19% versus the lows we saw back on 1st May).
- Prices all the way down the curve are up (or commensurate) with those offered 1-week/1-month/3-months/6-months ago – please see chart below detailing Winter-25 to Summer-26 Seasonal Forwards.
- On the Carbon side of things, UKAs continue to drift toward parity with EUAs (following the “common understanding” reached between the UK/Europe to link emissions markets at the UK-EU summit in London on 19th May – UKAs remain well-bid sitting at £53.09 on the mid-price this afternoon.
- Today’s UK electricity generation mix is bearish in nature reflecting benign ‘summery’ weather conditions and limiting gas-for-power burn – specifically, renewables are contributing 43%, thermal at 14% (gas and coal) and low carbon at 24% (nuclear and imports).
- Electricity Day-Ahead averages for the month are creeping up in response to Iran-Israel risks – currently at £69/mwh (or approx. 6.9p/kwh excluding non-energy).
- On the trading side, clients running flexible capability are mostly watching from the sidelines as the Israel-Iran conflict develops.