



Thurs, 13th Feb ’25
GAS
- Intraday, Summer-25 delivery has once more fallen below Winter-25 (to the tune of 2p/therm at the time of writing).
- Prices have been threatening to drop off over the last few days, with markets feeling overbought/overcooked.
- Whilst it felt this morning as though the fall was driven by profit-taking, it’s also the case that a number of bearish rumours have begun to circulate.
- The European Commission’s announcement yesterday that is weighing new powers to cap gas prices will have encouraged speculators to close out long positions.
- Warmer weather is also being forecast for the back-end of Feb (limiting demand and slowing the rate of storage withdrawals).
- Trump has now lifted Biden’s pause on new Department of Energy permits for LNG export facilities– which clears the way for new shipment hubs to be developed.
- China has of course imposed tariffs on US energy imports – meaning Europe is much more cargoes from the US.
- Reports abound that Trump is determined to reach a peace agreement between Russia/Ukraine that would undoubtedly lead to a resumption of Russian pipeline flows via Ukraine into Europe.
- All this, plus the long-touted glut of LNG supply expected in 2026 from projects already under way, mean that whilst the uptrend is still in place, it’s by no means a one-way bet with Summer-25 only 47 days away.
- On the bullish side, Norweigian capacities are down due to unplanned outages at the Troll and Kristin gas fields (though Troll is still at 96% and the Kristin impact is negligible).
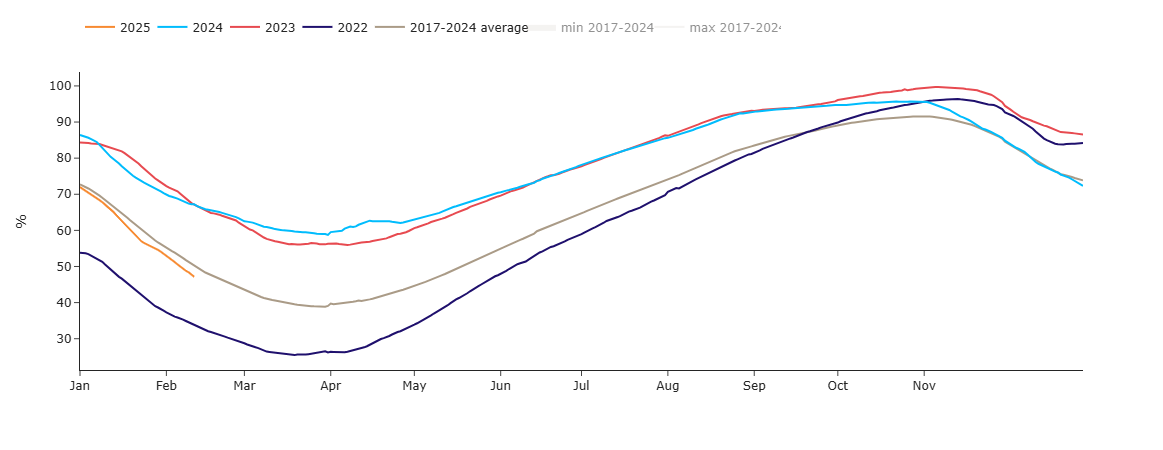
- Today, European storage is at 47% hvering just below the 7-year average (please see chart below).
- Monthly Day-Ahead averages will be softened by today’s price action, but are still high based on yesterday’s close – 136.071p/therm (or approx. 4.643p/kwh excluding non-gas).
ELECTRICITY & CARBON
- Looking to the continent, wind output forecasts have been revised downwards for the vcoming weekend (adding to the risk of increased gas-for-power burn and further storage withdrawals).
- Carbon prices were down yesterday, mirroring gas and heading back towards a retest of the €80/tn support level.
- The CoT (Commitment of Traders Report) confirmed speculators are net long again as of 7th Feb.
- Emissions prices are of course supported by bullish weather fundamentals with cold snaps to come amid poor (wintry) renewables outputs.
- Nonetheless, EUAs/UKAs remain correlated to gas which appears weakened on the news of US and Russia talks about a potential peace deal with Ukraine (and the possibility of a resumption of Russian gas flows).
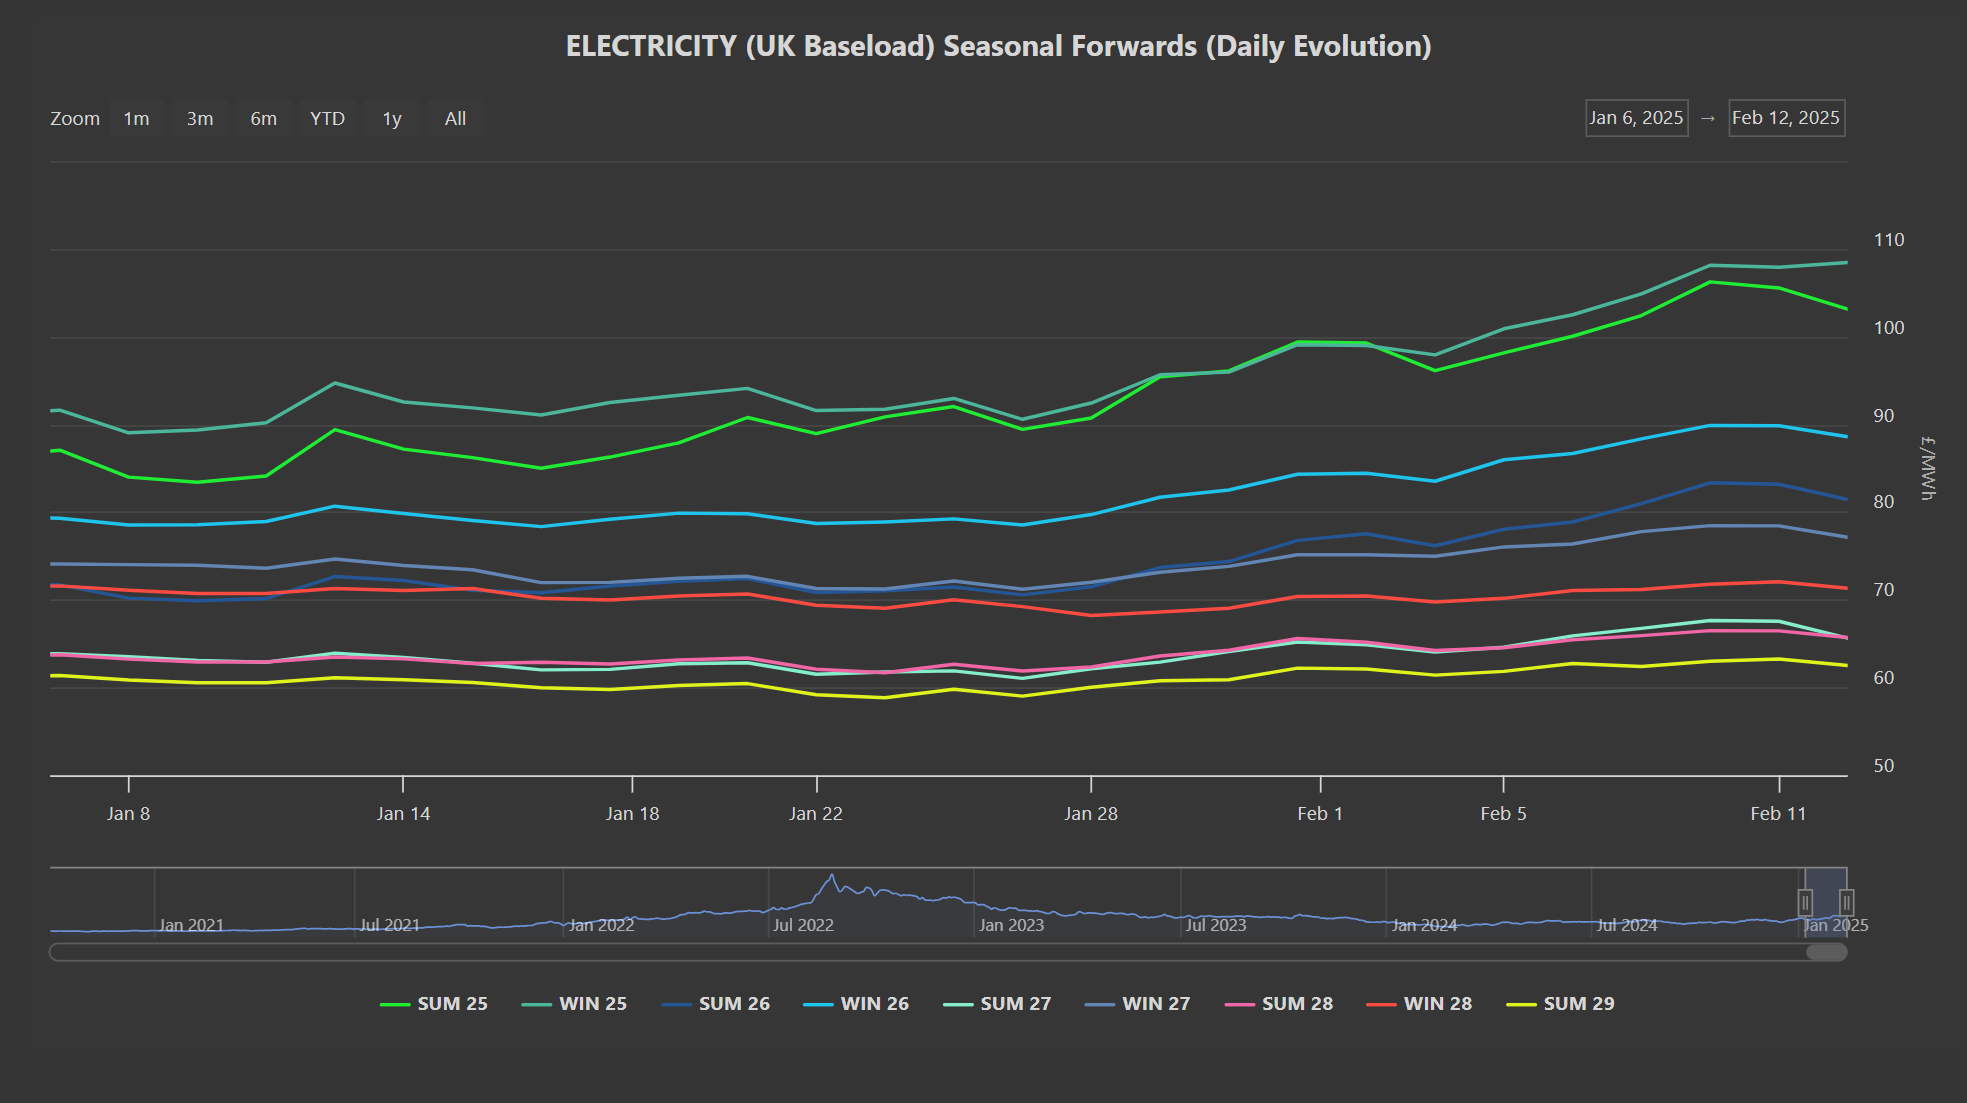
- Summer-25 electricity is dropping off, whilst Winter-25 is pretty flat (please see chart below).
- Today’s UK’s electricity generation mix has again been bullish with renewables contributing 17%, thermal at 53% (gas and coal) and low carbon at 21% (nuclear and imports).
- Monthly Day-Ahead averages so far for this month are at at £119.224 (or approx. 11.92p/kwh excluding non-energy).