



Thurs, 11th Dec ’25
GAS
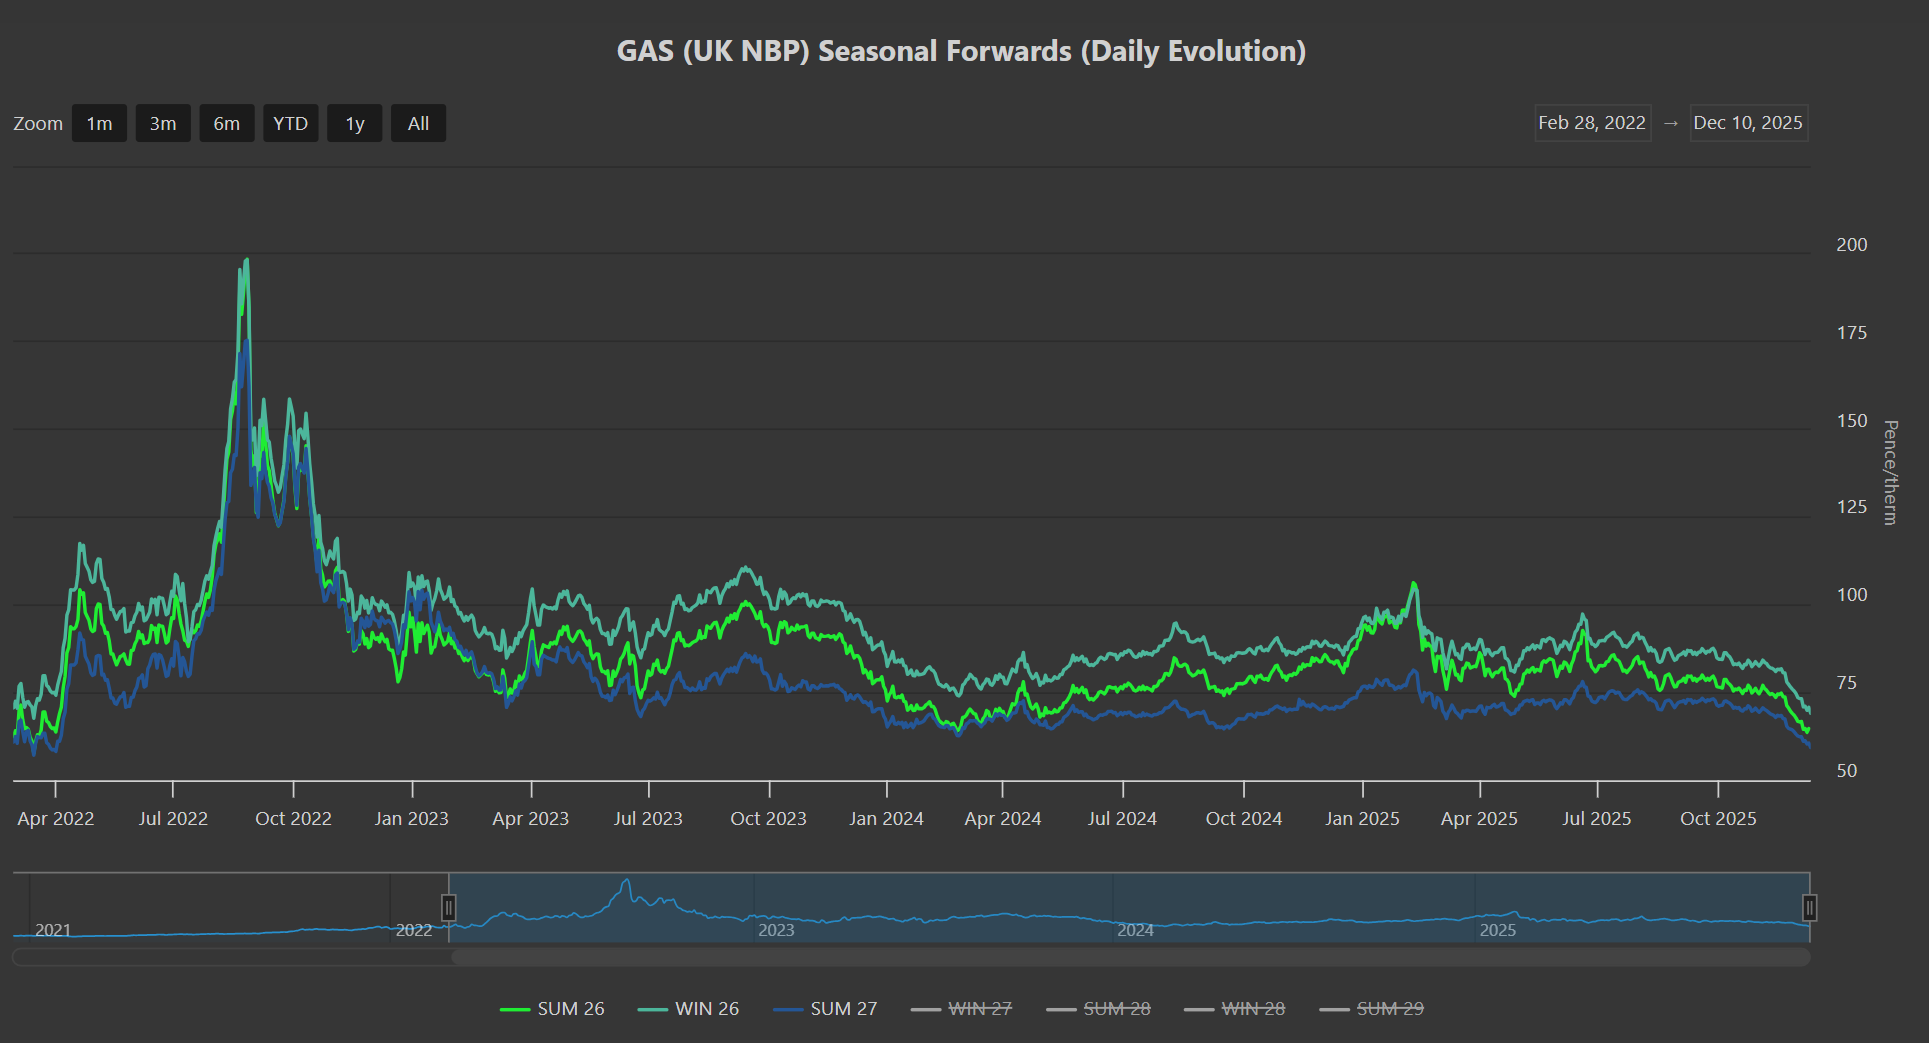
- Notably, delivery prices for the front 3-Seasons (Summer-27/Winter-27/Summer-28) have drifted to levels not seen since March ’22 (please see ‘Daily Evolution’ chart below).
- This despite, LNG gas imports into North West Europe having decreased month-on-month.
- Whilst heating demand is down off the back of unseasonably mild temperatures, Europe/the UK still need to draw consistent fuel flows, which is keeping the market from falling through the floor.
- The market’s bearish underlying sentiment is seemingly shrugging off any fears of supply tightness despite forecasts of falling wind outputs into next week.
- Whilst UK LNG imports/send-out feels a bit sluggish compared to European activity, we’ve nonetheless seen a redirection of Norwegian flows (with Franpipe having been re-routed through Vesterled).
- The combination of strong Norwegian pipeline flows versus lower wind (contributing to higher gas-for-power burn) signals that UK prices will likely remain neutral to bearish over the coming sessions.
- European net gas storage withdrawals are incrementally increasing with the very gradual onset of winter conditioning – today, European inventories are at 72% versus the 5-year average of 86%.
- Traders continue to eye the bearish impact of the return of Russian gas flows if/when peace talks bring about an end to Russian sanctions.
- Monthly Day-Ahead averages for December so far have fallen to 69p/therm (or 2.35p/kwh exc. non-gas).
ELECTRICITY & CARBON
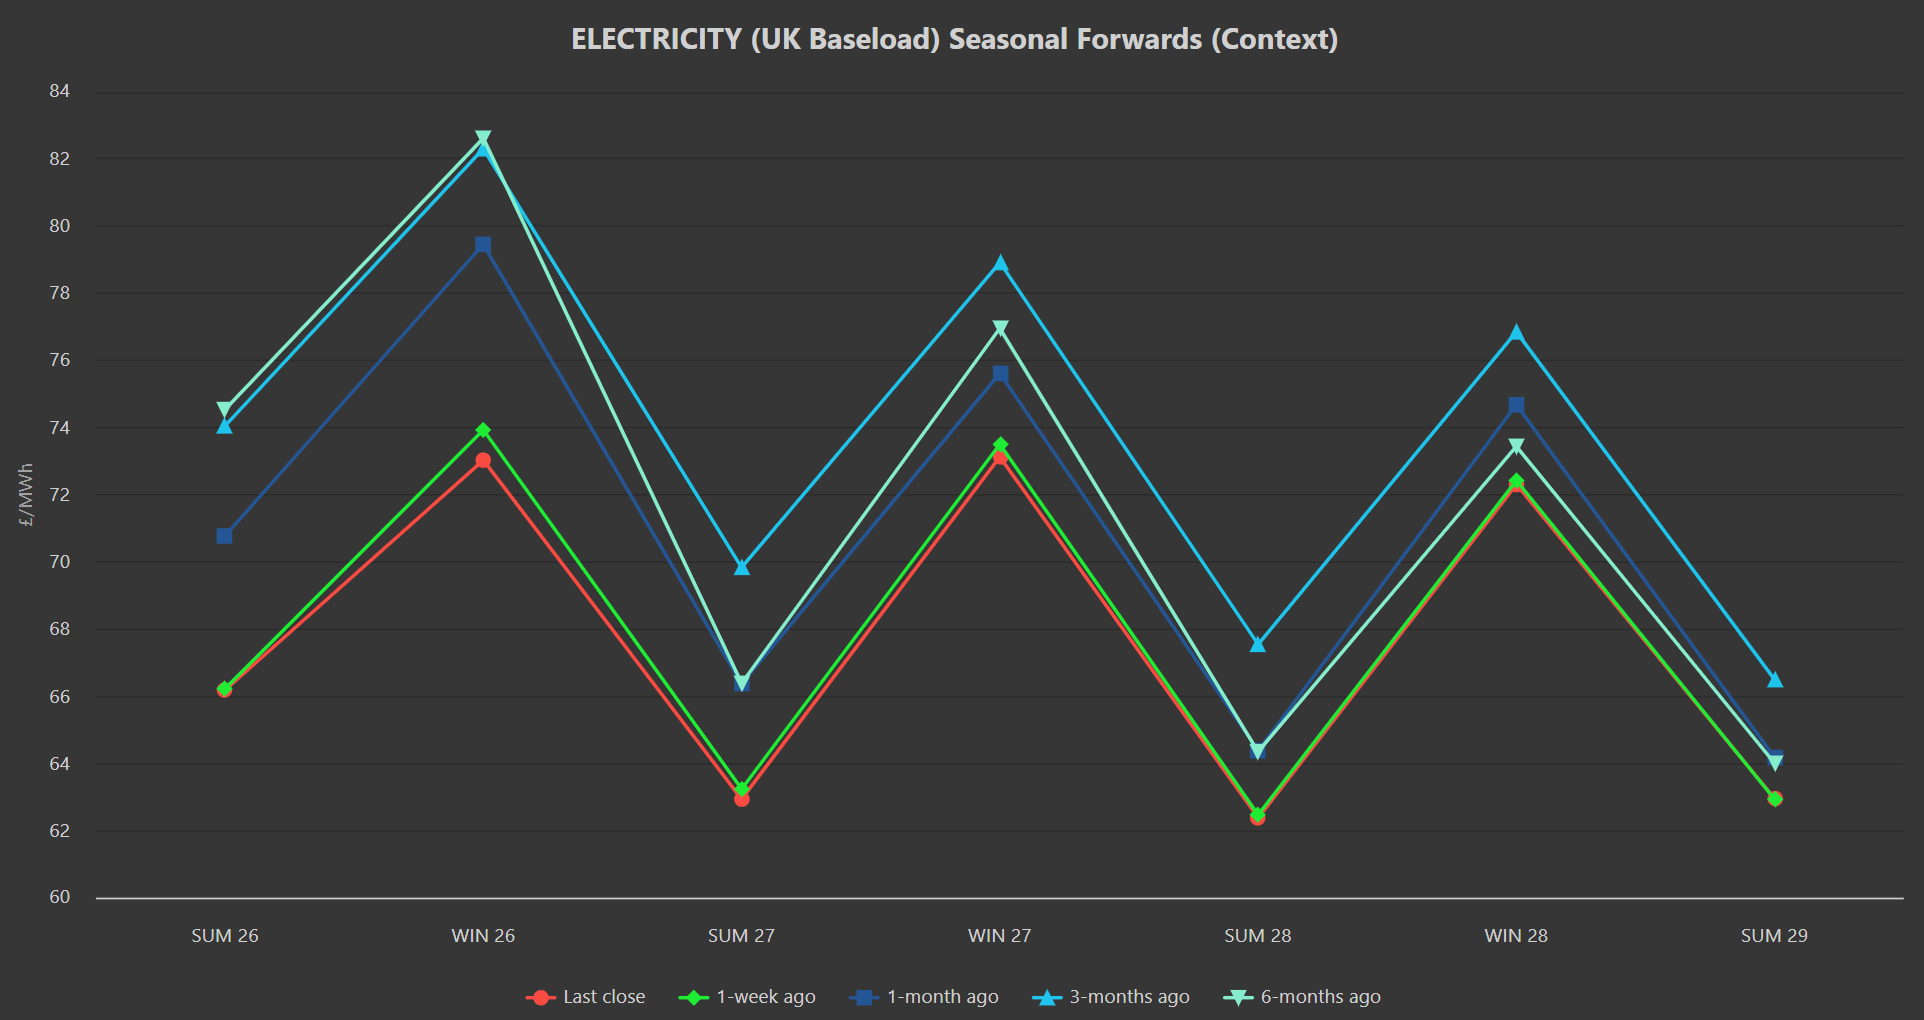
- Notably, Seasonal delivery prices all the way down the curve are lower versus 1-week/1-month/3-months/6-months ago (please see ‘Context’ chart below).
- On the Carbon side of things, UKAs went as low as £55.10 yesterday on the mid-price – their lowest level since late-Oct ’25.
- Rumours abound amongst Carbon traders that the EUA/UKA linkage talks are not going as well as hoped (a bearish driver for UKAs).
- Today’s UK electricity generation mix is neutral in nature, neither bullish not bearish – specifically, renewables are contributing 39%, thermal at 30% (gas and coal) and low carbon at 16% (nuclear and imports).
- Monthly Day-Ahead averages for December so far have fallen to £73/mwh (or 7.3p/kwh exc. non-energy).