Mon 23rd Sep ’24
GAS
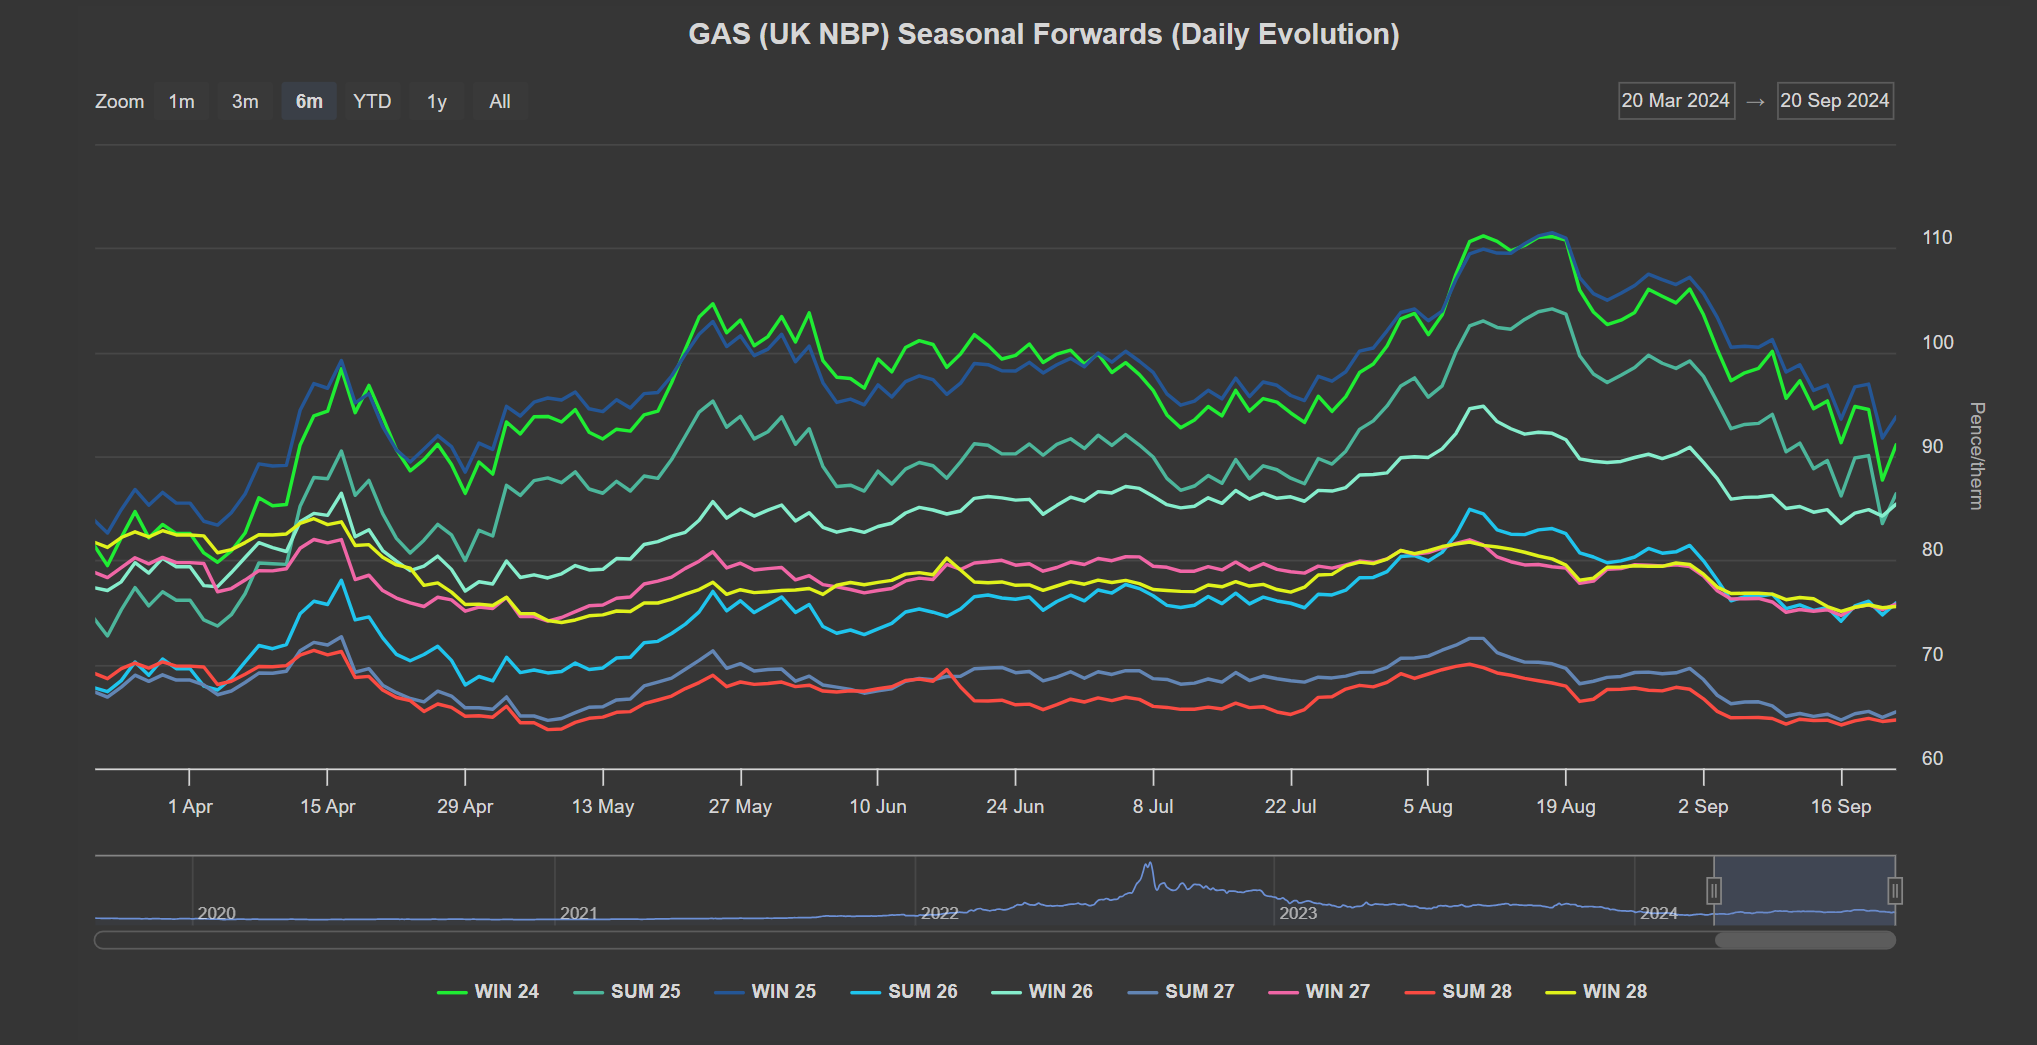
- With only 7 days of Summer-24 remaining, price-action continues to buck traditional norms with front-end Seasonal Forwards having fallen approx. 50% over the latter stages of Winter-23 (Dec ’23 to Feb ’24), only then to rise gradually thereafter until mid-Aug ’24 before falling back 25% off the back of late summer profit taking/repositioning (see Seasonal Forwards “Daily Evolution” at foot of GAS report below).
- To put it another way, we’ve had falling prices in winter, followed by rising prices across the summer – only then to fall with winter conditions on the horizon!
- The UK system was short at this morning’s open (demand forecast outstripping supply) – as such, prices started higher and have subsequently fallen back again.
- With winter now nearly upon us, market participants will surely begin to eye the potential supply impacts of geopolitical tensions across the Middle East and Eastern Europe.
- Consensus points toward Moscow preparing to attack Ukraine’s nuclear infrastructure with a view to Ukraine being forced to abandon its sustained counter-invasion of the Kursk region (the location, of course, of the transit point for the Sudzha pipeline).
- Israel has followed-up last week’s “device” attacks with an escalation of airstrikes on Hezbollah’s positions across Lebanon.
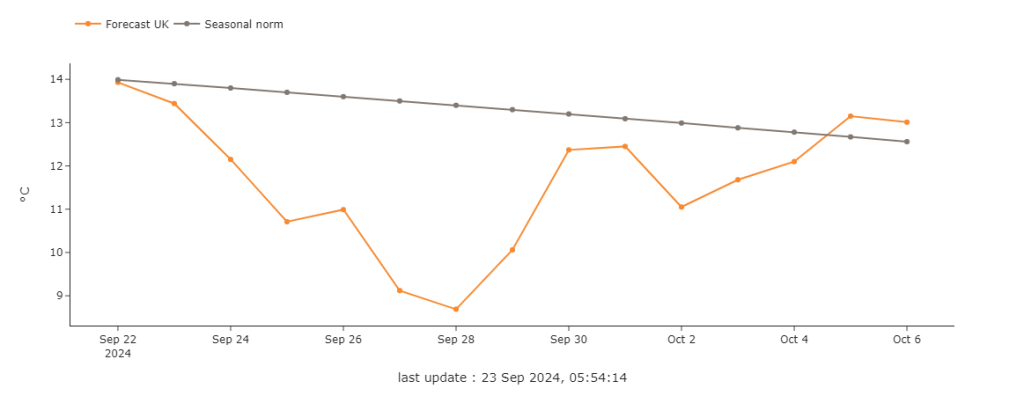
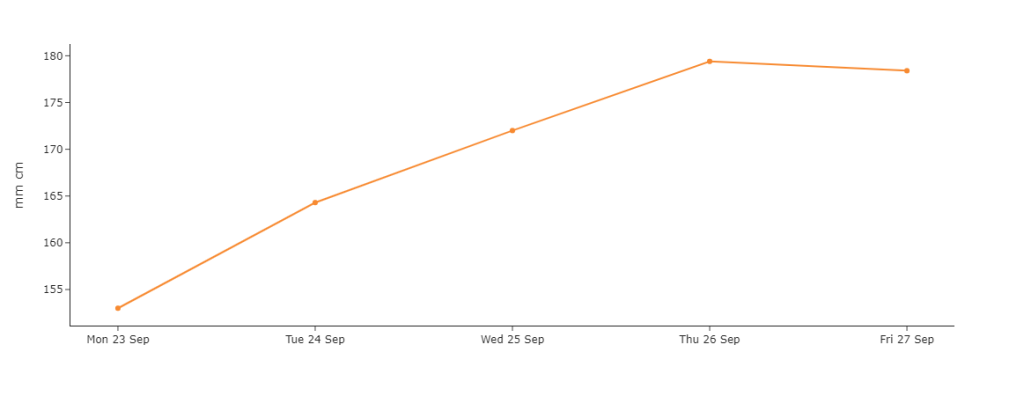
- Looking to more local drivers, lower temperature forecasts look set to increase heating demand:
UK Temperature Forecast
UK 5-day gas demand forecast
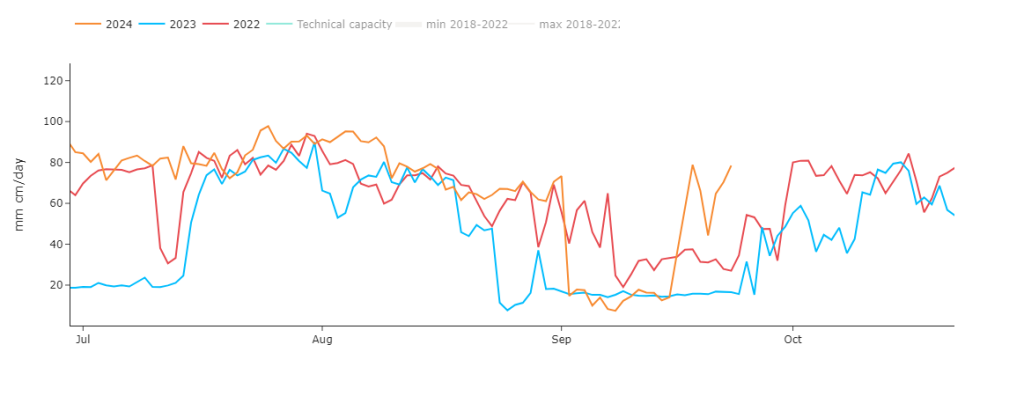
- Norwegian maintenance has all but ended with flows through Langeled to the UK now back online in earnest (with scheduled maintenance having ended earlier than ’23 & ’24):
Norwegian gas exports to the UK
- The lion’s share of remaining European offline capacity is expected to resume next week barring any last-minute extensions to maintenance.
- Clients with significantly open volumes for Winter-24 are now very much in the minority – with most having opted to heavily hedge Positions with winter conditions now only a week away.
- Monthly Day-Ahead averages so far this month are on target to achieve 85.8p/therm (or approx. 2.928p/kwh excluding non-gas).
ELECTRICITY & CARBON
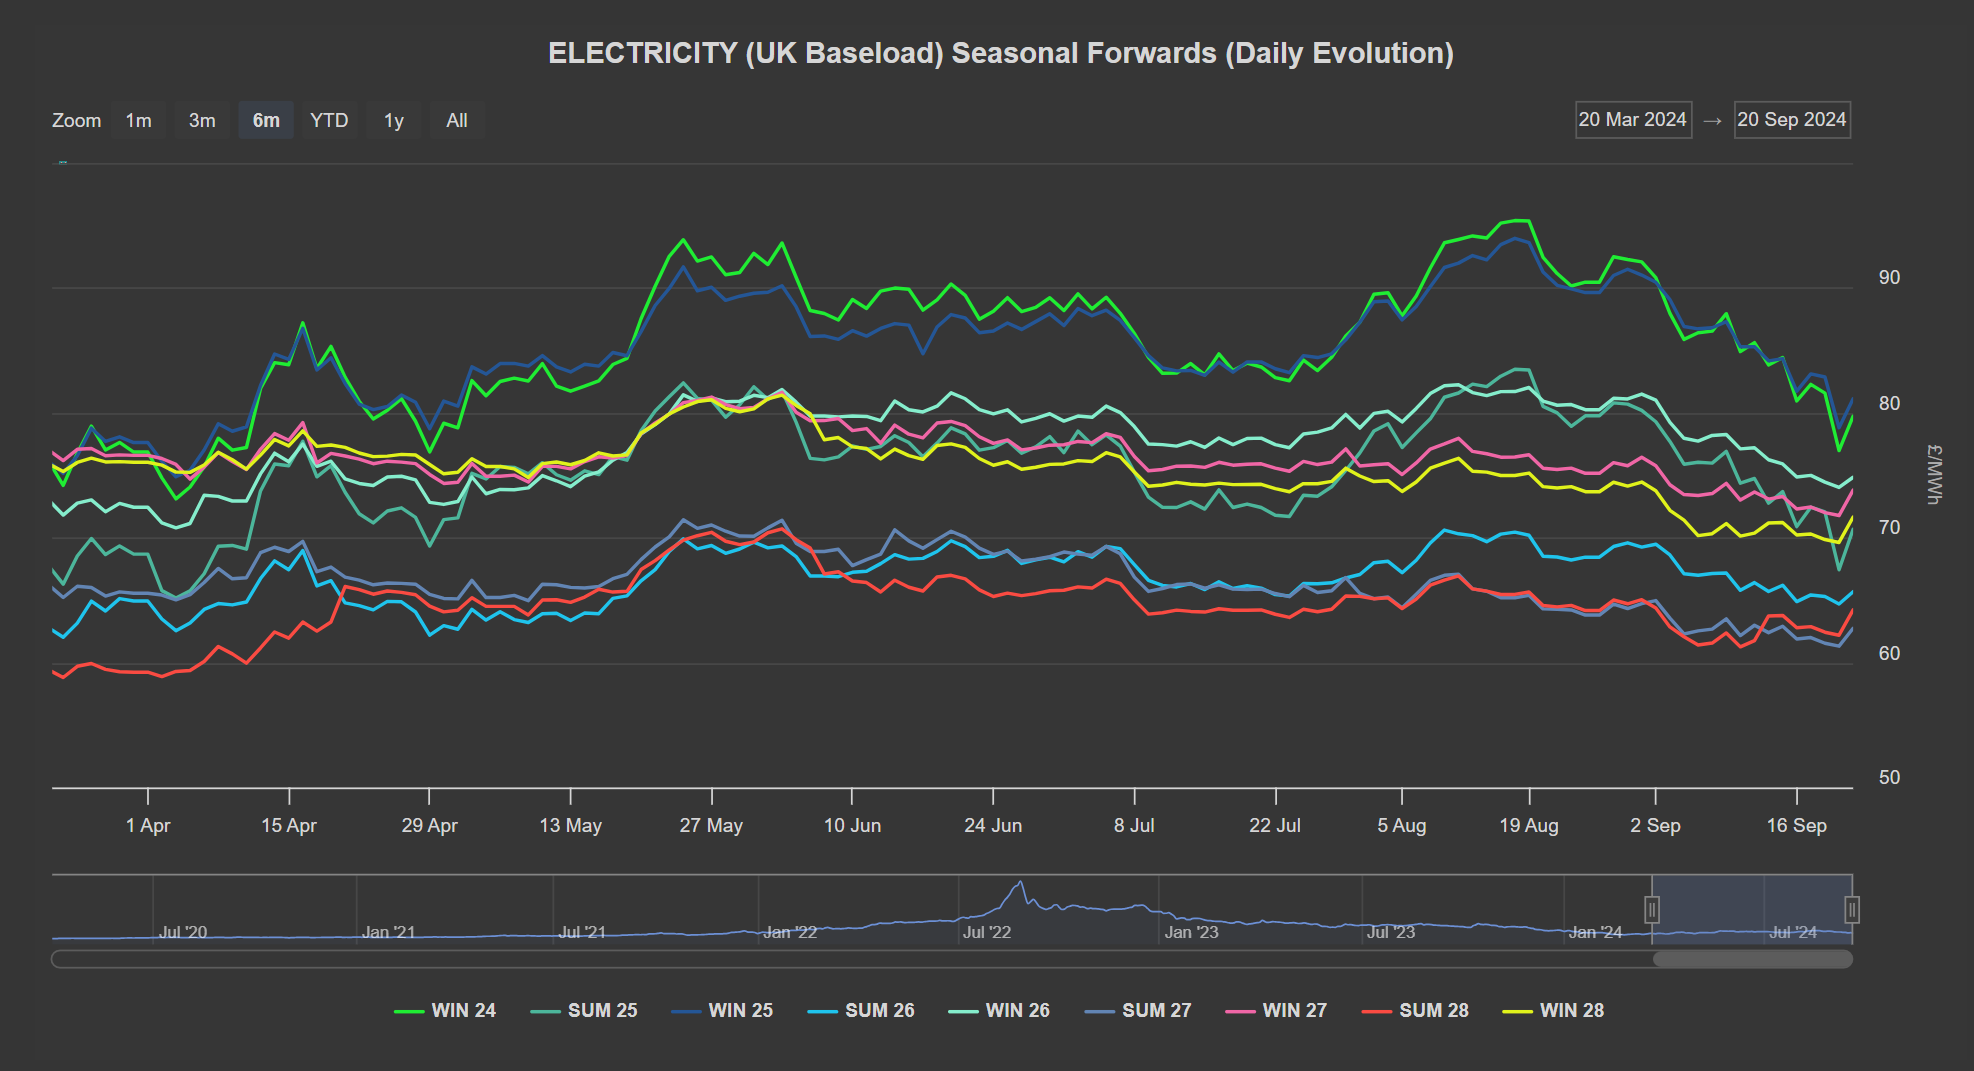
- With only 7 days of Summer-24 remaining, price-action continues to buck traditional norms with front-end Seasonal Forwards having fallen approx. 50% over the latter stages of Winter-23 (Dec ’23 to Feb ’24), only then to rise gradually thereafter until mid-Aug ’24 before falling back 30% off the back of late summer profit taking/repositioning (see Seasonal Forwards “Daily Evolution” at foot of ELECTRICITY report below).
- Looking to the continent for market drivers, temperatures will fluctuate around seasonal averages over the coming week, with a cold spell expected on Friday and over the weekend in Central-Western Europe.
- Wind generation outlook has been revised to calmer conditions, but periods of high output are still expected, particularly in Germany, starting tomorrow’s night until Saturday.
- Solar generation is forecast to be unstable this week due to low-pressure systems, with low production likely on some days.
- Wet conditions in Central-Western Europe will support increased run-of-river production and snowfall in the northern Alps, with a high chance of seasonal to above-normal precipitation continuing next week.
- On the Carbon markets, EUAs rebounded on Friday, off the back of a rebound in gas prices, following a volatile session on Thursday due to an as-yet-unconfirmed Ukraine-Azerbaijan deal transit extension.
- EUAs were still down 2% on the week nonetheless with the Dec ’24 benchmark contract closing at €63.39/tonne.
- Down the European electricity curve, prices rebounded to finish the week following the uptick in gas and carbon prices.
- As predicted last week, UKAs are retesting £39/tonne which marks the bottom of a confirmed daily descending trend channel – both EUAs and UKAs are now in a bearish trend.
- Our electricity generation mix is bullish in nature today with renewables contributing 19%, thermal at 43% (gas and coal) and low carbon at 22% (nuclear and imports).
- Monthly Day-Ahead averages so far this month are on target to achieve £77.994/mwh (or approx. 7.8p/kwh excluding non-energy).
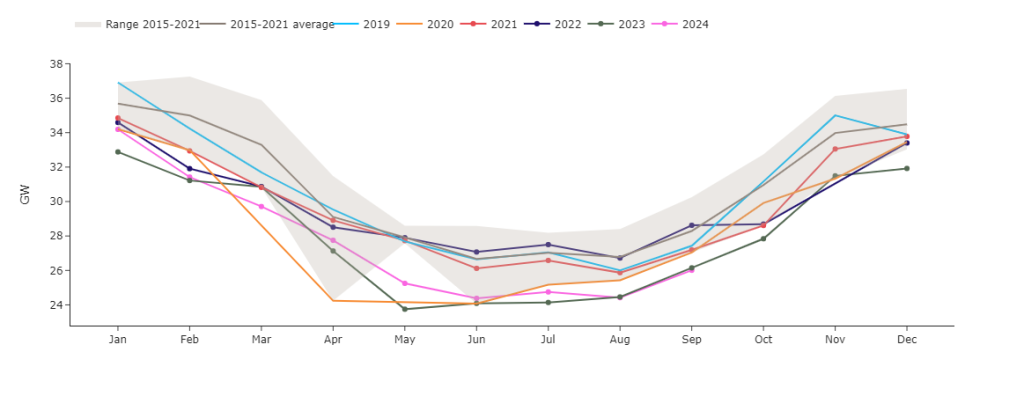
- Power load demand has begun its upward trajectory heading into Winter-24:
Monthly UK average power load