



Mon, 1st Dec ’25
GAS
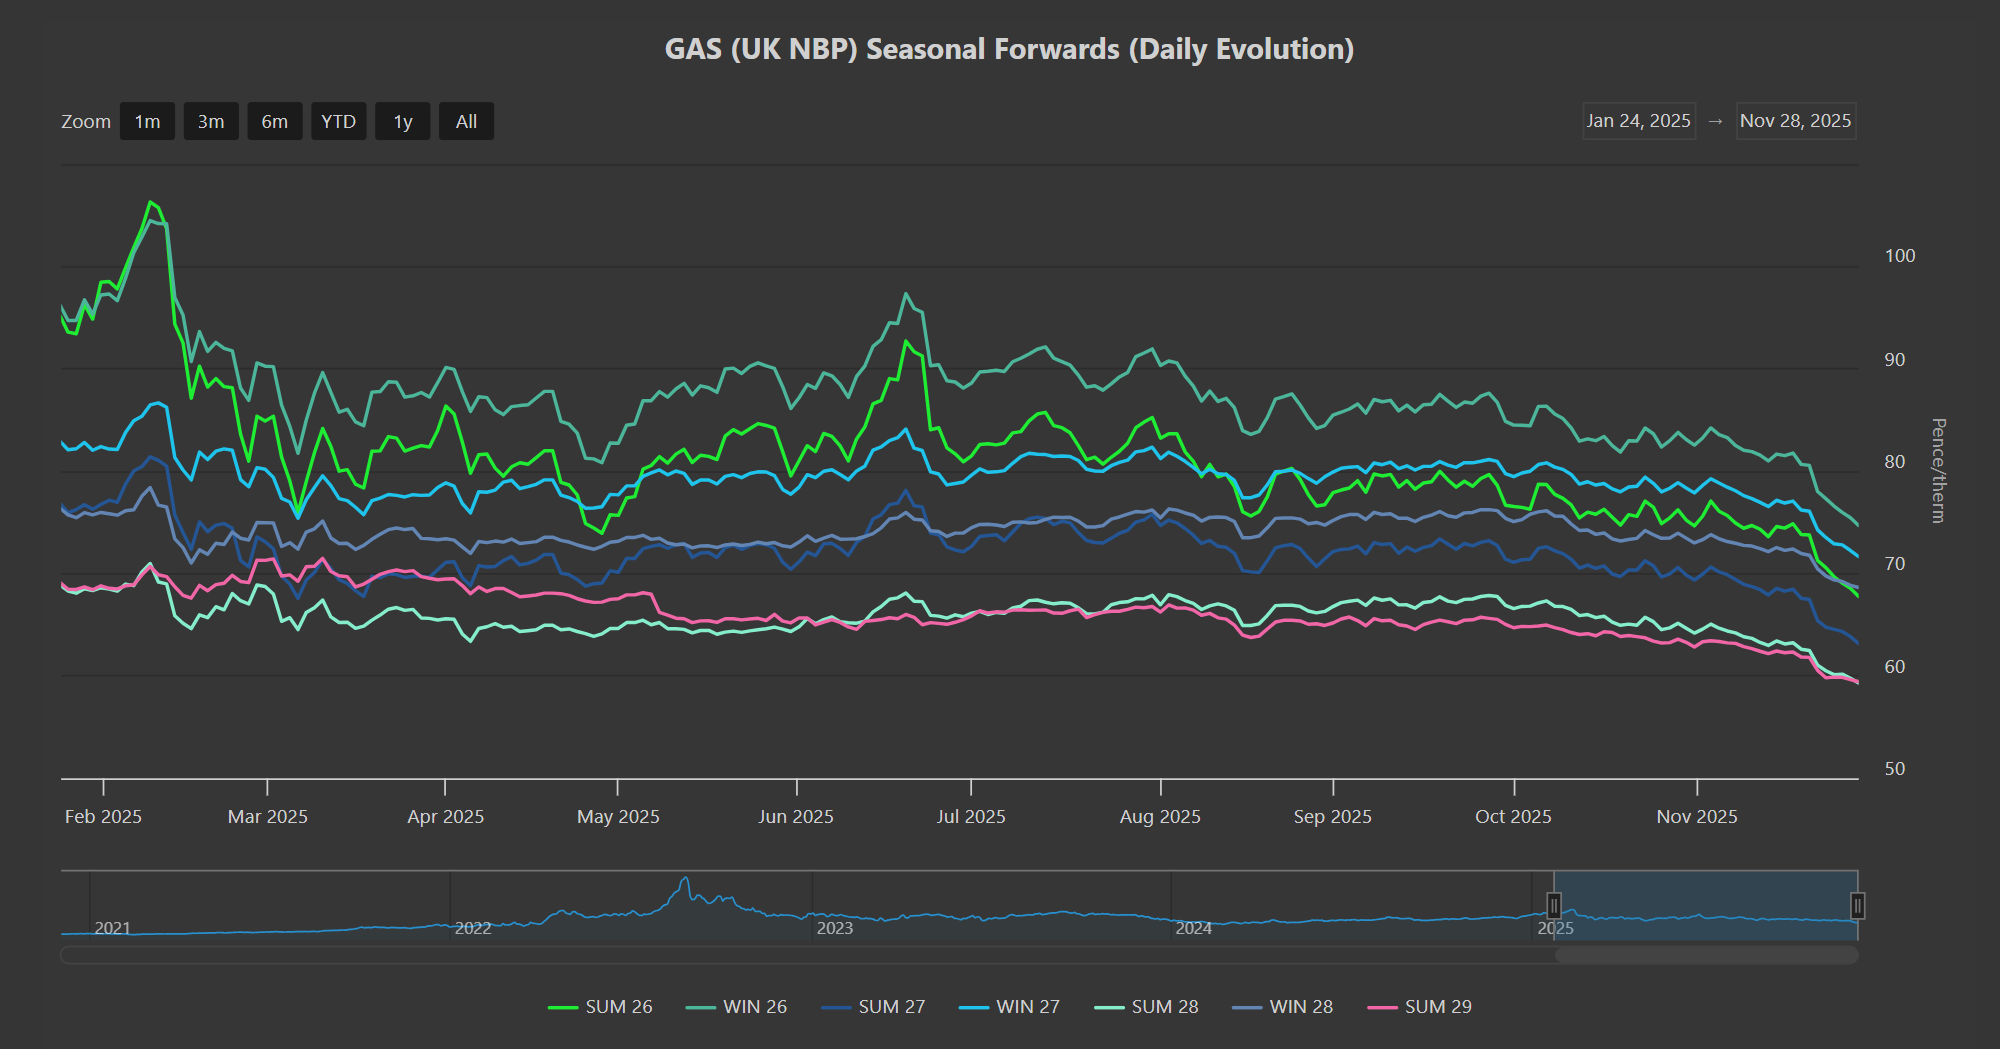
- Seasonal Forwards are generally around 30% lower than the prices printed at the height of last winter, and very clearly on the slide again today (for the 7th consecutive session) – please see chart below.
- This morning, near-term delivery (Day-Ahead/Week-Ahead/Month-Ahead) opened lower off the back of a long UK system (supply outstripping demand forecast).
- The primary bearish drivers are steady supply, milder weather, ongoing Ukraine/Russia talks, and rumours of an LNG glut come next summer.
- Temperature forecasts are predicting near or above seasonal norms across most of Europe for the coming fortnight, inevitably lowering heating demand (and gas for power burn/storage withdrawals).
- European storage fullness is at 76% versus the 5-year average of 87%.
- Monthly Day-Ahead averages for November came in at 76p/therm (or 2.6p/kwh exc. non-gas).
- Monthly Day-Ahead averages for December so far are at 73p/therm (or 2.5p/kwh exc. non-gas).
ELECTRICITY & CARBON
- Electricity Seasonal Forwards all the down the curve are mirroring bearish gas movements.
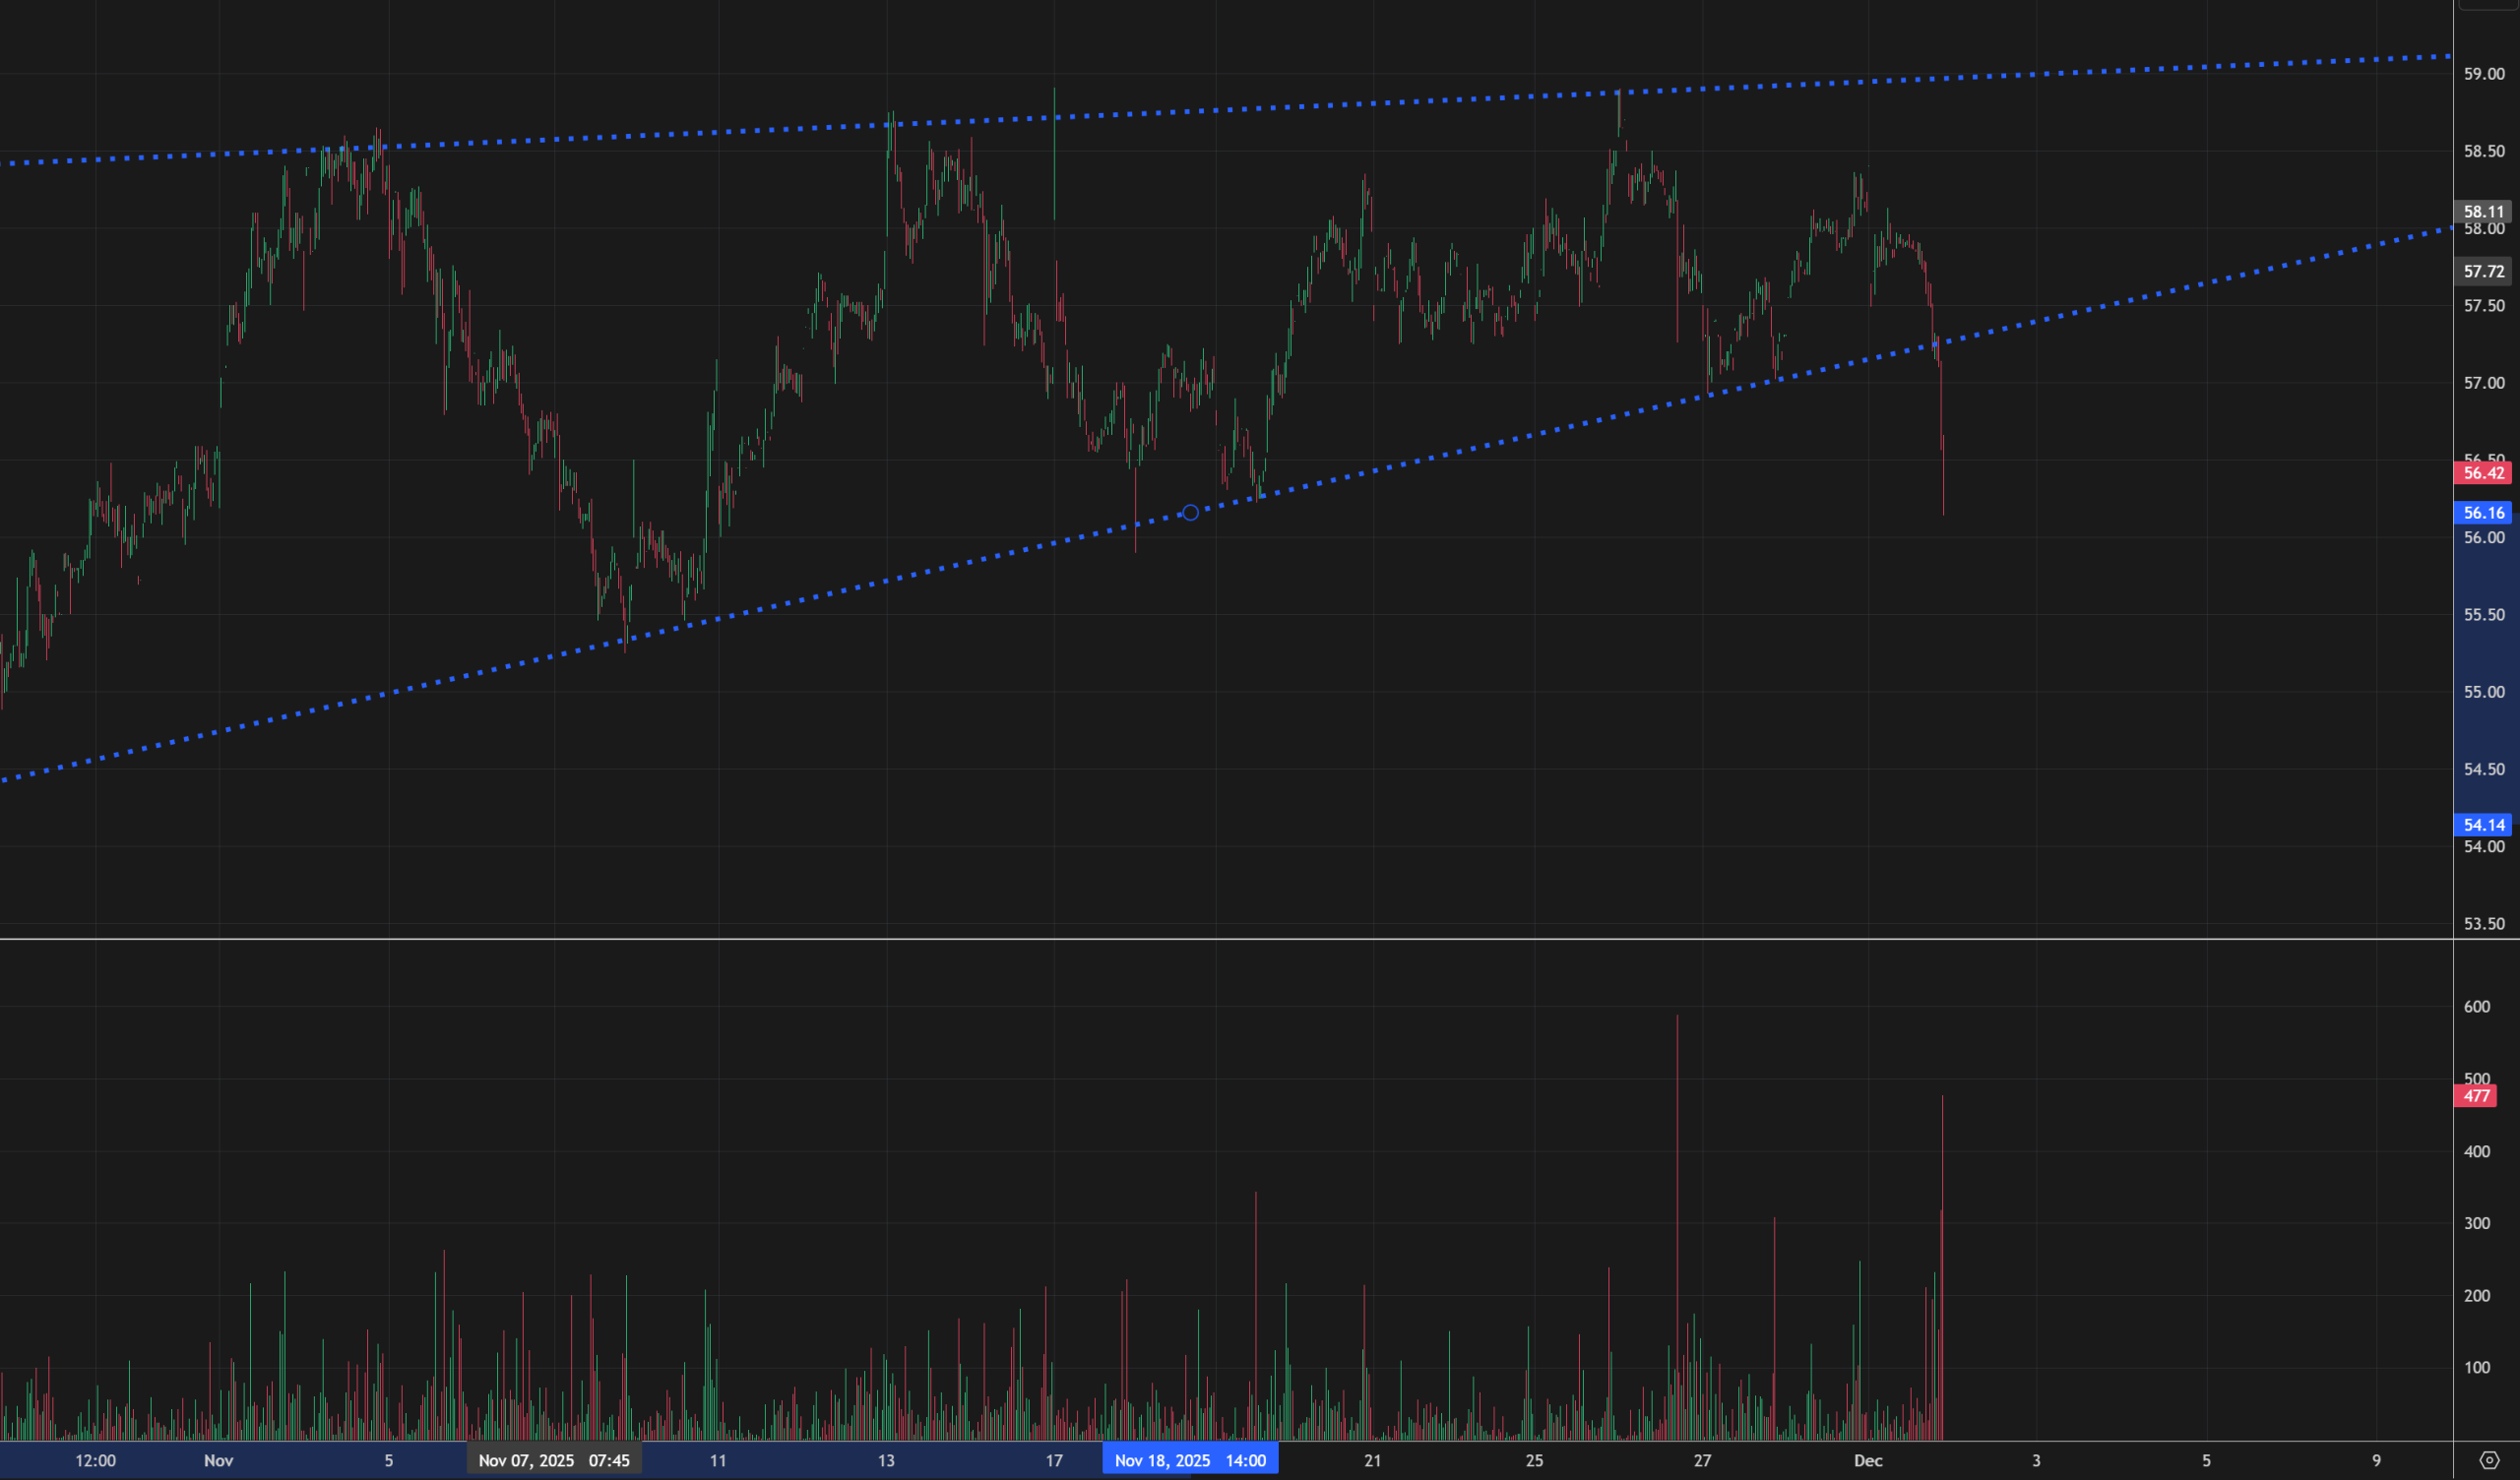
- On the Carbon side of things, UKAs continue to trade below the increasingly important resistance level of £58.50/tn, but have failed to fall back (yet) to the increasingly important support level of £55.50/tn – however, as per the chart below, prices on the 15-minute charts have just fallen through key support following a week of bulls failing to break-above key resistance levels.
- Next stop is likely to be a retest of £55.50/tn.
- Today’s UK electricity generation mix is neutral in nature, neither bullish not bearish – specifically, renewables are contributing 36%, thermal at 28% (gas and coal) and low carbon at 20% (nuclear and imports).
- Monthly Day-Ahead averages for November came in at £77/mwh (or 7.7p/kwh exc. non-energy).
- Monthly Day-Ahead averages for December so far are at £74/mwh (or 7.4p/kwh exc. non-energy).